| Sep 28, 15:27 |
| Oct 02, 14:56 |
| Oct 01, 14:15 |
| Oct 01, 06:24 |
| Sep 28, 07:19 |
| Oct 02, 15:48 |
| Sep 29, 14:48 |
| Sep 29, 16:45 |
| Sep 29, 15:31 |
| Sep 30, 03:47 |
| Sep 29, 17:55 |
| Oct 02, 08:30 |
| Sep 29, 08:54 |
| Oct 01, 11:27 |
| Sep 30, 08:23 |
| Sep 28, 19:22 |
| Balance of payments accounting of RRF transfers |
Question:
Do you by any chance know where the EUR 9bn will enter in the Hungarian balance of payments? Is it mixed between the transfers of the current account and the capital account?
The question was asked in relation to the following story: Current account moves to deficit of EUR 244.6mn in Q2
Answer:
We do not think it is possible to say in advance where the RRF will pass through. Usually, most of the EU funds are classified as capital transfers and we guess this will also apply for the RRF, since the funds will be mostly allocated to infrastructure. We cannot rule out that some part, possibly small, will be accounted in the current account though.
| Ask the editor | Back to contents |
| Potential govt action to lower tariffs |
Question:
Assuming that, due to the very limited fiscal space, the government opts not to offer a price relief package for gas and power tariffs (like a cap or a reduction in taxes), but instead politically pressures the regulatory agency to concede very small tariff hikes, wouldn't this burden end up falling on the public budget in the end, since major energy companies are state-controlled?
The question was asked in relation to the following story: Energy minister says natural gas tariffs shouldn't rise next year
Answer:
I would be surprised if the government launched an explicit freeze for power or natural gas prices since this hasn't been talked about at all. The government is rather likelier to limit the ability of companies to raise tariffs, but, again, much will depend on where prices actually go, though we are indeed moving to crunch time. To recall, the URE will make its tariff decision by mid-December, but the companies are likely to submit their applications fairly soon. Some years there are leaks about the levels, but some there aren't, so we shall see.
It is true that if the tariff increases are too little to match real costs, the companies in question will suffer and their profits will shrink and thus so will their dividends. But they are controlled by and large through minority stakes and so the government might see that as a price to pay. Dividend income is to rise in 2027 to some PLN 13.9bn from PLN 9.1bn this year, but perhaps the government doesn't see this as a major factor, especially as Orlen will likely generate a huge profit.
| Ask the editor | Back to contents |
| MPC guidelines note NBP selling FX to EC |
Question:
On page 6 of the document, it reads: "Banking sector liquidity in 2027 will be positively affected by the purchase of foreign currencies by NBP, mainly from the Ministry of Finance. The NBP sale of foreign currencies mainly to the European Commission, and a rise in currency in circulation, will have a curbing effect on the level of banking sector liquidity."
I am confused about the part which says that the NBP sells foreign currency to the European Commission. What does this refer to exactly? Any insights about this question would be very much appreciated.
The question was asked in relation to the following story: MPC retains 2.5% y/y target for 2027, warns of high inflation in H2 2026
Answer:
I think this is mostly a translation problem. The Polish version translated directly reads as:
"In the direction of limiting the level of liquidity there will be the sale of foreign currencies by the NBP, primarily to meet the needs of the European Commission, and the increase in cash in circulation."
That became "The NBP sale of foreign currencies mainly to the European Commission, and a rise in currency in circulation, will have a curbing effect on the level of banking sector liquidity," but you can see how that changes the meaning.
As always, the Polish version is the official one and so we can chalk this up to a mistranslation.
| Ask the editor | Back to contents |
| Latest financing plan / issuance progress |
Question: Where is the latest financing plan / issuance progress update from the finance ministry?
The question was asked in relation to the following story: Treasury fails to fulfil September borrowing plan
Answer: The most recent official document from the finance ministry on 2026 funding needs and plans is available here. Total gross financing needs are estimated at RON 278.5bn (EUR 54bn) in 2026. Funding must cover the projected 6.2%-of-GDP budget deficit (RON 127.8bn) and maturing debt repayments (RON 150.7bn). The authority plans to raise RON 160bn from the domestic market.
The finance ministry also publishes monthly public‑debt reports here. In the "Public debt bulletin" linked above, you can see that funding needs were 50.3% covered by end‑July. This means the state raised RON 139.9bn, of which RON 135bn by the central administration, RON 1.5bn by regional governments and RON 2.6bn through cash‑management instruments. External borrowing reached RON 37.9bn (foreign bonds and IFI loans), while domestic borrowing stood at almost RON 98bn by end‑July.
However, we have followed the finance ministry's bond issuance and private placements through end‑September, showing that the Treasury raised RON 145.5bn via government bonds, including retail and private placements, as well as foreign bonds (EUR 3bn and USD 2bn issued in February). Altogether, this covers about 52.2% of estimated financing needs. This figure excludes IFI loans and funding from NRRP and SAFE.
The external funding target stands at EUR 21bn, of which EUR 10bn through foreign bond issuance, with the remainder expected from private placements and loans under SAFE, RRF and IFI instruments. However, a finance ministry representative said earlier in September that authorities may scale down the foreign issuance plan due to the ongoing political crisis.
| Ask the editor | Back to contents |
| Will new PM get the votes on Tuesday to form a government |
Question:
Do you have a view in terms if the new PM will get the votes on Tuesday to form a government?
Answer:
I do not think that the Muresan government has good chances to win a vote of confidence (which is eventually scheduled for Wednesday, not Tuesday as initial reports suggested). The PM-designate does not have enough votes for majority yet since the PSD is still not supporting it. Overall, I think though that the chances for an agreement are relatively slim as Muresan and PSD leader Grindeanu continued to bicker with neither of the two showing willingness for reconciliation. Grindeanu is possibly expecting that president Dan would grant him the mandate for attempting to establish a government as a next step and not choose the option of early elections if the Muresan government fails to pass a vote of confidence. Dan has been vague on the issue and did not specifically say that he would step to dissolve the parliament although if the Muresan government fails to get an approval on Wednesday, the conditions for calling early elections would be met. Dan has indicated he does not want AUR to be part of the ruling (and the SDP would have problems to garner majority without AUR) but in case of early elections - polls show that AUR will be the largest party. So both scenarios should look undesirable for the president. The SDP should not be willing to go to early elections either as it has collapsed in polls and will lose grounds in a new parliament. So I think that the SDP might eventually compromise and at least agree on a rotation government (which Muresan does not prefer but has said would accept) and therefore, I think there are some chances for the Muresan government to pass in case they agree on rotation. But this all will depend on the PSD changing their stance in the next two days, which might depend on what signals the president would give about his plans what happens next, in my opinion.
The question was asked in relation to the following story: Parliament to hold vote of confidence in Muresan government on Wednesday
| Ask the editor | Back to contents |
| Data on FX flows |
Question:
Do you have data summarising the FX flows affecting Kazakhstan's market?
The question was asked in relation to the following story: FX sales from sovereign fund equal USD 200mn in September
Answer:
Data covering all relevant flows since Jan 2023 can be found here.
| Ask the editor | Back to contents |
| Factors affecting deceleration of household lending growth |
Question:
What causes the slowdown in household lending growth in Kazakhstan? Is the trajectory linked to macroprudential rules or changes to any of the subsidised lending programmes? Is there data for the average interest on new credit to households?
The question was asked in relation to the following story: Credit growth eases to 12.6% y/y in August
Answer:
There are several factors that support the NBK's overall effort to reduce household lending growth. Macroprudential regulations certainly have an impact, with several key reforms implemented over the last few years. To begin with, the NBK removed exemptions to the existing debt service mechanism, extending it to all loans. Essentially, it is based on a 0.5 cap, which means total monthly loan payments cannot exceed 50% of a person's income.
In addition, the NBK will introduce a coexisting cap on borrowers' debt-to-income ratio as of 2027. It has been in test mode since 2024, representing the ratio of a borrower's total outstanding debt (including a prospective new loan) to their annual income. The maximum DTI threshold will be set at the level of eight annual incomes. Based on current indications, there will not be differentiated caps for different loans.
In 2024, the central bank also set maximum amounts for unsecured consumer loans and micro-loans. This is important, as unsecured lending was a crucial driver of household credit growth, ahead of mortgages and auto loans. MFIs were prohibited from granting consumer loans to individuals with loan arrears exceeding 90 days. This was tightened further in 2025, when the debt-burden coefficient was reduced from 0.5 to 0.25 for borrowers who had experienced arrears exceeding 90 days over the last year.
The tightening also covered several other categories, including borrowers with bank arrears exceeding 30 days or microfinance arrears exceeding one day. Those who had qualifying debt during the previous 36 months or had undergone an ineffective restructuring during the last 12 months were included as well.
From the price side, the NBK reduced the maximum effective interest rates on unsecured loans (from 56% to 46%) and secured loans (from 40% to 35%). For short-term microloans, the reduction was even more significant (from 1% to 0.3%). As a whole, this reduces the cost of borrowing, but was also designed to steer lenders away from high-risk borrowers, as the regulated caps would fail to compensate for associated risks.
As of this year, all banks are obliged to comply with a 2% countercyclical capital buffer on retail lending. While this is not an explicit lending quota per se, it still gives banks an incentive to moderate credit extension. The related impact is amplified by NBK's liquidity management and sterilisation operations. Minimum reserve requirements were amended to absorb liquidity and shift financing away from consumer lending.
By end-2025, household credit growth eased to 19.8%, as opposed to 23.9% in 2024. Consumer credit slowed from 33.5% to 21.0%, while unsecured consumer lending slowed from 29.3% to 14.5%. Growth in new unsecured consumer lending slowed much more sharply, from 22.6% to 6.1%. Overall, the structural shift is clearly relevant and arguably driving the reduction.
At the same time, there are relevant cyclical factors as well, specifically when it comes to 2026. The real wage index has been negative throughout the first two quarters, which means some households may have become less willing to lever up once they stopped experiencing an improvement in real purchasing power. Inflation expectations also remain elevated, potentially contributing to risk aversion.
Beyond wages, it is likely that households also needed to adjust to the new tax environment in 2026. At this point, the effect of concerns about the VAT hike has dissipated, but it would have been relevant in H1. In a more general sense, there is an argument that the earlier credit boom is also affecting demand for new credit. While households can still consume, an increased share of their cash flow is already committed to existing debt, which can explain why credit growth has decelerated despite fairly positive retail sales growth.
With regard to subsidised lending programmes, there have not been any major changes affecting supply / demand. It may also be worth noting that the effect of recent monetary easing has not had much time to materialise yet. Finally, the interest rate data can be found here.
| Ask the editor | Back to contents |
| BCB's latest forecasts on GDP growth |
Question:
Have you seen this? https://www.bloomberg.com/news/articles/2025-09-25/brazil-central-bank-sees-economic-growth-slowing-to-1-5-in-2026 https://www.bcb.gov.br/content/ri/inflationreport/202509/rpm202509b1i.pdf
The question was asked in relation to the following story: OECD raises GDP growth forecast to 2.0% from 1.6% for 2026
Answer:
Looking at the news and report you sent, we noticed that they both date from September 2025, so it isn't clear if these were the right ones. The latest forecasts from the BCB for inflation and GDP growth were published on Sep 24, 2026, through the September Monetary Policy Report, and all information can be found in our piece which covered the report.
The BCB forecasts that GDP will rise 1.8% in 2026, which was a downward revision from the 2.0% forecast given in June. The BCB attributed this revision to a less favorable assessment of Q2 growth and weaker activity suggested by initial indicators for Q3. For 2027, the BCB forecasts GDP growth to slow to 1.4% on a restrictive monetary environment, reduced idleness in production factors, an uncertain external environment, and reduced credit and fiscal stimulus.
| Ask the editor | Back to contents |
| Employment package fiscal impact and liquidity management |
Question:
Do you have an estimate of current government liquidity against planned budget execution? Is the new employment package cash intensive?
The question was asked in relation to the following story: Kast announces USD 1.3bn employment package, targets over 100,000 jobs
Answer:
Employment package
Regarding the USD 1.3bn employment package, we believe that headline figure is mostly for effect and should not be interpreted as new cash requirements. About USD 1.0bn of the announced package is the government essentially saying it will execute its budget on specific lines (investment execution and supplier payments). Since 2026 inflation will be considerably higher than projected in the budget law, projecting full execution of the original budget in nominal terms isn't really a meaningful change compared to expectations. In the case of investment in particular, the biggest component of the announced package, there was significant underexecution in fiscal data through July, but this is common for the first few months of a new government taking office, and an acceleration of investment execution in the second half of the year was already anticipated.
We haven't mentioned this in an article yet, but Finance Minister Jorge Quiroz has already confirmed that the employment package doesn't change fiscal projections.
The reality is that the government has already taken the policies that it thinks are best to address the employment issue over the short- and medium-term, given fiscal constraints. For the short term, they launched several policies to revive the housing market and subsequently construction activity, which has been depressed since the pandemic, since this seems the most obvious and fastest way for the economy to recover some of the jobs lost over the past few years. Over the medium term, the government knows the recovery of the labor market will depend on economic growth regaining momentum, so it significantly cut corporate income taxes with its omnibus bill and introduced a tax stability regime, believing this will lead to a broad investment-led growth process that will eventually increase labor demand. In the meantime, the unemployment issue keeps making headlines every time the monthly jobs report is released. Since it wouldn't be well received for government officials to say "we have already done what we can to stimulate job creation, we now have to wait," they keep announcing new marginal policies and try to sell them as bigger measures than they actually are.
Government liquidity and management
Regarding government liquidity, the monthly releases on the fiscal balance and below-the-line financial transactions show that the government built up USD 3.5bn in cash balances through July. This is consistent with the budget office's report on Treasury assets, which shows that the government's holdings of highly liquid assets increased by nearly USD 4.2bn through July after ending last year at virtually zero. The previous government ran on cash buffers of nearly zero in 2024 and 2025, as it ran higher-than-expected deficits but tried to get by without increasing the borrowing ceilings for each year that were set in the budget law. The Kast administration raised the 2026 borrowing ceiling in part because FinMin Quiroz wanted to rebuild cash buffers to more normal levels.
In terms of how liquidity matches with planned budget execution, in broad terms we see no pressure currently. The USD 4.2bn in cash built up through July already almost covers the USD 5.1bn above-the-line deficit that the government plans to run in Aug-Dec. However, the FinMin plans its local primary auctions on a quarterly basis with the goal of adequately prefinancing its future needs, and for now we haven't noticed any stress to suggest that it could need to rely too heavily on cash buffers instead of raising what it needs in the market.
| Ask the editor | Back to contents |
| CB governor defends decision to hold rate despite depreciation, Fed tightening |
Question:
Why do you think it was necessary to intervene two days in a row? Any reading?
The question was asked in relation to the following story: CB governor insists Banxico doesn't have to follow the Fed
Answer:
It's common for Governor Victoria Rodríguez to discuss the monetary policy scene in the days following a policy rate decision. We don't think consecutive interviews are unheard of; however, we don't recall Governor Rodríguez giving interviews on consecutive days.
The governor was clear in the theme of her interviews, saying the context allows for the CB to hold its policy rate given 1) inflation is performing as expected, 2) recent currency depreciation has not materially worsened the inflation outlook, and 3) Banxico does not have to follow the Federal Reserve mechanically because of different macroeconomic conditions between Mexico and the US. In other words, the main theme of the interviews was to defend the CB's decision to hold its policy rate at 6.50%, not only last week but at upcoming sittings, in our view.
It's unclear to us why Governor Rodríguez decided to assure the market that the CB is not pondering any rate adjustments at the time. Perhaps the interviews are trying to offset the latest meeting's minutes, to be published on October 8, where one or two board members may ponder the need for a rate hike if currency depreciation or expectations about the Fed's path deteriorate much; however, this is only speculation. We note that local media speculated a board member could diverge from the rest of the board in the latest meeting, voting to raise the policy rate by 25 bps; while this did not happen, one hawkish board member may have pondered a hike, something that the market will surely notice in the minutes. Building on this speculation and considering Deputy Governor Jonathan Heath is the only board member that may promote a rate hike in the short term, Governor Rodríguez's media presence might be trying to preemptively show Heath in the minority, considering he is known to be more outspoken than other deputy governors, and his outspokenness could create the false perception that his position is shared by the board.
| Ask the editor | Back to contents |
| CB governor now focuses on core inflation, minimizes currency depreciation |
Question:
What do you read from her "change of discourse"?
Separately, at what point will the MXN depreciation force them into tightening policy? What would that look like?
The question was asked in relation to the following story: CB's Governor sees no inflationary pressure from MXN or growth
Answer:
CB Governor Victoria Rodríguez minimized a recent acceleration of general inflation, highlighting that the CB should focus on core inflation. While we agree with this stance, we warn this wasn't her position early in the year, when she backed further monetary easing despite no clear evidence that core inflation was decelerating, in our view.
We note that the governor stood among the board members backing the last Monetary Policy Rate (MPR) cut of the cycle, in May, adding to easing of 375bps since the cycle began in March 2024. While most of this cycle could not be criticized, the last few cuts brought the MPR into neutral territory despite lingering services inflation, something objected to by some analysts and CB Deputy Governor Jonathan Heath. Still, Governor Rodríguez minimized lingering core inflation by 1) focusing on non-core dynamism and 2) saying the upward pressure was limited to a few items and probably transitory. In summary, our take is that the governor did not mind core inflation remaining above 4.00% for 13 months at the time of the last rate cut but now minimizes non-core pressure by noting core inflation is slowing.
The second question is harder to answer. We minimize concerns regarding recent currency depreciation, recalling it's not enough to offset early 2026 appreciation. However, even a depreciation vs 2025-end levels would not be a significant inflationary risk, in our view. The CB's board has noted the currency has had only a modest inflationary impact in recent years; we agree, seeing pressure on a number of tradable goods rather than on general inflation.
A study by Banxico suggests a 1% depreciation contributes to a 0.02-0.04pps increase in overall inflation over the next 12 months. Such modest pressure could still have political implications and hurt consumer confidence, without pushing general CPI inflation too far up. These implications might be enough for the CB to raise an eyebrow even if CPI inflation is not being pressured above its tolerance band. However, we note the government may be able to limit some of these pressures by subsidizing fuel prices.
We do not expect the CB to show any concern if the currency depreciates a few percentage points from 2025-end, meaning the CB might be comfortable with the exchange rate moving to around USD/MXN 18.60. We insist a modest depreciation might even be welcome, considering the appreciation's impact on real wages is not enough to offset the negative impact on the exporting sector's competitiveness and on public revenues. Having said this, we believe the CB might not be so comfortable if further depreciation is fully linked to the divergence between the local monetary policy and the Federal Reserve, considering this wouldn't represent a short-term shock and risks unintended financial flows.
| Ask the editor | Back to contents |
| T-bills pledged as collateral (time series) |
Question:
Please could you explain the collateralscomment? Presumably these T-bills have been pledged against foreign borrowing, but what type of borrowing, and by whom? Has Egypt done large-scale TRS operations? And has there been a significant change or increase in the value pledged?
The question was asked in relation to the following story: Stock of T-bills held by foreigners jumps 18.5% m/m to USD 56.7bn at end-Jun
Answer:
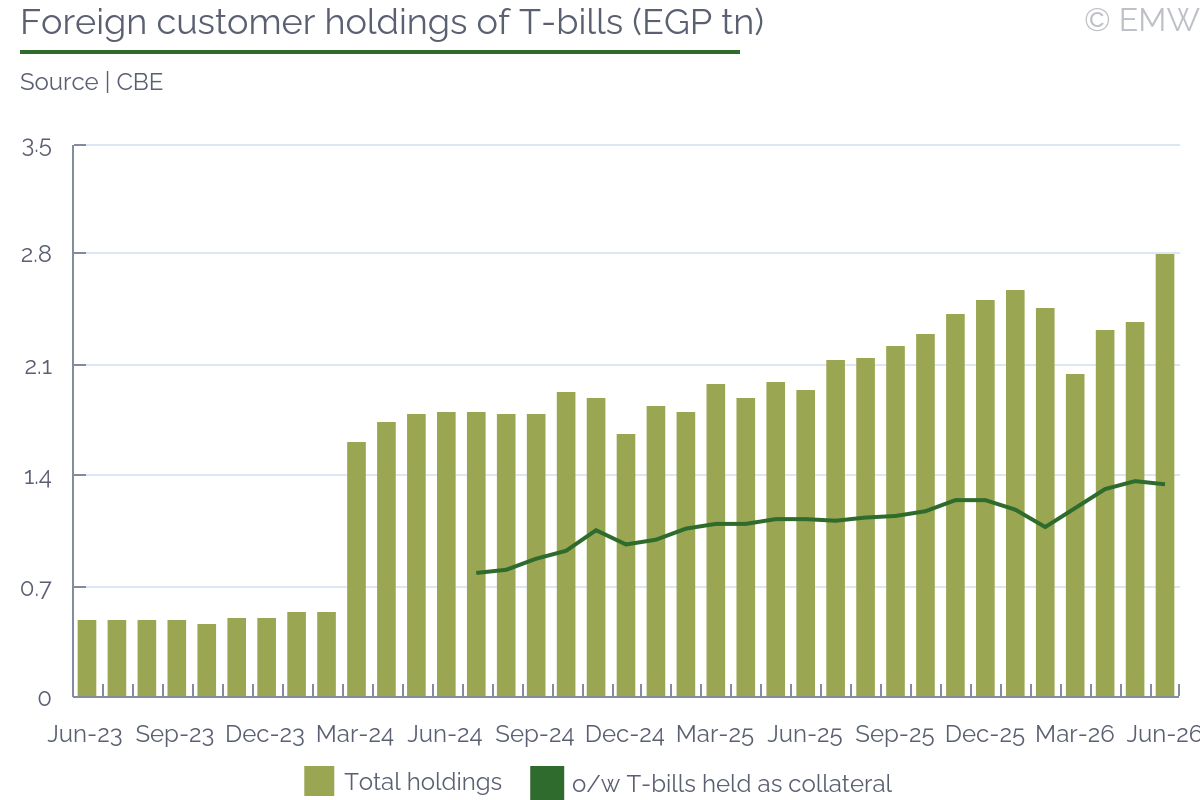
There is limited official information on these transactions. We get the figures from a footnote in CBE's monthly economic reports; here is what the latest report states:
[Foreign customers' holdings of T-bills of EGP 2.71tn] Include collaterals (Contingent Liabilities) under external financing operations, which reached EGP 1.35tn at the end of June 2026.
It is our understanding that local banks are using local-currency T-bills as collateral to borrow USD from foreign banks. Under this interpretation, the beneficial ownership of the T-bills should not change and should stay with the Egyptian bank rather than transferring to the foreign entity.
The CBE first mentioned the T-bills used as collaterals in its Aug 2024 report, when their outstanding value was given at EGP 785bn. Their stock has increased steadily to EGP 1.35tn as of June 2026. We think these transactions are linked to the March 2024 FX reform, which unlocked substantial external financing from bilateral and multilateral partners. Consequently, portfolio investors rushed in to buy high-yielding local currency T-bills. We haven't seen official information about the "foreign customers", but we think these are likely to include Gulf financial institutions, as well as European and US banks.
| Ask the editor | Back to contents |
| M2 growth and CPI inflation |
Question:
My understanding is that M2 growth is relatively low by historical standards. Do you still judge these levels as inflationary?
The question was asked in relation to the following story: Development partners join Egypt USD 520mn infrastructure finance guarantee fund
Answer:
M2 growth has indeed slowed recently, averaging 18.0% y/y during May-Jul, compared to an average of 24.7% y/y in 2025 and an average of 23.7% y/y over the past three years. I think this is still high and should have some inflationary impact, but probably not as much as I initially thought. The CBE also seems to think that the impact of high M2 growth on CPI inflation has diminished over time, and concludes its stance is sufficiently tight at the moment, according to the latest quarterly MPC report.
There is an interesting analysis of the real interest rate vs the neutral rate (Box 3). The CBE estimates that the real policy rate remains above the Neutral Real Interest Rate (assumed to be between 3% and 4%), resulting in a positive real interest rate gap and signaling a restrictive monetary policy stance. According to the CBE, this positive gap will continue to support the disinflation process over the forecast horizon and convergence of inflation toward its target over the near term.
| Ask the editor | Back to contents |
| Fiscal pressures, FX stability and the Moody's outlook for Angola |
Question:
HI on Angola: Moody's moved Angola to positive last week, citing FX stability, lower inflation and a falling debt ratio. How much of that improvement comes from the peg itself? The kwanza has held at 912 for two years with a 20-30% gpa in parallel FX markets. The H1 deficit looked much worse than the budget was 2.9% of GDP in six months against a 2.8% full-year target. what drove this? are they spending a lot on fuel subsidies? or is it due to lower oil production? October and November loading programmes are around 900 and 850 kb/d. Reserves excluding gold are lower than in January 2025, despite the oil windfall. Are they funding the fuel subsidy off balance sheet via Sonangol? i see that they've already which borrowed over $5bn in the first half and is owed over $4bn by the state. With no pump-price adjustment expected before the August 2027 election, is the fiscal position deteriorating behind a stable exchange rate? And how large an adjustment should we expect after the vote?
Answer:
I think there is a genuine tension between Moody's positive-outlook rationale and the underlying fiscal and FX dynamics, although I would not characterise the current situation simply as "fiscal deterioration behind a stable exchange rate".
FX stability is an important part of the improvement in Angola's debt metrics, but I would not describe the current regime as a hard peg. The kwanza has been broadly stable around AOA 912/USD since late 2024, and Moody's explicitly says this has helped reduce the debt ratio by limiting the local-currency increase in the value of the roughly 80% of government debt denominated in FX. It is therefore a meaningful mechanical contributor to the improvement in debt/GDP. Moody's also notes that FX conditions have remained orderly, with reserves broadly maintained around USD 15bn. It is worth noting, however, that the BNA has not recently been intervening to support the currency. Stable external financing access, relatively stable FX oil inflows and the government's debt-management strategy have been the main factors underpinning FX stability. The latter includes greater reliance on local-currency issuance and active debt-management operations to reduce short-term repayment pressures. Overall, I would expect a sharp fall in oil prices to change this dynamic and renew depreciation pressure on the kwanza.
The H1 fiscal deterioration looks more like an expenditure problem than an oil-revenue problem. Revenue execution has been relatively smooth, including on the non-oil side, while spending remains elevated, particularly on goods and services. This is important because it suggests that the H1 deficit was not primarily driven by weaker oil production or a shortfall in oil revenue.
Fuel subsidies are part of the budget, but the important distinction is how they are financed. I would not describe them as "off balance sheet". The subsidy is a budget expenditure and therefore worsens the fiscal balance. However, the government does not necessarily settle the subsidy obligation to Sonangol in cash immediately. The mechanism is essentially a netting arrangement. Sonangol owes the government oil-related taxes, while the government owes Sonangol compensation for selling fuel below cost. Rather than the government collecting the tax from Sonangol in cash and then paying the subsidy back, the two claims can be netted. This means the subsidy is recorded as expenditure, but the immediate cash-financing requirement is reduced because the government accumulates a payable to Sonangol. This is why Sonangol's borrowing matters. The company can effectively end up financing part of the government's subsidy obligation through its own balance sheet. The IMF describes the resulting government obligation as an account payable to Sonangol and notes that accumulation of this payable contributes to Sonangol's debt. Sonangol's debt is now part of the broader public-sector debt perimeter. I would therefore describe this as quasi-fiscal financing through Sonangol, rather than an off-budget subsidy. The subsidy remains in the fiscal accounts, but part of its cash financing is effectively shifted from the central government to the state company. I would nevertheless be cautious about linking all of Sonangol's recent borrowing directly to fuel subsidies. Some of the borrowing is clearly related to financing oil-sector investment and other corporate needs.
The reserves story is therefore important. Gross reserves have not increased in line with the oil-price windfall and remain slightly below their January 2025 level. This suggests that stronger oil inflows are being absorbed by a combination of fiscal financing needs, debt-service requirements and FX-market management rather than accumulating entirely as external buffers. This is the part of the story that I think is worth watching most closely. The official exchange rate is stable, but if fiscal deficits remain elevated, government payables to Sonangol rise and reserves gradually decline, some of the adjustment is effectively being deferred rather than eliminated.
On the 2027 election and fuel prices, I would avoid putting a precise post-election adjustment into the base case. There is no clear official schedule that would allow us to quantify the size of a pump-price adjustment after the August 2027 election. The 2027 election will nevertheless be an important factor for the rating outlook because the policy direction after the election will determine how quickly fiscal consolidation and subsidy reform proceed. A continuation of the current policy framework would provide greater continuity, while a change in government could bring different spending priorities, particularly given opposition parties' emphasis on living standards and greater investment in areas such as health and education. The key issue for the sovereign profile would ultimately be how any change in policy translates into the fiscal deficit, public-sector borrowing requirements and the pace of subsidy reform.
Overall, I would say the debt improvement is real, and FX stability has made a material mechanical contribution by containing the local-currency value of FX debt. But the H1 numbers show that fiscal adjustment is not yet complete. Fuel subsidies are a meaningful expenditure item, while their cash financing can be intermediated through Sonangol, creating government payables and potentially shifting liquidity pressure onto the SOE. The combination of stable FX, weaker reserve accumulation and rising quasi-fiscal exposure is therefore worth monitoring closely ahead of 2027.
The question was asked in relation to the following story: Main Themes
| Ask the editor | Back to contents |
| 2027 election polls |
Question:
Are there any reliable polls for the presidential election in January?
The question was asked in relation to the following story: Main Themes
Answer:
There are a few polls covering the 2027 election but the polling base is still relatively limited and the results vary depending on methodology and fieldwork dates. The most recent is SBM Intelligence's Sep 2026 Voter Sentiment Tracker which interviewed 1,103 respondents in 12 states and the FCT. It found the NDC at 42.2% of stated preference and the ruling APC at 25.5%. SBM did caution that the survey is a snapshot of voter sentiment and shouldn't be looked at as a forecast of the election result. SBM's May survey had put the NDC at 57.4% and the APC at 11% so the Sep results suggest a significantly narrower gap over the four-month period.
There's also an aggregation of surveys compiled by NigeriaPolls. The July 2026 aggregation covers four sources: NigeriaPolls, NOI Polls, SBM Intelligence and Afrobarometer. The individual samples were 2,400, 1,800, 1,500 and 2,100 respectively. The reported voter-intention figures showed Tinubu at 34.3% in the weighted aggregate, Obi 26.5%, Atiku 21.8% and Kwankwaso 8.5% (and around 9% undecided). NigeriaPolls says it weights the polls by sample size and recency so this may be a useful way of comparing several sources.
NigeriaPolls conducted its own 3,102-person survey earlier in June across all 36 states and the FCT. Like SBM, it described the survey as an early reading of voter sentiment rather than an election forecast. The results showed APC at 34%, PDP at 28%, Labour Party at 18% and NNPP at 6%. In terms of assessing the available data, NOI Polls, SBM Intelligence and Afrobarometer have longer-established polling operations while NigeriaPolls is a newer platform. Overall, the available data gives a useful sense of the current mood but issues like turnout and late changes in voter preferences remain unpredictable.
| Ask the editor | Back to contents |
| Loan-to-deposit ratio excluding SAL funds |
Question:
On your side, do you keep track of underlying LDR excluding SAL figures? Also, do you have any view or expectations of how SAL may increase or decline through the financial year?
Answer:
We don't usually keep data on the LDR excluding SAL, as there is no reliable monthly data on the SAL figures or their placement in commercial banks - they could be approximated based on anecdotal evidence and parliamentary approval for SAL funds disbursement. There is one good proxy for SAL funds placement in commercial banks, which could be found in the central bank's data on deposits in commercial banks here:
https://www.bi.go.id/SEKI/tabel/TABEL1_17.xls
If you look at the last sheet (1.17_2), you can see under memo items the central government's deposits in commercial banks. The row "Time deposits" includes the SAL funds alongside other government deposits, as the SAL funds are placed in six-month deposits that could be withdrawn at any time. If you look at the column Sep 2025, you can see the first IDR 200tn deposit of SAL funds in state-owned commercial banks. After that, judging from past data, if we assume that government time deposits in commercial banks are more or less constant at IDR 200-230tn, any excess amount on top is a rough approximation of the SAL funds placed in the commercial banks.
I'm attaching a table with the relevant data for your convenience. You can find the loan data at the following link, under Table I.4:
https://www.bi.go.id/id/statistik/ekonomi-keuangan/seki/Default.aspx#headingOne
One downside is that loan and deposit data are lagged by two months, with the latest available breakdown for July. Bank Indonesia releases only a statement on the loan and deposit growth in August with the MPC decision at the following link, while the full breakdown will be released in October.
https://www.bi.go.id/id/publikasi/ruang-media/news-release/Pages/sp_2819326.aspx
As for the overall SAL balance, the only available accurate data is published annually with the Audited Financial Statements, with the latest one being here:
https://www.bpk.go.id/assets/files/lkpp/2025/lkpp_2025_1784028222.pdf
If you look at p. 34, it shows SAL funds stood at IDR 438.3tn at end-2025. The government usually keeps these funds with the central bank, but decided to deposit IDR 200tn in commercial banks first in Sep 2025. Since then, the amount has grown to about IDR 280tn, with another IDR 100tn on standby, according to statements from the finance minister. Those funds will be reduced to about IDR 200tn by July 2027, with some local analysts speculating this could happen by Dec 2026.
The question was asked in relation to the following story: Govt to keep SAL funds in commercial banks until Jul 2027
| Ask the editor | Back to contents |