 |
|
| Middle East and Africa Morning Review | Oct 1, 2026 |
|
| This e-mail is intended for Sample Report only. Note that systematic forwarding breaches subscription licence compliance obligations. Open in browser | Edit Countries on Top |
|
| Large EMs |
|
| Egypt |
|
|
|
|
| United Arab Emirates |
|
|
| Nigeria |
|
|
|
| Middle East & N. Africa |
|
| Israel |
|
|
|
| Jordan |
|
|
|
| Morocco |
|
|
|
| Oman |
|
|
|
| Saudi Arabia |
|
|
|
|
|
|
| Tunisia |
|
|
|
|
| Sub-Saharan Africa |
|
| Angola |
|
|
| Ethiopia |
|
|
| Ghana |
|
|
|
|
|
| Kenya |
|
|
|
|
|
|
| Mozambique |
|
|
|
|
|
| Senegal |
|
|
|
|
| South Africa |
|
|
|
|
|
|
| Uganda |
|
|
|
|
| Zambia |
|
|
|
|
|
|
| Egypt |
|
| Foreign funds buy USD 0.7bn worth of bonds/T-bills on EGX in September (net) |
|
| Egypt | Oct 01, 08:05 |
|
- Non-Arab funds were net sellers in September, but Arab funds stepped in
- Pound depreciates by 3.4% m/m in September due to regional uncertainty, high energy prices
- Foreign investors held USD 57bn worth of T-bills as of end-June, but this includes USD 28bn pledged as collateral
Foreign institutional investors bought EGP 503bn worth of T-bills and bonds through the local exchange (EGX) in September and sold EGP 467bn worth of the debt instruments, recording a net acquisition of EGP 37bn (USD 700mn), according to data from the local bourse. The non-Arab institutional investors, who we believe are more sensitive to global and regional volatility, recorded a net outflow of USD 830mn in the month. The regional security situation deteriorated in September, after a drone attack damaged a key Saudi pipeline, which sent oil prices into triple digits, while US-Iran talks collapsed again. Foreign Arab funds were net buyers, with a net inflow of USD 1.5bn. Following the spike in energy prices and regional tensions, the pound depreciated by a strong 3.4% m/m in September. 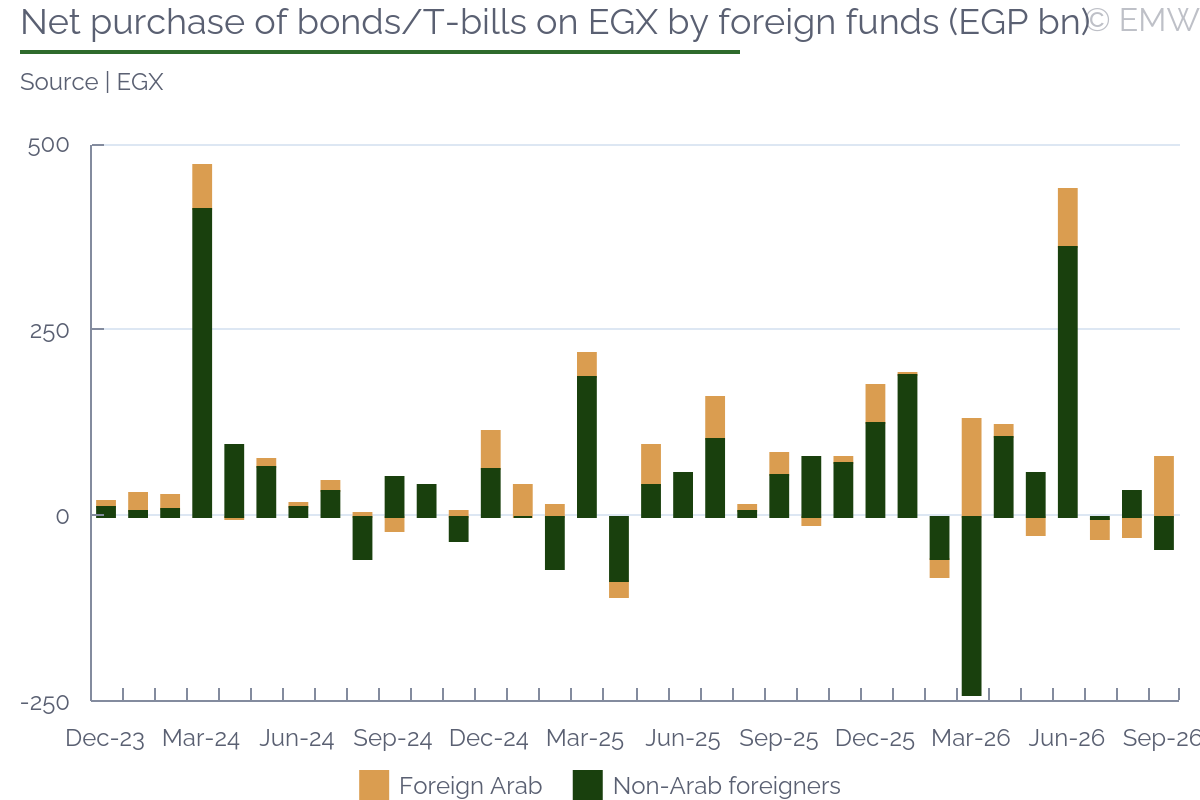 It should be noted that the EGX does not provide a breakdown by instrument type - bonds vs T-bills - but we believe that foreign demand is geared heavily towards the short-term notes. Foreign investors held USD 57bn worth of T-bills as of end-June, accounting for 42% of the outstanding stock and for 103% of CBE's official FX reserves. However, the CBE said that these foreign holdings include T-bills pledged by local banks as collateral worth USD 28bn, so the actual foreign holdings should be around USD 29bn. | Trading of T-bills/bonds by institutional investors on EGX (EGP bn) | | Jun-26 | Jul-26 | Aug-26 | Sep-26 | | Buy | 2,415 | 2,108 | 2,026 | 2,079 | | Egyptians | 1,616 | 1,590 | 1,510 | 1,576 | | Arabs | 218 | 157 | 166 | 228 | | Foreign non-Arab | 581 | 362 | 350 | 276 | | | Sell | 2,425 | 2,117 | 2,032 | 2,086 | | Egyptians | 2,063 | 1,567 | 1,520 | 1,619 | | Arabs | 142 | 182 | 195 | 148 | | Foreign non-Arab | 219 | 367 | 316 | 319 |
| | Source: EGX |
|
|
|
|
|
| Egypt | Oct 01, 06:49 |
|
Egypt's Eqat completes studies for USD 320mn extraction plant in Eastern Desert (Ahram) Egypt IMPA signs EGP 103bn debt settlement agreement with National Investment Bank (Ahram) Egypt steps up reforms to boost competitiveness, attract investment: Minister to Fitch (Ahram) Cabinet prepares for October transparency conference, orders boost to strategic reserves (Zawya) Six years after a mining reboot, Egypt's gold ambitions start to take shape (Zawya) Egypt adds 45 MMcf/d of natural gas from 4 wells (Amwal Al Ghad) Egypt Presses Economic Reforms to Boost Competitiveness, Attract Global Investment (Sada Elbalad) EU Targets EUR 5bn Investment for Egypt by 2027 (Sada Elbalad) Egypt, China explore expanded cooperation in pharmaceutical manufacturing, vaccines (Daily News Egypt) SCZONE steps up push to attract US investment (Daily News Egypt) |
|
|
|
| | Stock of T-bills held by foreigners jumps 18.5% m/m to USD 56.7bn at end-Jun |
|
| Egypt | Oct 01, 06:02 |
|
- Foreign holdings include collaterals worth USD 27.5bn, CBE says in a footnote
- Capital flight triggered by Iran war was relatively muted, and foreign investors returned in April
- Pound depreciated sharply in March, but has regained some of its strength since then on portfolio and remittance inflows
The stock of T-bills held by foreign investors rose by a strong 18.5% m/m to a record EGP 2.79tn (USD 56.7bn) as of end-June, following a milder increase of 2.3% m/m in May, according to figures published by the central bank (CBE). This is the stock of local currency notes only, so the m/m changes do not reflect FX rate effects. The increase in foreign holdings reflects the surge of portfolio inflows due to the cease-fire in the Middle East and the breakthrough in US-Iran talks earlier this year. In fact, the EGX secondary market recorded the second strongest net purchase of T-bills/bonds since the major FX reform. The CBE noted that the foreign holdings include collaterals (contingent liabilities) worth USD 27.5bn at end-month under external financing operations. Excluding the contingent liabilities, the stock of T-bills held by foreign investors (USD 29.2bn) accounts for 53% of CBE's net international reserves as of end-June. Meanwhile, the T-bill holdings of foreign banks (branches) - another set of data we have been monitoring - fell by 12.0% m/m to EGP 76bn following a 17.3% m/m increase recorded in the preceding month. 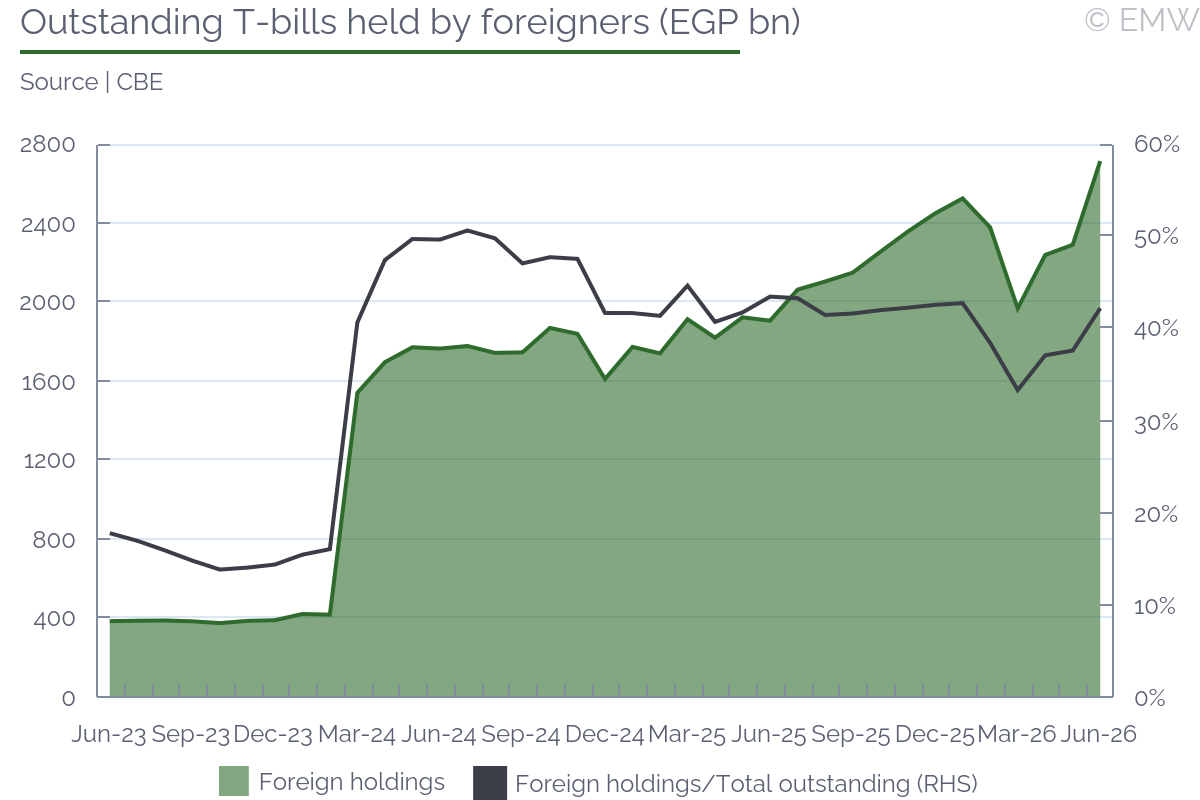 Egypt has recorded massive capital inflows since March 2024, and a large chunk of these inflows were portfolio investments into T-bills. Not surprisingly, the Iran war triggered capital flight, but EGX figures and FX reserve data showed that capital outflows were relatively muted. The FX market was liquid enough to accommodate an orderly and calm exit and there were a few waves of portfolio investors rushing back in to buy T-bills. Portfolio investments recorded a massive USD 8.9bn net inflow in June - the second highest on record - which helped the pound regain some of the strength it lost in March. | EGX: Net purchases by foreign investors (EGP mn) | | | Mar-Aug | Week ended Sep 3rd | Week ended Sep10th | Week ended Sep 17th | Week ended Sep 24th | | USD/EGP official (average) | 51.72 | 50.98 | 51.06 | 51.92 | 51.75 | | EGX statistics - net purchase by foreigner investors | | | | | | | Net purchase of equity (EGP mn) | -26,031.0 | -347 | 3,540.1 | 795.4 | -1,387.8 | | Foreign Arab funds | -14,895.0 | -303.8 | 4,590.9 | -432.6 | -394.6 | | Foreign non-Arab funds | -11,136.0 | -43.1 | -1,050.8 | 1,228.0 | -993 | | Net purchase of bonds/T-bills (EGP mn) | 456,096.0 | -18,834.3 | 21,361.8 | -27,733.1 | 74,894.0 | | Foreign Arab funds | 140,938.0 | -6,955.9 | 18,053.7 | 18,018.3 | 19,917.9 | | Foreign non-Arab funds | 315,158.0 | -11,878.4 | 3,308.1 | -45,751.4 | 54,976.1 | | Total net purchases (equity + debt) | 430,065.0 | -19,181.2 | 24,901.9 | -26,937.7 | 73,506.2 | | Total net purchases (equity + debt), USD mn | 8,315.3 | -376 | 487.7 | -518.8 | 1,420.5 |
| | Source: EGX |
|
|
|
|
| United Arab Emirates |
|
| Etihad Rail launches network linking Abu Dhabi, Dubai and Fujairah |
|
| United Arab Emirates | Oct 01, 09:39 |
|
- New services strengthen the UAE's inter-emirate rail network
- Rail travel connects with Dubai Metro and public transport
Etihad Rail has launched passenger services linking Abu Dhabi, Dubai and Fujairah, expanding the UAE's national railway network and creating a new inter-emirate transport option, according to the Emirates News Agency (WAM). The service began operations on Sep 30, with Dubai's Al Yalayis Station in Jumeirah Golf Estates joining the existing Abu Dhabi-Fujairah route. The Dubai station is connected to Jumeirah Golf Estates Metro Station by a dedicated pedestrian bridge, allowing passengers to transfer between Etihad Rail and Dubai Metro. The launch follows the start of introductory passenger services between Abu Dhabi and Fujairah on June 30. Etihad Rail said more than 150,000 passengers used that route during its initial operating phase, indicating early demand for inter-emirate rail travel. Meanwhile, the Dubai-Abu Dhabi journey takes about 64 minutes, while the direct Dubai-Fujairah service takes roughly 70 minutes. Etihad Rail is operating 10 daily services between Dubai and Abu Dhabi, alongside six daily services between Abu Dhabi and Fujairah. The passenger fleet comprises 13 trains, each capable of carrying up to 400 passengers at speeds of up to 200 kilometres per hour. The network is designed to integrate with existing public transport rather than operate as a standalone system. Etihad Rail is continuing to expand the passenger network. Stations in Liwa and Madinat Zayed are scheduled to open on November 30, followed by additional stations in the Al Dhafra region on December 30. Sharjah is scheduled to join the network on March 30, 2027. The expansion gives the UAE a national passenger rail backbone connecting major population centres, business hubs and tourism destinations. It also builds on Etihad Rail's existing freight network, which has been operating nationally since 2023. Consequently, the passenger project is moving the railway beyond freight transport and toward a broader role in the UAE's domestic mobility system. By connecting rail with Metro, buses and other modes, the network is intended to make inter-emirate travel less dependent on road transport while supporting wider economic and urban integration. Established in 2009 by federal decree, Etihad Rail is the UAE's national rail operator. It builds, manages, and operates the country's first-ever national freight and passenger railway network. Additionally, Etihad Rail is spearheading direct cross-border connections. These efforts include a joint venture with Oman Rail to connect Abu Dhabi directly to the Omani port city of Sohar, as well as coordinated link-ups with Saudi Arabia's state railway. Etihad Rail is state-owned. The Government of Abu Dhabi owns 70% via the Abu Dhabi Developmental Holding Company (ADQ), one of the region's largest sovereign wealth funds. The federal government owns the remaining 30%. |
|
|
|
| Nigeria |
|
| Local markets are closed on 01 Oct 2026 due to a public holiday. |
|
| Nigeria | Oct 01, 12:01 |
|
EmergingMarketWatch coverage of Nigeria will be limited on 01 Oct 2026 due to a public holiday. |
|
|
|
| Israel |
|
|
| Israel | Oct 01, 06:41 |
|
If Flydubai Justifies Netanyahu's Warning, Why Wasn't More Done to Prevent It? (Haaretz) Stoking West Bank Tensions, Netanyahu Seeks to Manufacture an Election Emergency (Haaretz) How Israel's Security Chiefs Are Serving Netanyahu's Interests for the Election (Haaretz) Israel to join UAE in flydubai probe, Netanyahu says; [President] Herzog condemns settler violence (Jerusalem Post) Israel's next government left with war bill (Jerusalem Post) Will El Al and IsrAir continue to soar? Waiting for the opening of trading in Tel Aviv (Calcalist) "The entry of food chains into the electrical goods industry is intended to obscure the rise in food prices" (Calcalist) "If the budget is just a recommendation, we still have a lot of room to deteriorate" (Calcalist) Israel temporarily suspends FlyDubai flights to Israel; Arkia prepares to resume flights to the Emirates (Calcalist) The business sector faces an earthquake due to Jewish terrorism in the West Bank - and is silent (TheMarker) Netanyahu: It's too early to determine whether Iran was involved in the attempted attack on the flight (TheMarker) [Shin Bet chief] Zini's warning that preceded the attempted attack (Globes) Goods around the world have already become more expensive, in Israel it will happen after the holidays (Globes) The crisis between Netanyahu and Erdogan escalates (Globes) |
|
|
|
| Treasury plans to raise NIS 11.2bn from local market in October |
|
| Israel | Sep 30, 16:30 |
|
- Borrowing plan is similar to targets in Jan-Jul
- Treasury to hold four auctions in October
The treasury plans to sell tradable bonds worth NIS 11.2bn on the local market in four equal auctions in October, according to the borrowing plan for the month published on Wednesday evening. The amount is twice as high as the plans in the previous months but broadly in line with the borrowing targets in Jan-Jul. The borrowing would be much higher than in October 2025 but this is due to the timing of the Jewish holidays, which were mostly in October last year. In October, the authority intends to raise NIS 6.5bn by selling fixed-rate bonds and they will comprise the bulk of the fundraising, as usual, NIS 3.8bn through CPI-linked bonds and NIS 900mn through floating rate bonds. It does not plan to sell T-bills in October with the last such auction held in September 2025. According to the 2026 budget plan, the government intends to raise NIS 224.06bn by selling tradable bonds on the local market this year and has targeted raising NIS 108.4bn in Jan-Oct. The treasury has raised a total of NIS 112.4bn to-date, lower than the NIS 116.2bn offered, as it failed to meet its plans in the non-competitive auctions held on Tuesdays. |
|
|
|
| Jordan |
|
| Energy ministry raises fuel prices for October |
|
| Jordan | Oct 01, 08:54 |
|
- 90-octane gasoline rises 5.0% m/m, diesel 5.9% and 95-octane gasoline 3.8%, ending their three-month freeze
- However, kerosene and household LPG prices remain unchanged
- Treasury-borne fuel subsidies and price differentials reach JOD255mn through end-September
Jordan's Fuel Pricing Committee partially raised domestic fuel prices for October after a marked increase in crude oil and refined-product prices during September, according to the energy ministry. The decision ends three consecutive months in which the government kept the prices of main petroleum products unchanged despite higher global energy costs. The price of 90-octane gasoline rose by 5.0% m/m to JOD 1.05 per litre from JOD 1.00, 95-octane gasoline increased by 3.8% to JOD 1.360 from JOD 1.310 and diesel rose by 5.9% to JOD 0.900 from JOD 0.850. Kerosene remained at JOD0.550 per litre, while the price of a 12.5kg household LPG cylinder was kept at JOD 7. The partial adjustment indicates that the government continues to absorb part of the higher import cost rather than fully passing it on to households and businesses. The Ministry said that, without subsidies and price differentials, the October cost would have been JOD 1.077 per litre for diesel and JOD 1.044 for kerosene. Cumulative subsidies and price differentials borne by the Treasury reached around JOD255mn through end-September, up 13.8% from JOD224mn at end-August. The government will also provide JOD 1.8mn in support for industrial LPG in October. The decision reflects an effort to balance consumer protection against the growing fiscal cost of shielding the domestic economy from volatile global energy prices. Authorities continue to base domestic fuel prices on the 30-day average of international prices, but the gradual adjustment approach means that retail prices still do not fully reflect international costs. |
|
|
|
| Natural gas falls to 56% of Jordan’s power generation in Jan-Aug 2026 |
|
| Jordan | Sep 30, 16:33 |
|
- Renewables reach 21% of Jordan's electricity generation
Natural gas accounted for 56% of Jordan's electricity generation during the first eight months of 2026, down from 63% in 2025, as renewable energy increased its contribution to the power mix, according to National Electric Power Company (NEPCO) data. Renewables supplied 21% of generated electricity through August, compared with 18% during 2025. The figures point to a gradual diversification of Jordan's power system as solar and wind projects reduce the share of natural gas-fired generation. Oil shale remained an important source, accounting for 16% of generation in the first eight months, down from 17% in 2025. Meanwhile, heavy fuel oil increased its contribution from 1% to 3%, while diesel rose from zero to 1%. Electricity imports from Egypt also increased from 1% to 3%. State-owned NEPCO owns and operates the high-voltage transmission grid, balances and dispatches power across the network, and acts as the sole wholesale buyer of electricity generated by public and private plants. The changing mix has implications for Jordan's exposure to fuel costs. NEPCO said higher international oil and gas prices directly increase electricity-generation costs, with the prices of some natural-gas supplies linked to Brent crude oil under long-term contracts. The company said the resulting gap between generation costs and electricity prices contributes to operating losses and rising debt. The shift toward renewables also strengthens Jordan's energy-security position by reducing reliance on imported fuels. The country has expanded renewable capacity substantially over the past decade, while the government's 2025-2035 energy strategy targets a 40% renewable share of the electricity-generation mix by 2035. The strategy also calls for additional solar and wind projects and greater use of energy-storage technologies. |
|
|
|
| Morocco |
|
| | GDP growth slows to 4.0% y/y in Q2 as industry contracts |
|
| Morocco | Oct 01, 05:38 |
|
- Agriculture surges 21.2% y/y, offsetting a sharp contraction in secondary-sector activity
- Domestic demand remains the main growth engine, rising 5%, led by household consumption and investment
- Net exports remain a drag, although the negative contribution narrows as export growth accelerates
- Q2 mix points to stronger agriculture but weaker underlying non-agricultural momentum in H2, while the wider financing gap adds to external vulnerability
GDP growth slowed to 4.0% y/y in Q2 2026, from 4.6% in Q1 and 5.8% a year earlier, according to HCP's quarterly national accounts. The print was also lower than the flash estimate of 4.8%. The slowdown reflects a sharp weakening in non-agricultural activity, whose growth eased to 1.5% from 4.9% a year earlier, partly offset by a strong agricultural rebound. At current prices, GDP growth slowed to 4.4% from 7.5%, implying a further moderation in the overall price increase to just 0.4% from 1.7%. 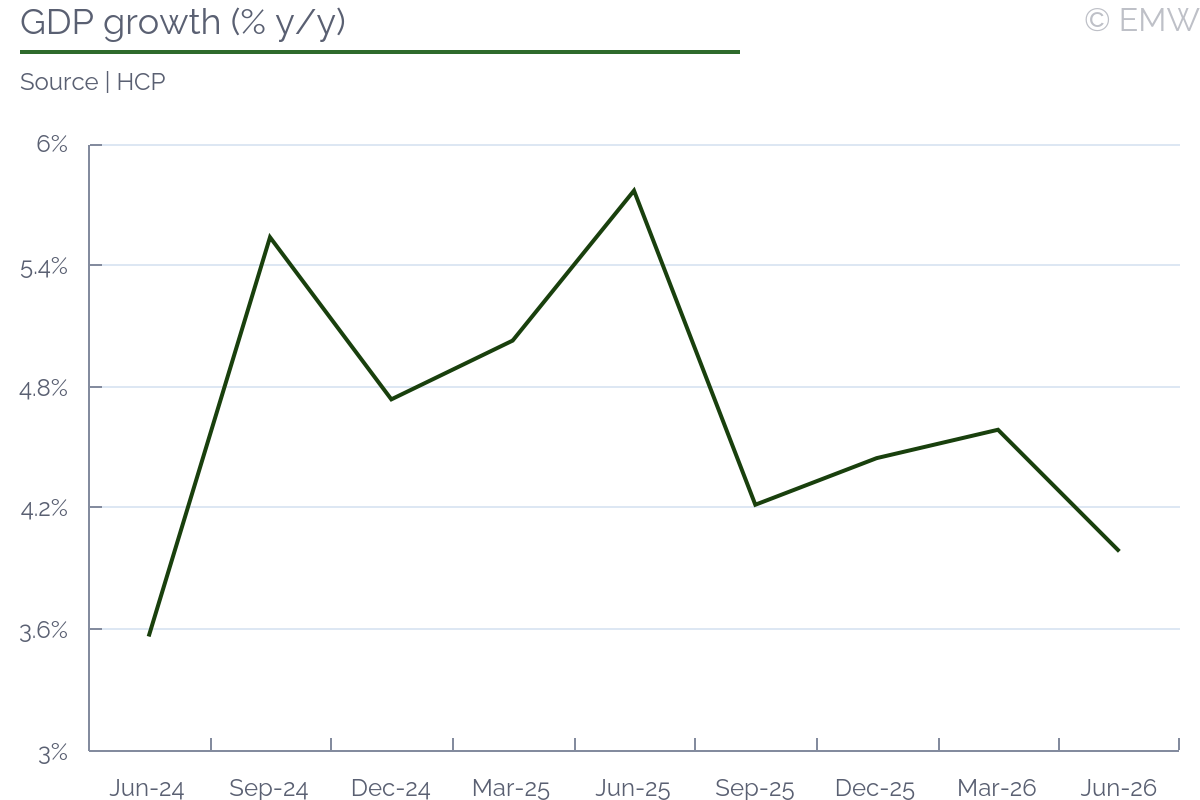 Domestic demand remained the main support to growth, increasing 5.0% y/y and contributing 5.6pps to GDP growth, down from 7.5% growth and a 10.3pps contribution a year earlier. Household consumption accelerated to 4.1% from 1.8%, contributing 2.3pps, while public consumption eased slightly to 4.6% from 4.8%. Investment growth slowed to 6.8% from 20.3%, but still contributed 2.4pps to growth, pointing to continued support from capital spending despite the normalization from last year's exceptionally strong base. The external sector remained a drag, although the negative contribution narrowed compared with a year earlier. Import growth slowed to 9.1% from 12.1%, reducing its negative contribution to 4.7pps from 6pps. At the same time, export growth accelerated to 7.6% from 3.6%, lifting its contribution to 3.1pps from 1.5pps. As a result, the overall contribution of external trade improved to -1.6pps, from -4.5pps a year earlier. The supply side showed a sharp divergence between agriculture and the rest of the economy. Agricultural value added jumped 21.2% y/y, compared with 8.3% a year earlier, while fishing increased 15.9%. In contrast, the secondary sector contracted 3.9%, following 5.8% growth a year earlier, reflecting a 28.6% collapse in extractive industries and a 3.2% decline in manufacturing. Construction growth also slowed to 2.8% from 7.6%, while electricity and water growth eased to 1.9%. Services growth moderated to 4.0% from 4.5%, although financial and insurance services accelerated to 7.7% and education, health and social services remained strong at 6.4%. | GDP real growth, % y/y | | Q2 25 | Q3 25 | Q4 25 | Q1 26 | Q2 26 | | GDP real growth % y/y | 5.8% | 4.2% | 4.4% | 4.6% | 4.0% | | Household | 1.8% | 0.6% | 1.1% | 4.6% | 4.1% | | General government | 4.8% | 5.7% | 6.2% | 4.9% | 4.6% | | Gross fixed capital formation | 20.3% | 16.3% | 10.2% | 10.8% | 6.8% | | Exports | 3.6% | 7.7% | 7.2% | 9.2% | 7.6% | | Imports | 12.1% | 10.9% | 5.9% | 12.7% | 9.1% |
| | Source: HCP |
The financing position deteriorated despite continued domestic demand. Gross national disposable income rose 4.4%, while national saving fell to 30.6% of GDP from 31.1%. Gross investment increased to 35.6% of GDP from 33.5%, widening the economy's financing requirement to 5% of GDP, from 2.4% a year earlier. This points to greater reliance on external financing as investment remains elevated relative to domestic saving. Looking ahead, the Q2 data suggest that agriculture will continue to provide an important cushion in 2026, but the sharp weakening in non-agricultural activity points to softer underlying momentum. Strong household consumption and public investment should continue to support domestic demand, while the improved export performance is helping limit the drag from external trade. However, the contraction in mining and manufacturing, together with the widening financing requirement, highlights risks to the external balance if import-intensive investment and consumption remain strong. The central bank has also revised its 2026 GDP projection downwards to 4.4%, before slowing sharply to 2.9% in 2027. Agricultural value-added is forecast to rebound 16% this year on an estimated cereal harvest of 93mn quintals, while non-agricultural growth is expected to slow to 3.1% from 4.5% in 2025, reflecting weaker-than-expected performance in mining and manufacturing. Non-agricultural growth is then projected to recover to 4% in 2027. The government has based the 2027 budget plan on the forecast of 4.1% GDP growth. Growth is expected to be driven primarily by continued strength in non-agricultural activities, with their value added projected to increase 4.3%, while agricultural GVA is forecast to rise 1.2%, assuming cereal production of 70mn quintals. |
|
|
|
| AfDB provides EUR 270mn airport expansion loan |
|
| Morocco | Oct 01, 05:16 |
|
- Programme targets major airports in Marrakech, Agadir, Fez and Tangier
- It will strengthen Morocco's role as an aviation hub between Africa and Europe
The African Development Bank (AfDB) signed a EUR 270mn financing agreement with Morocco's National Airports Office (ONDA) to expand and modernise airport infrastructure under the Airport Infrastructure Expansion and Modernisation Programme (PEMIA). The programme targets major airports in Marrakech, Agadir, Fez and Tangier, with upgrades to terminals, air navigation, security, baggage handling and digital passenger services. Airport capacity is expected to reach 14mn passengers in Marrakech, 5mn in Agadir, 3.6mn in Tangier and 3mn in Fez by 2030. The investment supports Tourism Vision 2030 and Morocco's preparations for major international events like co-hosting 2030 World Cup, while strengthening its role as an aviation hub between Africa and Europe. Higher airport capacity should support tourism, trade and logistics growth, with several thousand jobs expected to be created and scope for additional private investment. The project adds to Morocco's infrastructure investment pipeline ahead of 2030, complementing rail and urban transport projects and supporting tourism receipts and external services exports. Rising passenger traffic will increase pressure to deliver airport capacity on schedule, while stronger connectivity should help Morocco capture additional tourism and logistics demand over the medium term. |
|
|
|
| Oman |
|
| | GDP growth accelerates to 5.1% y/y in Q2 |
|
| Oman | Oct 01, 12:46 |
|
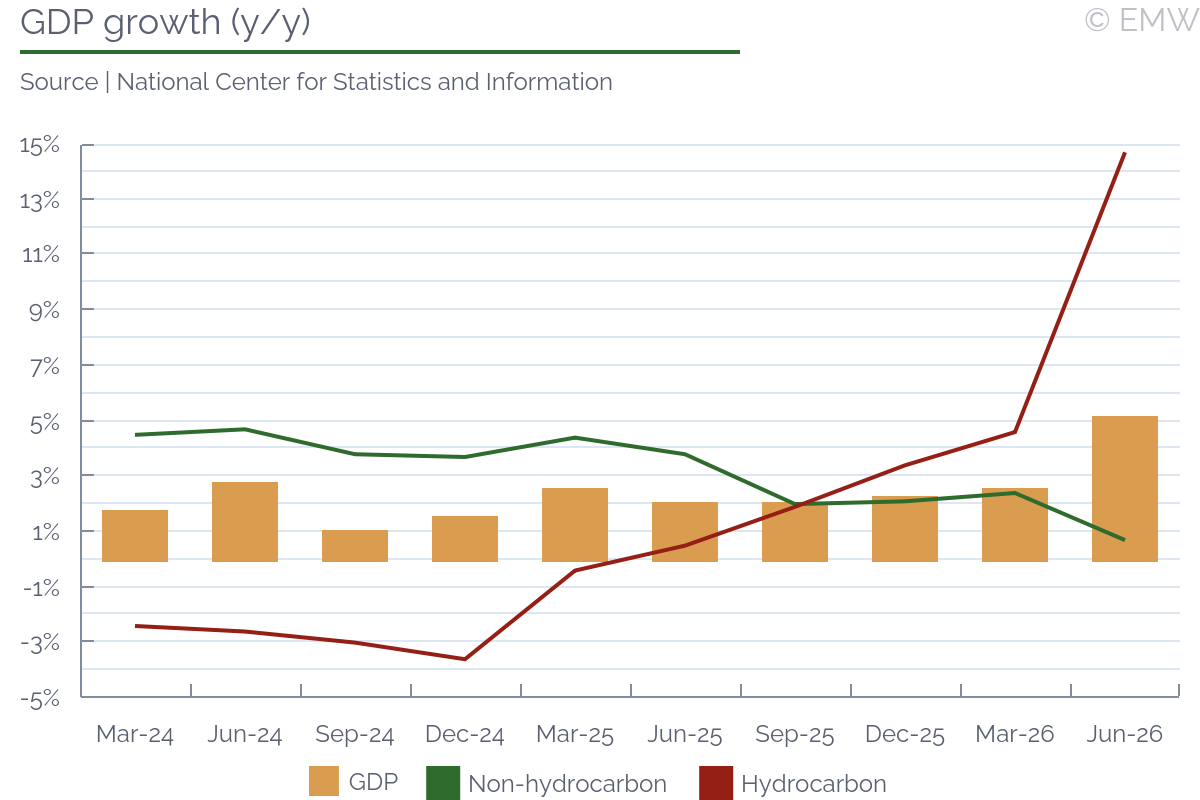
- Growth of hydrocarbon economy accelerates to 14.7% y/y
- Non-hydrocarbon economic growth slows to 0.7% y/y
- Non-hydrocarbon sector accounts for 70% of total GDP
Oman's GDP grew 5.1% y/y during the second quarter of 2026, according to data from the National Centre for Statistics & Information (NCSI). That was an acceleration from growth of 2.6% y/y during the first quarter of 2026. The overall economic acceleration during the second quarter came as growth in the hydrocarbon sector surged, while the non-hydrocarbon sector experienced a slowdown. The hydrocarbon sector increased 14.7% y/y during the second quarter, an acceleration from the growth of 4.6% y/y during the first quarter of 2026. The robust expansion was driven by the crude oil sector, which increased 15.2% y/y, while the natural gas sector rose 11.7% y/y. Oman is not a member of OPEC, but is a member of the OPEC+ alliance. Meanwhile, the non-hydrocarbon sector posted moderate growth of 0.7% y/y, down from the growth of 2.4% y/y during the first quarter of 2026. A breakdown shows that the sector of financial and insurance activities jumped 8.1% y/y. Similarly, the sector of wholesale & retail trade increased 2.9% y/y, and the telecommunications sector rose 1.4% y/y. Likewise, the manufacturing sector increased 0.5% y/y in Q2, showing early signs of stabilizing despite the fact that the construction sector dropped by 4.6% y/y. This mixed performance supports indications of a cooling real estate market alongside sticky raw material input costs. Having spent the last few years completing massive infrastructure overhauls - including ports, special economic zones like Duqm, and major highways - Oman is navigating a transitional lull before new project cycles pick up the slack. Additionally, manufacturing and construction remain highly interdependent. The 4.6% y/y drop in construction directly lowered domestic demand for manufactured building materials such as cement, structural steel, and cables. Moreover, since Oman imports a large portion of its industrial raw components, shipping disruptions and input cost volatility following the start of the Iran war on Feb 28 meant Omani factories faced tighter margins throughout the first half of the year. Finally, the sector of public administration and defence decreased 1.6% y/y during the second quarter. During the second quarter, the non-hydrocarbon sector accounted for exactly 70% of total real GDP. Looking forward, the IMF expects Oman's economy to expand 3.7% in 2026. Click here for our comprehensive database of macro forecasts. |
|
|
|
| | Trade surplus jumped 53% y/y to USD 14.2bn in Jan-July |
|
| Oman | Sep 30, 21:20 |
|
- Exports rise 18% y/y to USD 41.2bn as imports increase 5% y/y to USD 27.1bn
- UAE is Oman's main trading partner
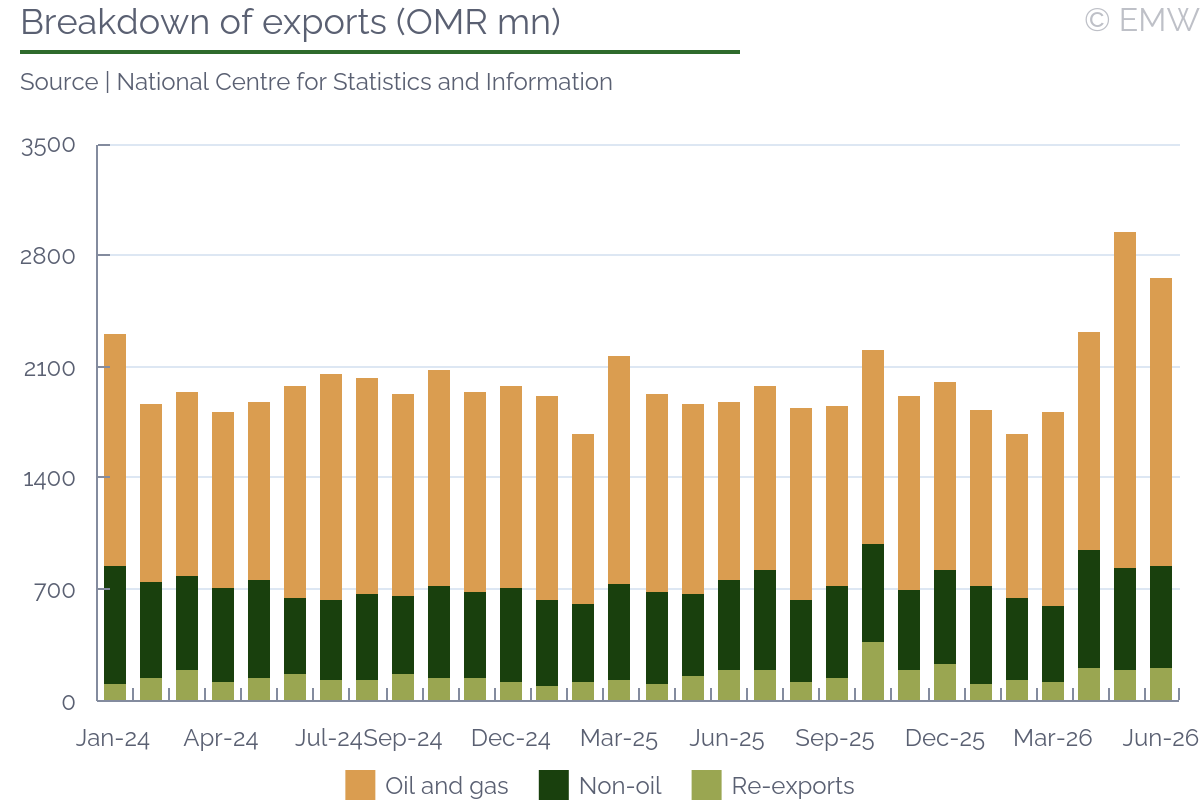
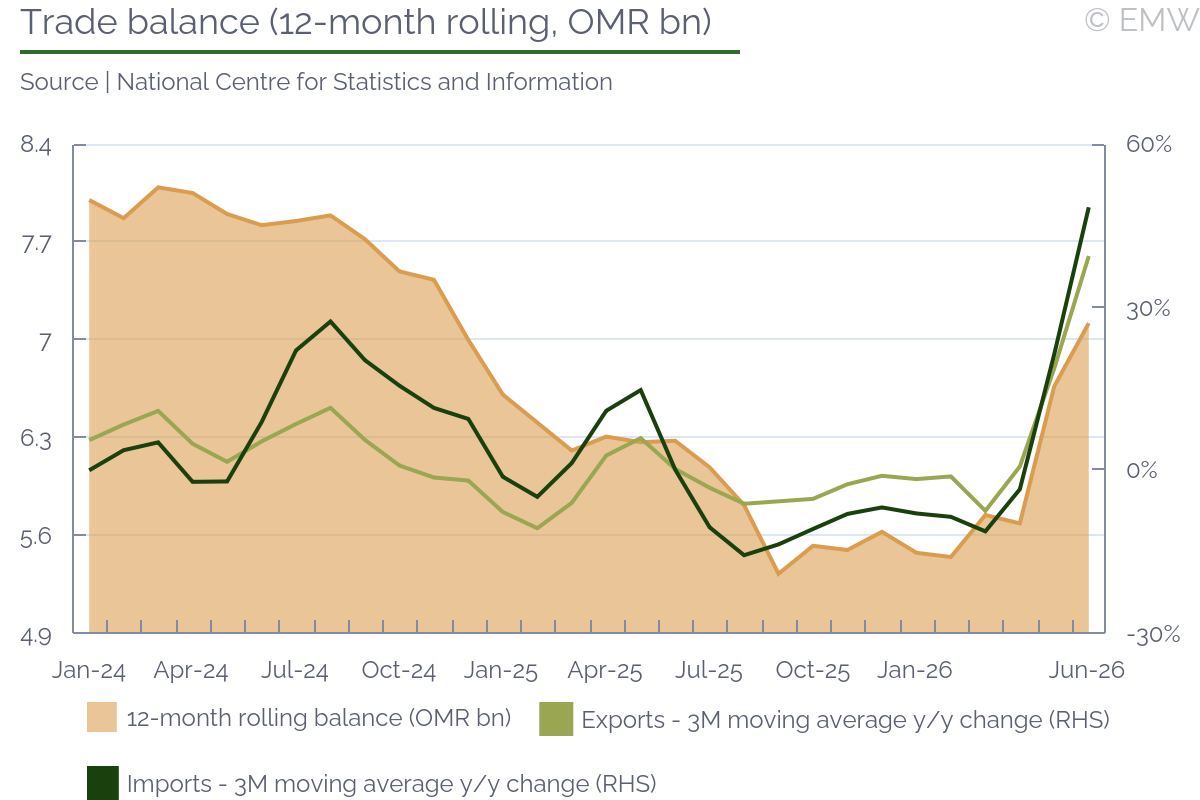
Oman's trade surplus jumped 53% y/y to OMR 5.5bn (USD 14.19bn) during the first seven months of 2026, according to data from the National Centre for Statistics & Information (NCSI). A breakdown shows total merchandise exports increased by 18% y/y to OMR 15.9bn (USD 41.2bn). Meanwhile, imports increased by 5% y/y to OMR 10.4bn (USD 27.1bn). This measured growth in imports, combined with surging export revenues, played a large role in widening Oman's overall trade balance. | External merchandise trade (OMR mn) | | Jan - July 2025 | Jan - July 2026 | Y/Y change | | Exports | 13,463 | 15,866 | 18% | | Oil and gas | 8,566 | 10,417 | 22% | | Non-oil | 3,893 | 4,309 | 11% | | Re-exports | 1004 | 1140 | 14% | | Imports | 9,898 | 10,409 | 5% | | Balance | 3565 | 5457 | 53% |
| | Source: National Centre for Statistics & Information |
The 18% y/y jump in total exports was primarily driven by oil and natural gas exports, which increased 22% y/y to OMR 10.4bn (USD 27.1bn). Non-oil exports also showed solid growth, increasing 11% y/y to OMR 4.3bn (USD 11.2bn). Similarly, re-exports rose 14% y/y to OMR 1.1bn (USD 3bn). Within the oil and gas sector, the underlying driving factor was a 44% y/y rise in LNG sales, which reached OMR 1.7bn (USD 4.4bn). This rapid growth in natural gas complemented a 19% y/y increase in crude oil exports, which reached OMR 5.9bn (USD 15.3bn), while refined oil exports grew 17% y/y to OMR 2.8bn (USD 7.4bn). Meanwhile, the 11% y/y increase in non-oil exports was supported by a 27% y/y surge in base metals and metallurgical articles to OMR 994mn (USD 2.6bn). Products of chemical industries also jumped 26% y/y to OMR 627mn (USD 1.6bn), while plastics and rubber products grew by 6% y/y to OMR 600mn (USD 1.6bn). The statistics show that the UAE remains Oman's dominant trading partner through July 2026. The neighbouring country acted as the top destination for Omani non-oil exports, which increased by 101% y/y to OMR 1.4bn (USD 3.6bn), and remained the largest individual source of Omani imports at OMR 2.9bn (USD 7.4bn), up 23% y/y. | Omani Non-Oil Exports (Jan - July 2026) | | Oman Non-Oil Trade Partners (Jan - July 2026) | Exports (OMR mn) | Y/Y Change | | United Arab Emirates | 1,390 | 101% | | Saudi Arabia | 418 | -37% | | India | 402 | 1% | | United States | 286 | 28% | | South Korea | 179 | -45% |
| | Source: National Centre for Statistics & Information |
Imports The 5% y/y increase in total merchandise imports highlights shifting dynamics in Oman's industrial and domestic demand through July 2026, resulting in highly uneven growth across different types of goods: - Natural or Cultured Pearls & Precious Metals: Rocketed by 432% y/y to OMR 1bn (USD 2.65bn).
- Electrical Machinery & Mechanical Equipment: Surged by 26% y/y to OMR 2.1bn (USD 5.5bn), indicating sustained investments in domestic infrastructure and technology.
- Base Metals and Articles: Rose by 12% y/y to OMR 1bn (USD 2.7bn).
- Transport Equipment: Decreased by 4% y/y to OMR 1bn (USD 2.6bn).
- Mineral Products: Plummeted by 34% y/y to OMR 1.6bn (USD 4.1bn), suggesting that Oman continues to substitute foreign raw materials with domestic supply.
The import landscape also saw notable geographic shifts during the first seven months of 2026 as Oman rearranged several of its key supply chain relationships: - UAE: Imports grew by 23% y/y to OMR 2.9bn (USD 7.4bn), commanding a 27% share of all goods entering the Sultanate.
- China: Imports grew by 42% y/y to OMR 1.4bn (USD 3.7bn).
- Turkey: Imports exploded by 424% y/y to OMR 745mn (USD 1.9bn).
- India: Imports dropped by 7% y/y to OMR 744mn (USD 1.9bn).
- Saudi Arabia: Imports fell 15% y/y to OMR 649mn (USD 1.7bn).
|
|
|
|
| Saudi Arabia |
|
| Deficit in banks’ net foreign assets widens to USD 58.0bn at end-August |
|
| Saudi Arabia | Oct 01, 11:28 |
|
- Foreign assets fall sharply m/m, foreign liabilities fall at slower pace
- Foreign assets now account for 8.1% of banks' total assets and for 13.6% of total deposits
The deficit in banks' net foreign assets widened for the first time in three months in August, to SAR 217.3bn (USD 58.0bn) as of end-month from a SAR 210.8bn deficit a month earlier, according to figures released by the central bank (SAMA). The NFA deficit rose because of falling foreign assets, which in turn reflected falling claims on foreign banks and foreign branches. Foreign liabilities also fell on the month, albeit by a smaller amount. That drop was mostly concentrated in liabilities to foreign banks. We note that credit growth in Saudi Arabia outpaced the growth in deposits for two years in a row, leading to tighter liquidity and encouraging the commercial banks to look for additional funds from foreign banks, leading in general to growing external liabilities. Meanwhile, the net foreign assets of SAMA remain sizeable, recording a net asset position of around USD 464bn and accounting for about 35% of GDP. 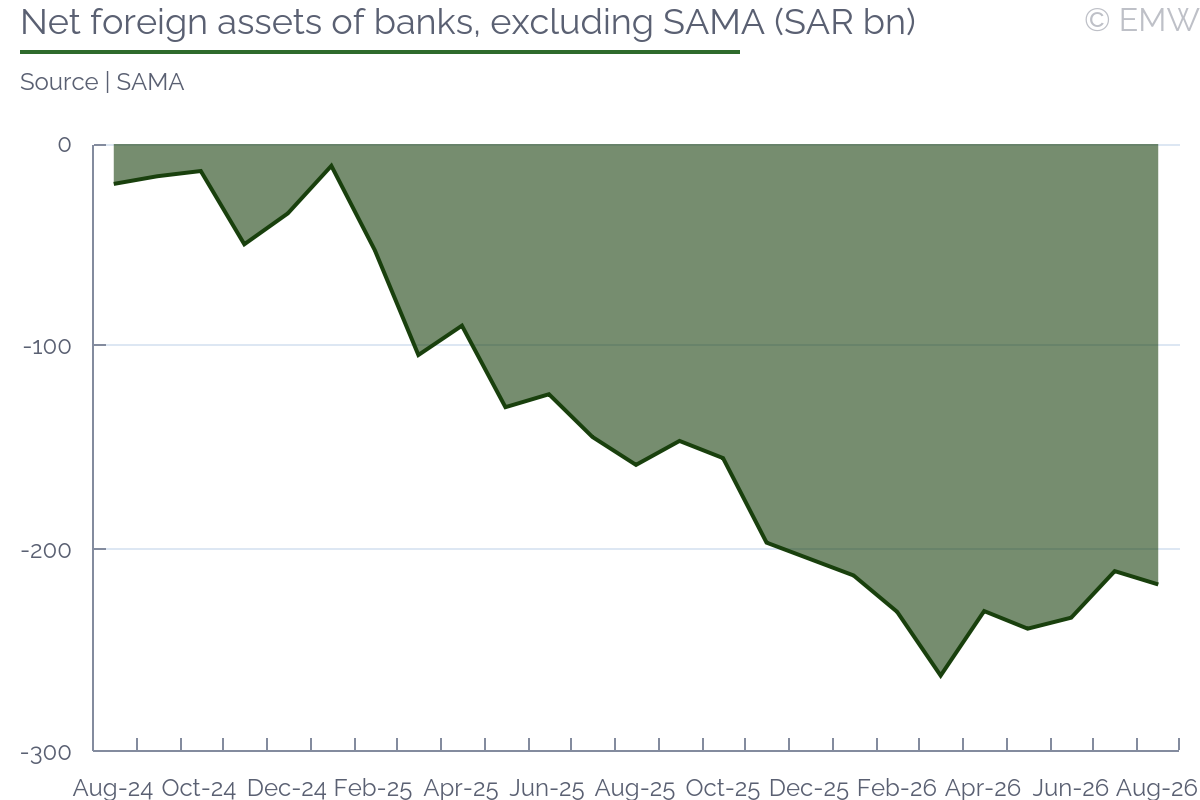 Banks' foreign assets are equal to 8.1% of banks' total assets and 13.6% of their total deposits. NFAs peaked in Apr 2023 and have been trending down since then on the back of rising foreign liabilities, especially to other creditors and foreign banks. We think overall NFAs will remain in a deficit position in 2026, and it seems that even high oil prices would not be able to help ease the pressure in this account. | Foreign Assets and Liabilities of Banks (SAR bn) | | Apr-26 | May-26 | Jun-26 | Jul-26 | Aug-26 | | Foreign assets | 431.0 | 429.9 | 431.9 | 439.3 | 419.0 | | Due from banks abroad | 61.7 | 57.0 | 52.6 | 59.3 | 46.6 | | Due from branches abroad | 74.6 | 75.4 | 77.4 | 77.2 | 69.8 | | Investments abroad | 220.0 | 222.1 | 225.5 | 225.8 | 227.0 | | Other assets | 74.7 | 75.4 | 76.3 | 76.9 | 75.6 | | Foreign liabilities | 661.5 | 669.0 | 665.7 | 650.1 | 636.3 | | Due to banks abroad | 302.8 | 307.9 | 310.2 | 305.2 | 290.4 | | Due to branches abroad | 99.5 | 97.0 | 103.9 | 96.8 | 100.7 | | Due to others | 259.2 | 264.2 | 251.5 | 248.1 | 245.2 | | Net foreign assets of banks | -230.5 | -239.1 | -233.7 | -210.8 | -217.3 | | Net foreign assets of SAMA | 1,768.2 | 1,743.5 | 1,768.3 | 1,746.0 | 1,740.5 |
| | Source: SAMA |
|
|
|
|
|
| Saudi Arabia | Oct 01, 08:32 |
|
Oil dips as recovering Gulf exports ease supply fears, US-Iran diplomacy in focus (Arab News) Saudi Red Sea Yacht Show targets over USD 480mn in investment returns (Arab News) Saudi Arabia projects 2027 budget deficit at 3.6% of GDP (Saudi Gazette) Saudi Arabia will respond decisively to any threat to its security (Saudi Gazette) Saudi Arabia's unemployment rate drops to 6.5% in Q2 2026 (Saudi Gazette) Saudi Vision 2030 programmes achieve 93% of targets, Crown Prince says (Zawya) Humain picks EY MENA to develop Saudi Arabia's first AI-native BPO service (Zawya) Saudi Arabia planning Oman pipeline, says Total CEO (AGBI) Red Sea disruption threatens Saudi petchems' recovery (AGBI) Saudi foreign investment drops during Iran war (AGBI) |
|
|
|
| FX reserves fall by 0.3% m/m to USD 487bn as of end-August |
|
| Saudi Arabia | Oct 01, 07:36 |
|
- FX reserves boosted by Aramco's dividend paid every three months, next payment due in September
- Saudi Arabia raised USD 24bn in Eurobonds and loans in January, issued USD 3bn Sukuk in September
- Oil revenues come under pressure in Jul-Sep because of Houthi attacks on key oil assets
The total reserve assets of the central bank (SAMA) fell by USD 1.3bn or 0.3% m/m to USD 487bn as of end-August, following a sharper 1.2% m/m decline in the preceding month, according to SAMA's monthly report. According to our calculations, Saudi Arabia's foreign reserves are enough to finance more than two years of imports, so the external position remains healthy, despite the unprecedented regional insecurity. We note that FX reserves are boosted every three months by the dividend payment by Saudi Aramco. The last such payment was on Jun 9, and the next one should take place in September. Aramco's dividends are a major revenue source for the government and a significant boost to FX reserves. The company's shares rallied after oil prices jumped in March as the kingdom has maintained its alternative oil export capabilities, while high oil prices offset the drop in exported volumes during Q2. However, oil revenues came under pressure in Jul-Sep because of Houthi attacks on Saudi tankers in the Red Sea and drone attacks on the key East-West pipeline. According to news reports, however, Saudi Arabia stepped up ship-by-ship transfers off the coast of Oman and managed to make up for the lost crude loadings in the Red Sea. 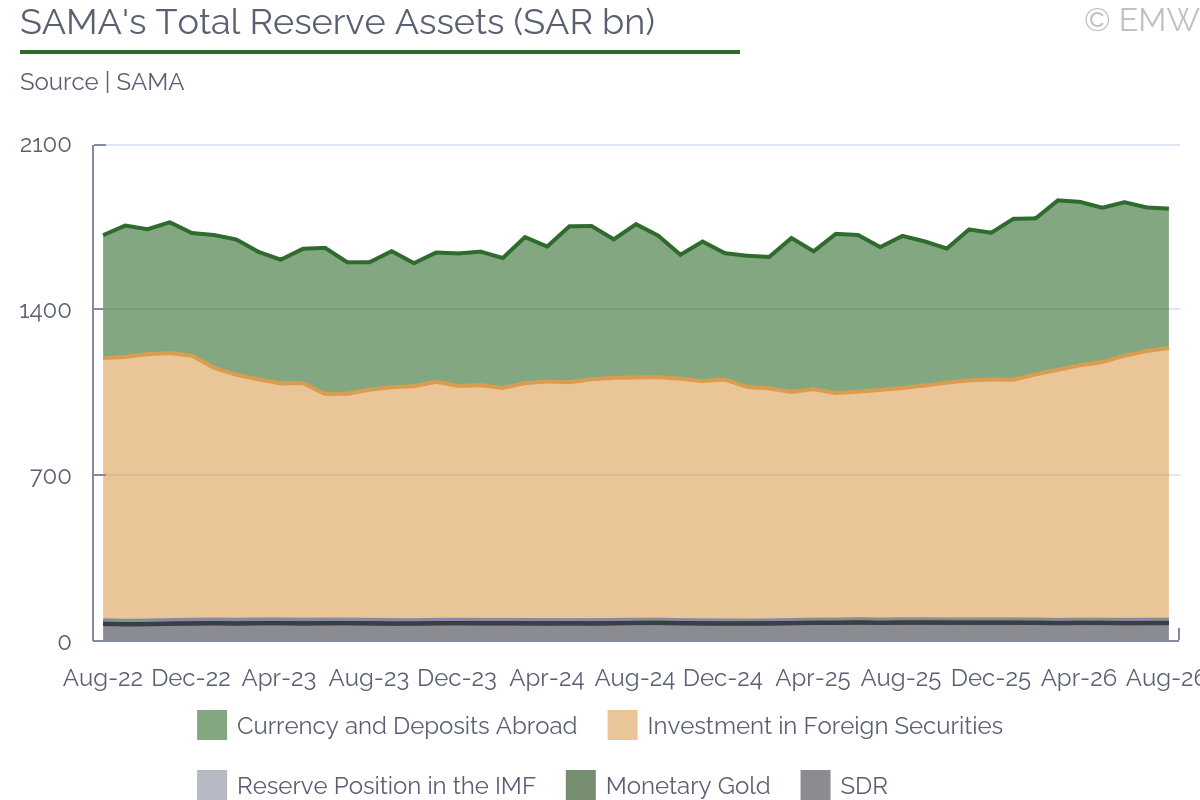 SAMA's reserve assets are up 6.7% y/y supported by Eurobond issuances (USD 11.5bn, another USD 3.3bn Sukuk was issued in September), foreign loans (USD 13bn), and high oil prices, while the blockade of the Hormuz Strait dragged on Saudi imports via the Gulf ports. Saudi Arabia managed to export crude oil via the Red Sea during Q2, thus reaping the benefits of high oil prices. However, the Iran-backed Houthis entered the conflict in July, forcing Saudi tankers to head north to the Suez Canal and Egypt's SUMED pipeline, adding significant costs and delays. Saudi Arabia formed a 14-country maritime defence alliance to counter the Houthis in the Red Sea, and began offering Saudi crude via ship-to-ship transfers off the coast of Oman in August. |
|
|
|
| | Ministry of finance projects fiscal deficit of 3.6% of GDP in 2027 |
|
| Saudi Arabia | Oct 01, 06:41 |
|
- Ministry to release detailed borrowing plans for 2027 by year-end
- Iran war: 2026 deficit forecast raised to 4.9% of GDP as economy swings to a 3.6% contraction
- GDP growth to rebound to 12.8% in 2027, inflation to remain stable
The finance ministry projects a fiscal deficit of 3.6% of GDP in 2027, narrowing from the revised deficit of 4.9% in the current year, the ministry said in a pre-budget statement on Wednesday. Revenues are seen at SAR 1.20tn next year (gradually growing to SAR 1.35tn by 2029), while expenditure is expected at SAR 1.39tn (USD 370bn). The government plans to continue borrowing in domestic and international markets in 2027, in line with its medium-term debt strategy, although more concrete details will be released by the end of the year. Financing will include bonds, sukuk and loans, alongside alternative funding channels such as project and infrastructure financing and export credit agencies. The finance ministry said the 2027 budget estimates should be viewed against a global backdrop of continued uncertainty and accelerating geopolitical developments. | Medium-term Fiscal Projections (SAR bn) | | 2025 actual | 2026 budget | 2026 est | 2027* | 2028* | 2029* | | Total Revenues | 1,112 | 1,147 | 1,190 | 1,202 | 1,302 | 1,351 | | Total Expenditures | 1,388 | 1,313 | 1,435 | 1,392 | 1,479 | 1,544 | | Budget Balance | -277 | -165 | -245 | -191 | -177 | -192 | | As % of GDP | -5.8 | -3.3 | -4.9 | -3.6 | -3.1 | -3.3 |
| | Note: *Projections | | Source: MoF's 2027 pre-budget document |
The impact of the Iran war Economic and geopolitical developments in 2026 have weighed on the kingdom's growth outlook, with preliminary estimates indicating a 3.6% contraction in GDP, largely driven by a projected 21.8% contraction in oil activities. Non-oil activities, on the other hand, are expected to grow by 3.2% this year, partly offsetting the impact of weaker oil-sector performance. The government attributed the resilience of the non-oil economy to reforms introduced since the launch of Vision 2030, which have helped diversify economic activity, improve the business environment and expand the private sector's contribution to growth. Inflation is projected at around 2.1% this year, while unemployment among Saudi nationals is expected to remain low at around 6.5%. Growth outlook The ministry expects that GDP growth will rebound to 12.8% in 2027. Inflation is expected to remain stable over the period, easing to 1.9% and remaining at that level between 2027 and 2029. The ministry said it would continue to manage public finances with a long-term perspective, preserving its capacity to respond to external shocks while maintaining spending on development and strategic priorities. It added that economic transformation plans would continue to focus on supporting growth, broadening the economic base and expanding non-oil revenues to secure more stable and sustainable income over the medium and long term. | Projections of Key Economic Indicators (%) | | 2025 actual | 2026 est | 2027* | 2028* | 2029* | | GDP growth | 4.6 | -3.6 | 12.8 | 3.9 | 5.7 | | nGDP (SAR bn) | 4,776 | 4,978 | 5,358 | 5,695 | 5,869 | | Inflation | 2.0 | 2.1 | 1.9 | 1.9 | 1.9 |
| | Note: *Projections | | Source: Ministry of Finance's 2027 pre-budget document |
Click here for our comprehensive database of macro forecasts. |
|
|
|
| | Unemployment rate among Saudi citizens edges up to 6.5% in Q2 |
|
| Saudi Arabia | Sep 30, 14:18 |
|
- Labour market conditions weaken slightly due to rising female unemployment and falling female participation rates
- Falling non-Saudi unemployment defies slowdown in construction, infrastructure projects
- Total unemployment has been gradually declining due to government initiatives, robust private sector growth, new industries
- Job market has undergone significant expansion in private sector employment coupled with consistent growth in public sector jobs
The unemployment rate among Saudi citizens edged up to 6.5% in Q2 2026 from 6.4% in the preceding quarter, according to the Labour Force Survey published by the stats office. The quarterly increase was entirely due to rising unemployment among females (up 0.6pps q/q to 9.6%), while the unemployment rate among Saudi men edged down 0.1pp q/q to 4.8%. Meanwhile, the unemployment rate among non-Saudis fell for the second quarter in a row, reaching 1.3%, and resulting in a nationwide unemployment rate of 3.0%. We thought that the unemployment rate among non-Saudis would pick up this year after the government scaled back some of the large infrastructure projects and business confidence weakened due to regional instability. However, it seems that the demand for foreign workers remains robust, especially in Riyadh. We note that foreign workers are not allowed to live in the country unless they are employed. While the government has moved aggressively to restrict foreign employment in some sectors to boost employment among Saudi citizens, the kingdom continues to rely heavily on foreign workers in labour-intensive sectors such as construction. 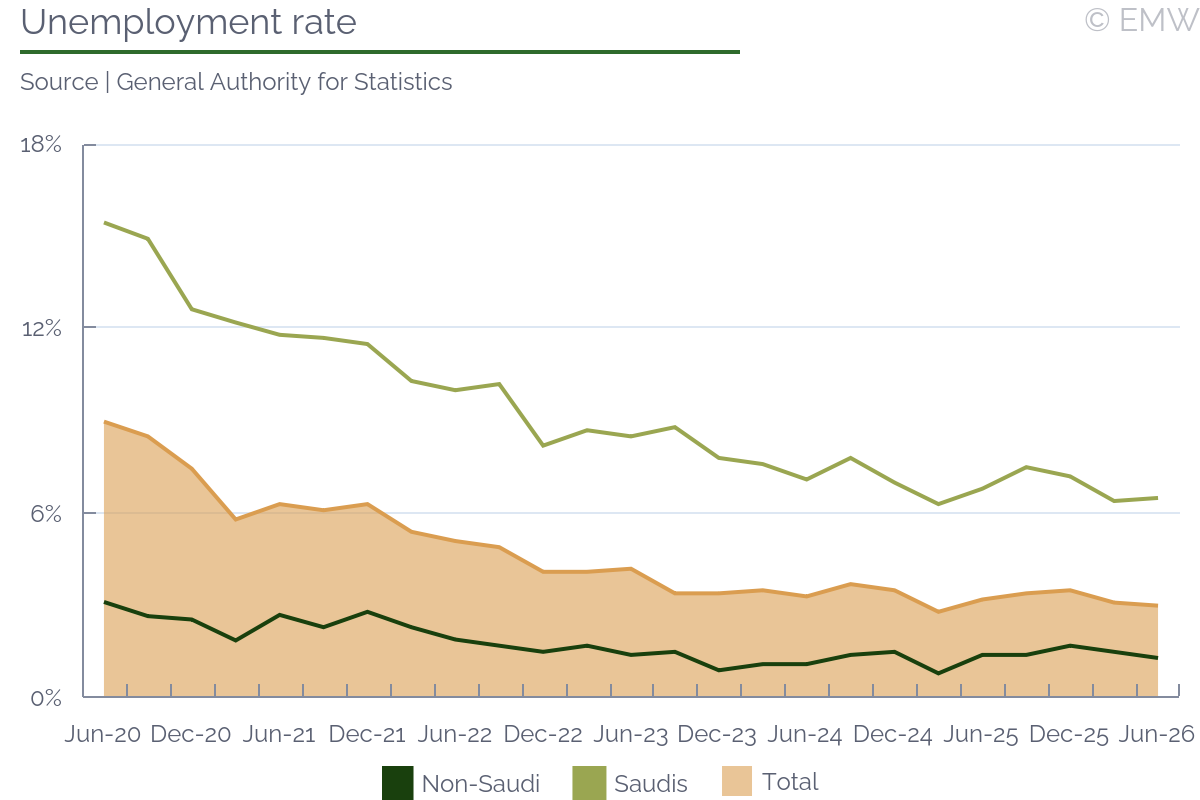 Over the past few years, the labour market saw a sharp increase in employment numbers across various sectors, especially in manufacturing, construction, and hospitality, supported by a recent tourism boom. This resurgence was marked by a significant increase in the employment of high-skilled Saudis and non-Saudis in the professional, scientific, and technical fields, and the trend of employing skilled expatriate workers was crucial for addressing the skill mismatches in the local labour market. Further, the job market has undergone a significant expansion in private sector employment coupled with consistent growth in public sector jobs, highlighting an improved diversity within the workforce. Saudi Arabia has also taken steps in recent years to create more job opportunities for women, which halved the female unemployment rate from around 30% in 2020. As of June, the female labor force participation rate was 34%, surpassing the Vision 2030 initial target of 30% (this target was raised to 40% last year). While structural and cultural factors keep around 65% of Saudi women out of the labour force, there have been some notable improvements over the past few years. However, the Iran war has dealt a serious blow to the kingdom's economic diversification plans, revealing a vulnerability in the economic diversification program, so we expect that the labour market will soften further this year. | Labour participation among Saudis (%) | | Q2 25 | Q3 25 | Q4 25 | Q1 26 | Q2 26 | | Males | 64.0 | 64.3 | 64.7 | 64.2 | 63.9 | | Females | 34.5 | 33.7 | 34.5 | 33.9 | 33.7 | | Total | 49.2 | 49.0 | 49.5 | 49.0 | 48.7 |
| | Source: General Authority for Statistics |
Labour Force Participation The Labor Force participation rate of Saudis weakened for the second quarter in a row, reaching 48.7%, while the employment-to-population ratio fell to 45.5%. Among Saudi core working age population (25-54 years), the quarter saw a drop in the employment-to-population ratio by 0.4pps q/q to 62.9%, while the Labor force participation rate fell to 66.6%. The unemployment rate in the prime working age rose to 5.5%, which is still near the historic low. The median age in the kingdom is 29 and Saudis under 30 make up 63% of the total population. Hence, one of the government's main tasks is to provide young people with meaningful employment. |
|
|
|
| Tunisia |
|
| IsDB approves EUR 335.5mn for motorway extension to El Kef and Jendouba |
|
| Tunisia | Oct 01, 07:00 |
|
- Financing will support better road connectivity between Tunis and the underserved northwest
- Project aligns with government's 2026-2030 development agenda
The Islamic Development Bank (IsDB) has approved EUR 335.49mn for Tunisia's highway-network extension towards El Kef and Jendouba, as part of a broader USD 938mn package approved for projects across six member countries. According to the IsDB, the project is intended to improve accessibility and connectivity, support economic integration and regional development, and strengthen road safety and transport infrastructure. The investment is particularly relevant for the relatively less-developed northwest, where weak transport links have been a longstanding constraint on investment and access to markets. The financing adds another sizeable externally funded infrastructure project as the government is seeking to raise investment under the 2026-2030 Development Plan while preserving limited domestic fiscal space. Unlike general budget financing, the IsDB funds are tied to a specific transport project. |
|
|
|
| BCT governor proposes Arab swap network against external shocks |
|
| Tunisia | Oct 01, 06:20 |
|
- Proposal would provide pre-arranged regional liquidity during periods of market stress
- Nouri also calls for joint stress tests and an Arab early warning system
BCT governor Fethi Zouhair Nouri has proposed creating a regional network of swap and repo lines to provide Arab economies with liquidity during periods of financial stress, as part of a broader push to move regional monetary cooperation towards pre-arranged crisis protection mechanisms. Speaking at the 50th meeting of Arab central bank governors, Nouri also proposed common regional stress tests, an early-warning system covering energy, food, trade and capital-flow risks, greater use of the Buna cross-border payments platform and annual exercises to test the resilience of payment systems. The emphasis on pre-arranged liquidity facilities aligns with the vulnerability constraints in several Arab economies, including Tunisia. Tunisia secured around USD 312mn in financing from the Arab Monetary Fund in July to support its balance of payments needs and economic reform programme. |
|
|
|
| Angola |
|
| | Fiscal pressures, FX stability and the Moody's outlook for Angola |
|
| Angola | Oct 01, 11:27 |
|
Question: HI on Angola: Moody's moved Angola to positive last week, citing FX stability, lower inflation and a falling debt ratio. How much of that improvement comes from the peg itself? The kwanza has held at 912 for two years with a 20-30% gpa in parallel FX markets. The H1 deficit looked much worse than the budget was 2.9% of GDP in six months against a 2.8% full-year target. what drove this? are they spending a lot on fuel subsidies? or is it due to lower oil production? October and November loading programmes are around 900 and 850 kb/d. Reserves excluding gold are lower than in January 2025, despite the oil windfall. Are they funding the fuel subsidy off balance sheet via Sonangol? i see that they've already which borrowed over $5bn in the first half and is owed over $4bn by the state. With no pump-price adjustment expected before the August 2027 election, is the fiscal position deteriorating behind a stable exchange rate? And how large an adjustment should we expect after the vote? Answer: I think there is a genuine tension between Moody's positive-outlook rationale and the underlying fiscal and FX dynamics, although I would not characterise the current situation simply as "fiscal deterioration behind a stable exchange rate". FX stability is an important part of the improvement in Angola's debt metrics, but I would not describe the current regime as a hard peg. The kwanza has been broadly stable around AOA 912/USD since late 2024, and Moody's explicitly says this has helped reduce the debt ratio by limiting the local-currency increase in the value of the roughly 80% of government debt denominated in FX. It is therefore a meaningful mechanical contributor to the improvement in debt/GDP. Moody's also notes that FX conditions have remained orderly, with reserves broadly maintained around USD 15bn. It is worth noting, however, that the BNA has not recently been intervening to support the currency. Stable external financing access, relatively stable FX oil inflows and the government's debt-management strategy have been the main factors underpinning FX stability. The latter includes greater reliance on local-currency issuance and active debt-management operations to reduce short-term repayment pressures. Overall, I would expect a sharp fall in oil prices to change this dynamic and renew depreciation pressure on the kwanza. The H1 fiscal deterioration looks more like an expenditure problem than an oil-revenue problem. Revenue execution has been relatively smooth, including on the non-oil side, while spending remains elevated, particularly on goods and services. This is important because it suggests that the H1 deficit was not primarily driven by weaker oil production or a shortfall in oil revenue. Fuel subsidies are part of the budget, but the important distinction is how they are financed. I would not describe them as "off balance sheet". The subsidy is a budget expenditure and therefore worsens the fiscal balance. However, the government does not necessarily settle the subsidy obligation to Sonangol in cash immediately. The mechanism is essentially a netting arrangement. Sonangol owes the government oil-related taxes, while the government owes Sonangol compensation for selling fuel below cost. Rather than the government collecting the tax from Sonangol in cash and then paying the subsidy back, the two claims can be netted. This means the subsidy is recorded as expenditure, but the immediate cash-financing requirement is reduced because the government accumulates a payable to Sonangol. This is why Sonangol's borrowing matters. The company can effectively end up financing part of the government's subsidy obligation through its own balance sheet. The IMF describes the resulting government obligation as an account payable to Sonangol and notes that accumulation of this payable contributes to Sonangol's debt. Sonangol's debt is now part of the broader public-sector debt perimeter. I would therefore describe this as quasi-fiscal financing through Sonangol, rather than an off-budget subsidy. The subsidy remains in the fiscal accounts, but part of its cash financing is effectively shifted from the central government to the state company. I would nevertheless be cautious about linking all of Sonangol's recent borrowing directly to fuel subsidies. Some of the borrowing is clearly related to financing oil-sector investment and other corporate needs. The reserves story is therefore important. Gross reserves have not increased in line with the oil-price windfall and remain slightly below their January 2025 level. This suggests that stronger oil inflows are being absorbed by a combination of fiscal financing needs, debt-service requirements and FX-market management rather than accumulating entirely as external buffers. This is the part of the story that I think is worth watching most closely. The official exchange rate is stable, but if fiscal deficits remain elevated, government payables to Sonangol rise and reserves gradually decline, some of the adjustment is effectively being deferred rather than eliminated.
On the 2027 election and fuel prices, I would avoid putting a precise post-election adjustment into the base case. There is no clear official schedule that would allow us to quantify the size of a pump-price adjustment after the August 2027 election. The 2027 election will nevertheless be an important factor for the rating outlook because the policy direction after the election will determine how quickly fiscal consolidation and subsidy reform proceed. A continuation of the current policy framework would provide greater continuity, while a change in government could bring different spending priorities, particularly given opposition parties' emphasis on living standards and greater investment in areas such as health and education. The key issue for the sovereign profile would ultimately be how any change in policy translates into the fiscal deficit, public-sector borrowing requirements and the pace of subsidy reform. Overall, I would say the debt improvement is real, and FX stability has made a material mechanical contribution by containing the local-currency value of FX debt. But the H1 numbers show that fiscal adjustment is not yet complete. Fuel subsidies are a meaningful expenditure item, while their cash financing can be intermediated through Sonangol, creating government payables and potentially shifting liquidity pressure onto the SOE. The combination of stable FX, weaker reserve accumulation and rising quasi-fiscal exposure is therefore worth monitoring closely ahead of 2027. The question was asked in relation to the following story: Main Themes |
|
|
|
| Ethiopia |
|
| Reported drone strikes in Addis Ababa raise risk of wider conflict |
|
| Ethiopia | Oct 01, 10:49 |
|
- Explosions were heard overnight in Addis Ababa as opposition alliance claims drone strikes on military targets
- Intelligence service imposes indefinite ban on drone flights over the capital and surrounding areas
- Fighting continues across Tigray, Amhara and Afar, with tens of thousands reportedly displaced
Explosions were heard overnight in Addis Ababa as Ethiopia's renewed northern conflict showed potential signs of spreading to the capital, with a source linked to the opposition alliance claiming responsibility for several drone strikes, including against military headquarters. Reuters could not independently verify the claim, while there was no visible damage near the military base and federal authorities had not immediately commented. If confirmed, the attacks would represent the first known drone strikes by anti-government forces in Addis Ababa and would mark a further escalation of the conflict that began last week across Tigray, Amhara and Afar. Capital security risk adds new dimension to conflict Ethiopia's national intelligence service on Wednesday imposed an indefinite ban on drone flights over Addis Ababa and surrounding areas. The reported emergence of armed-drone capability among opposition forces follows claims by a pro-government militia that it captured drone frames and batteries from forces linked to the Tigray People's Liberation Front (TPLF), although Reuters could not independently verify this. Meanwhile, federal forces have reportedly advanced in southern Tigray, while opposition forces have captured or contested towns in Afar and Amhara. Tens of thousands have reportedly been displaced by fighting in Afar. Escalation increases economic and regional risks We note that any sustained conflict affecting Addis Ababa would represent a broader economic risk than the transport and communications disruptions already reported in northern Ethiopia. It could weigh on investor confidence and economic activity as the government targets more than 10% GDP growth in FY2026/27, while complicating the movement of goods, people and capital. The renewed fighting has already involved reported TPLF seizures of airports in Mekelle, Axum and Shire, while the newly formed alliance of armed groups has reportedly expanded fighting into Afar and Amhara after declaring a "defensive war" against the federal govt. The conflict also raises regional risks given tensions involving Eritrea, Sudan and Egypt, although the Ethiopian government's allegations of external support are denied by those countries. |
|
|
|
| Ghana |
|
| John Boadu retains lead in opposition NPP’s chairmanship race - poll |
|
| Ghana | Oct 01, 08:58 |
|
- Boadu is backed by 48% of NPP voters, slightly down from 51% in early September
- Main opposition party to elect new leadership on Oct 3
The former general secretary of the opposition New Patriotic Party (NPP), John Boadu, retained his lead in the party chairmanship race, according to the latest poll conducted by Global InfoAnalytics. According to the results, Boadu was backed by 48% of the NPP voters, slightly down from 51% in a poll published in early September. Former energy minister Boakye Agyarko came second with 38%, the same as earlier this month, while former NPP chairman Paul Afoko was third with 12%. The party elections will be held on Saturday, Oct 3. Global InfoAnalytics also asked respondents who they preferred for the position of NPP general secretary, and 71% pointed to incumbent Justin Kodua Frimpong, followed by Sylvester Tetteh with 17% and Eugene Antwi with 6%. |
|
|
|
| Government reportedly extends diesel subsidy by two more months |
|
| Ghana | Oct 01, 08:45 |
|
- Sources tell local media that size of subsidy remains, but its structure is changed
- Now it will include GHS 1 margin cut and suspension of GHS 1 D-levy
- Fuel prices are expected to rise further this month
The government decided to extend the diesel price subsidy of GHS 2 per litre for October and November, Joy FM and Citi FM reported citing sources within the government. According to them, the size of the intervention remains unchanged, but its structure is changed. Until now, the GHS 2 support came in the form of a reduction in statutory margins, but the government has now decided to reduce the margin cut to GHS 1 while also suspending the Energy Sector Shortfall and Debt Repayment Levy (D-levy) on diesel of GHS 1 per litre. The government decision will therefore not change the overall effect on fuel prices which are expected to rise this month. The Chamber of Petroleum Consumers (COPEC) recently said it expects the mean petrol price to rise by 5.2% and the mean diesel price by 22.9% as of Oct 1, mainly due to higher global prices, but also the slight weakening of the cedi. Automotive fuels have 1.7% weight in overall CPI, and a price hike of the expected size would add 0.1pp to inflation. |
|
|
|
|
| Ghana | Oct 01, 08:30 |
|
Mahama orders security agencies to make Ghana's ports 'ironclad' against drug trafficking (Joy FM) Okaikwei Central MP alleges Ghana was close to settling Tullow tax dispute for $150m (Joy FM) Auditor-General vows tough surcharges, unveils tracker, AI audits (Joy FM) Mahama faces economic, political constraints in galamsey fight - Senyo Hosi (Citi Newsroom) John Boadu leads NPP chairmanship race with 48% - Global InfoAnalytics (Citi Newsroom) Court grants EOCO arrest warrant to arrest Manhyia South MP (Starr FM) Baffour Awuah to turn himself in to EOCO today - JoyNews sources (Joy FM) GoldBod generates US$1.87bn in FX in September, beats target (Class FM) |
|
|
|
| GoldBod generates USD 1.9bn from gold sales in September |
|
| Ghana | Oct 01, 07:47 |
|
- Amount rises by 42.2% from August, exceeds USD 1.4bn monthly projection
- Of total, USD 1.2bn is provided to central bank, USD 701mn to commercial banks
- GoldBod expects to generate USD 1.5bn from gold sales in October
The Ghana Gold Board (GoldBod) announced that it generated USD 1.871bn in foreign exchange by selling gold from artisanal and small-scale mining (ASM) operations in September. The amount exceeded the USD 1.4bn target set for the month. Of total, USD 1.17bn was made available to the Bank of Ghana, way above the USD 700mn target. A further USD 701.3mn was made available to commercial banks, slightly above the USD 700mn target. The amount provided to the central bank is for reserve accumulation and the one to commercial banks is to support stability in the foreign exchange market. GoldBod started releasing information about gold sales last month, after the central bank and the government agreed on a new financing model for GoldBod's ASM operations. The new model came into effect on Aug 3, after the central bank stopped pre-financing gold purchases and GoldBod secured its own financing. In August, the first month under the new financing framework, GoldBod generated USD 1.315bn of which USD 668.2mn was provided to commercial banks through spot sales and funded forward arrangements, and USD 646.6mn was provided to the central bank under the Ghana Accelerated National Reserves Accumulation Policy (GANRAP). For October, GoldBod expects to generate USD 1.5bn, of which USD 1bn will be provided to commercial banks and USD 500mn to the central bank. The October programme will be implemented under GoldBod's newly developed Spot FX Sales/Intermediation Framework, which aims to strengthen transparency, fairness and regulatory compliance in the management of FX sales and intermediation by GoldBod. It marks the exit of the Bank of Ghana from FX intermediation and the assumption of full responsibility for FX intermediation by GoldBod. |
|
|
|
| Kenya |
|
| Sifuna allies win legal battle over Linda Mwananchi party name |
|
| Kenya | Oct 01, 08:47 |
|
- Ruling removes one hurdle to securing Sifuna's 2027 political vehicle
- Group faces 15 October deadline for registering authorised party officials
- Sifuna has emerged as one of the more prominent opposition figures
The Political Parties Disputes Tribunal has overturned the Registrar of Political Parties' refusal to reserve the Linda Mwananchi Movement name and ordered the Registrar to reserve it within seven days, handing Nairobi Senator Edwin Sifuna's allies a victory in their efforts to establish a political vehicle ahead of the 2027 election. The tribunal found there was no legal justification for the earlier refusal and also struck out submissions from the rival Liberty National Democratic Alliance, finding that it was not a fully registered political party and lacked legal capacity to participate in the proceedings. The ruling nevertheless leaves Sifuna's camp facing a tight electoral timetable. Political parties planning to contest the August 2027 election must submit the names and specimen signatures of authorised officials by 15 October and certified nomination rules by 30 October. Linda Mwananchi recently selected Sifuna as its presidential candidate and said it would unveil his political vehicle in early October. Sifuna has emerged as one of the more prominent opposition figures following his split with ODM's leadership over its cooperation with Ruto's government. A Mizani Africa poll, recently cited by the media, put his presidential support at 13.2%, behind Ruto at 38.7% and Kalonzo Musyoka at 27.5%, but ahead of Fred Matiang'i at 7.7%. Earlier surveys similarly placed Sifuna among the leading opposition contenders. The opposition nevertheless remains fragmented among several prospective candidates and political vehicles, while Ruto retains the advantage of incumbency ahead of the August 2027 election. |
|
|
|
| Govt appoints new CEOs at three key energy agencies |
|
| Kenya | Oct 01, 08:02 |
|
- New heads confirmed at EPRA, GDC and Ketraco
- EPRA leadership change follows controversy over emergency fuel import
- New CEOs oversee major regulatory, geothermal and transmission projects
The government has appointed new chief executives at three major energy-sector institutions, with Edward Kinyua taking over at the Energy and Petroleum Regulatory Authority (EPRA), Stephen Busieney at Geothermal Development Company (GDC) and Tom Imbo at Kenya Electricity Transmission Company (Ketraco). Energy Minister James Opiyo Wandayi said the appointments take effect immediately following recruitment by the respective boards, with each CEO serving an initial three-year term that may be renewed once. Kinyua, previously EPRA's director of petroleum and gas, replaces Daniel Kiptoo, who resigned in April following controversy over an emergency petrol cargo imported outside the government's G-to-G fuel arrangement. Busieney had headed GDC in an acting capacity since November 2025, while Imbo replaces John Mativo, who was dismissed. The appointments come as Ketraco prepares Kenya's first PPP-funded transmission lines, GDC seeks to expand geothermal development, and EPRA implements changes intended to open electricity distribution to additional operators. They also coincide with the launch of the Lamu refinery construction. |
|
|
|
|
| Kenya | Oct 01, 07:56 |
|
Early winners as Lamu refinery project kicks off (Business Daily) Sacco accounts holding millions rise to 154,000 (Business Daily) Revealed: Counties made Sh8.3bn manual payments outside payroll systems (Nation) Candles, rallies and reflection: ODM marks one year without Raila (Nation) Rising local demand drives up Ethiopia power imports (Nation) By hook or crook: Sh2.2tr Lamu refinery project kicks off amid scrutiny (The Standard) Sifuna gets party nod but will he beat key deadlines? (The Standard) Lenders tighten mortgage loans tap amid ballooning bad loans (The Standard) Mudavadi's 2027 election wish: No goons, no petitions (The Star) CBK licenses 29 more digital lenders as regulated credit market expands (The Star) Experts call for stronger health, social systems to support Kenya's ageing population (capitalfm.africa) Dangote East Africa refinery: Ruto assures Lamu residents land concerns will be handled lawfully (Citizen) 'Lekki proved it can be done, Lamu must repeat it,' Dangote says at refinery launch (Citizen) |
|
|
|
| Honeywell secures USD 300mn contract for Dangote's Lamu refinery |
|
| Kenya | Oct 01, 07:39 |
|
- US firm to provide technology, engineering services and equipment
- Existing Nigerian refinery designs expected to cut development time
- Dangote targets completion of Lamu facility within 40 months
- Uganda says it will proceed with its own refinery project
US-based Honeywell Technologies has secured a contract worth about USD 300mn to provide process technologies, licensing, engineering services, equipment, catalysts and digital solutions for Dangote Group's planned 700,000 bpd refinery in Lamu. Honeywell said it will draw on designs developed through its work on Dangote's Nigerian refinery, potentially reducing the development schedule by nearly two years compared with a typical new facility. The Lamu plant will be designed to process a range of crude feedstocks and produce petrol, diesel, jet fuel and polypropylene. The contract was announced as President William Ruto and Aliko Dangote formally broke ground on the USD 16bn project on 30 September. Dangote said the refinery should be completed within 40 months and also announced plans for an engineering school in Lamu to train 1,000 people. Ugandan President Museveni, who attended the ceremony, welcomed the offer for regional governments to acquire equity but said Uganda would continue with its own planned refinery. The Honeywell award follows a more than USD 450mn contract to India's Engineers India Limited, which will provide project-management and engineering, procurement and construction-management services. Dangote has offered regional governments a combined 30% stake in the Lamu project, with Kenya allocated 10% and potentially seeking more if other countries do not fully take up their allocations. |
|
|
|
| Govt raises KES 57.5bn in October bond auction |
|
| Kenya | Sep 30, 16:00 |
|
- Bids reach KES 80.6bn, equivalent to 161% of KES 50bn offered
- Gross T-bond issuance reaches KES 643bn so far in FY2026/27
- Net bond issuance is equivalent to 49% of annual securities borrowing target
The government raised KES 57.5bn in its October bond auction, exceeding the KES 50bn target after investors submitted KES 80.6bn of bids, CBK results showed. The reopened 7.8-year bond attracted KES 34.6bn of bids, of which KES 28.6bn was accepted at a weighted average yield of 12.73%. The 12.5-year paper drew KES 46.0bn, with KES 28.9bn accepted at 13.60%. Market weighted average rates were higher at 12.87% and 13.80%, respectively, indicating that CBK rejected bids seeking higher yields. The latest auction takes gross T-bond issuance so far in FY2026/27 to around KES 643bn, or 39% of the midpoint of the government's full-year issuance plan. Including planned monthly switch operations, the calendar envisages gross bond issuance of KES 1.37tn-1.93tn. Net bond issuance stands at around KES 483bn after KES 160bn of repayments, equivalent to 49% of the KES 987.4bn full-year net government securities borrowing target. The borrowing plan envisages meeting the target through net T-bill and bond issuance, although it notes that emphasis is on bonds; T-bills will be used primarily for cash and liquidity management. |
|
|
|
| Mozambique |
|
| Central bank reports stronger FX liquidity, prepares real-time market platform |
|
| Mozambique | Oct 01, 08:41 |
|
- Banks purchased USD 5.73bn in foreign currency through August, up USD 724mn y/y
- FX sales to clients rose USD 593mn to USD 5.65bn, despite continued access constraints for some companies
- BoM plans real-time FX platform as reserves remain under pressure and IMF flags external imbalances
The Bank of Mozambique (BoM) says foreign currency liquidity has been improving despite difficulties among some companies in accessing FX, rejecting the view that the country faces a generalised shortage. Governor Felisberto Navalha said banks purchased USD 5.73bn in foreign currency from exporters and other economic agents through August, up USD 724mn y/y. Commercial bank sales to clients also increased by USD 593mn to USD 5.65bn. BoM attributed the stronger FX activity partly to liquefied natural gas projects in the Rovuma Basin and the continued performance of the extractive sector, alongside exchange-rate stability. However, the latest reserve data point to continued pressure on the external buffer. BoM's net international reserves fell 0.8% m/m to USD 3.44bn at end-July, the lowest level since November 2023 and 14.0% below a year earlier. The decline contrasts with the stronger FX turnover reported by banks, highlighting the distinction between higher market transactions and the central bank's underlying reserve position. The IMF has continued to highlight persistent FX shortages, wider external imbalances and tight financing conditions, while projecting Mozambique's current account deficit at 43.0% of GDP in 2026. BoM plans to introduce a digital platform by end-December to monitor FX flows, including exporter supply, importer demand, prices and bank exchange rates. We note that stronger aggregate FX activity does not necessarily indicate that FX access constraints have been resolved. The new platform could help identify where liquidity bottlenecks are concentrated and strengthen BoM's ability to address them. |
|
|
|
| TotalEnergies sees scope to accelerate LNG phase 2 |
|
| Mozambique | Oct 01, 08:31 |
|
- TotalEnergies says Phase 2 could be accelerated by leveraging construction synergies
- Phase 1 remains targeted to start production in 2029, with construction progressing at full speed
- Area 1 holds about 65 TCF of gas reserves, according to TotalEnergies
TotalEnergies says it could accelerate the second phase of its Mozambique LNG project by leveraging existing construction activity and avoiding the demobilisation and subsequent remobilisation of teams already operating at the site. Speaking during the company's Strategy & Outlook 2026 presentation, Chairman and CEO Patrick Pouyanné said synergies from the current construction programme could allow Phase 2 to move forward more quickly. The comments add a new potential expansion dimension to Mozambique's LNG development beyond the first phase currently under construction. TotalEnergies is developing the first phase of Mozambique LNG in Area 1, with start-up targeted for 2029. President of Exploration and Production Nicolas Terraz said construction was progressing "at full speed", with around 10,000 people currently working on the site. Terraz also said Area 1 contains around 65 trillion cubic feet (TCF) of gas reserves, indicating a substantial resource base beyond the first phase currently being developed. Accelerating Phase 2 could improve the efficiency of Mozambique LNG's development by retaining construction capacity and infrastructure already being deployed. It could also bring forward additional investment and export capacity from the Rovuma Basin. However, the comments refer to a potential acceleration rather than a confirmed final investment decision or revised development schedule. The immediate milestone remains completion of Phase 1 and its targeted 2029 start-up. |
|
|
|
| Govt approves new VAT, income tax regulations |
|
| Mozambique | Oct 01, 08:27 |
|
- New regulations operationalise 2025 reforms covering VAT, corporate and personal income taxes
- ISPC turnover threshold raised 60% to MZN 4mn, with new 3-5% differentiated rates replacing the previous MZN 75,000 payment or 3% option
- 10% withholding tax introduced on digital goods and services and electronic-money agent commissions, while capital gains face 32% autonomous taxation
- VAT framework further incorporates digital supplies from non-resident providers, with revised VAT, IRPC, IRPS and ISPC rules effective from Jan 2026
Government approved new regulations governing Value-Added Tax (VAT), Corporate Income Tax (IRPC), Personal Income Tax (IRPS) and the Simplified Tax for Small Taxpayers (ISPC), advancing implementation of the tax reforms adopted at the end of 2025. The regulations establish procedures and administrative requirements for legislative changes that took effect from January 2026. For VAT, the framework further operationalises taxation of digital goods and services supplied by non-resident providers, including mechanisms requiring domestic acquirers to fulfil tax obligations on relevant transactions. The IRPC reforms include a 10% withholding tax on income from digital goods and services and commissions paid to electronic money agents, alongside 32% autonomous taxation of capital gains. Simplified accounting and taxable-income regimes have also been removed for affected companies, with organised accounting and computerised accounting systems required. Under the revised ISPC regime, eligibility has been extended to businesses with annual turnover of up to MZN 4mn, from MZN 2.5mn previously. The former fixed MZN 75,000 annual payment or 3% option has been replaced by differentiated turnover-based rates, including 3%, 4% and 5%, alongside quarterly taxation and invoicing requirements. We note that the measures should broaden the formal tax base and strengthen revenue administration, particularly in digital and small-business activity. However, the fiscal impact will depend on effective enforcement and compliance. This comes as FMO, a consortium of Mozambican non-governmental organizations, estimates PESOE-2027 debt service at MZN 98.932bn, around 24% above projected public investment of MZN 79.567bn, highlighting the tension between revenue mobilisation, debt obligations and development spending. |
|
|
|
| | MPC holds policy rate at 9.25% for fourth straight meeting |
|
| Mozambique | Oct 01, 08:09 |
|
- Rate unchanged as elevated climate and geopolitical risks keep inflation outlook uncertain
- Annual inflation eased to 6.5% in August from 7.5% in July, though BoM expects short-term price pressures before a return to single-digit inflation
- Real GDP growth improved to 1.7% y/y in Q2 from 0.1% in Q1, led by agriculture, extractives and services
- New 18-month reserve requirement regime to support import substitution and exports
- Next ordinary CPMO meeting is scheduled for Nov 25
The Monetary Policy Committee (CPMO) of the Bank of Mozambique (BoM) kept the monetary policy rate, MIMO, unchanged at 9.25%, marking the fourth consecutive hold. The decision reflected elevated inflation risks and uncertainties, including climate shocks and geopolitical tensions in the Middle East and Europe. The committee also changed the compulsory reserve regime, introducing an 18-month framework allowing banks to deduct qualifying new financing for companies supporting import substitution and/or higher exports from the domestic-currency component of reserve requirements. The applicable rate is the MIMO rate, with a margin of up to 150bps depending on the purpose. The decision matched our pre-meeting forecast of a 9.25% hold. 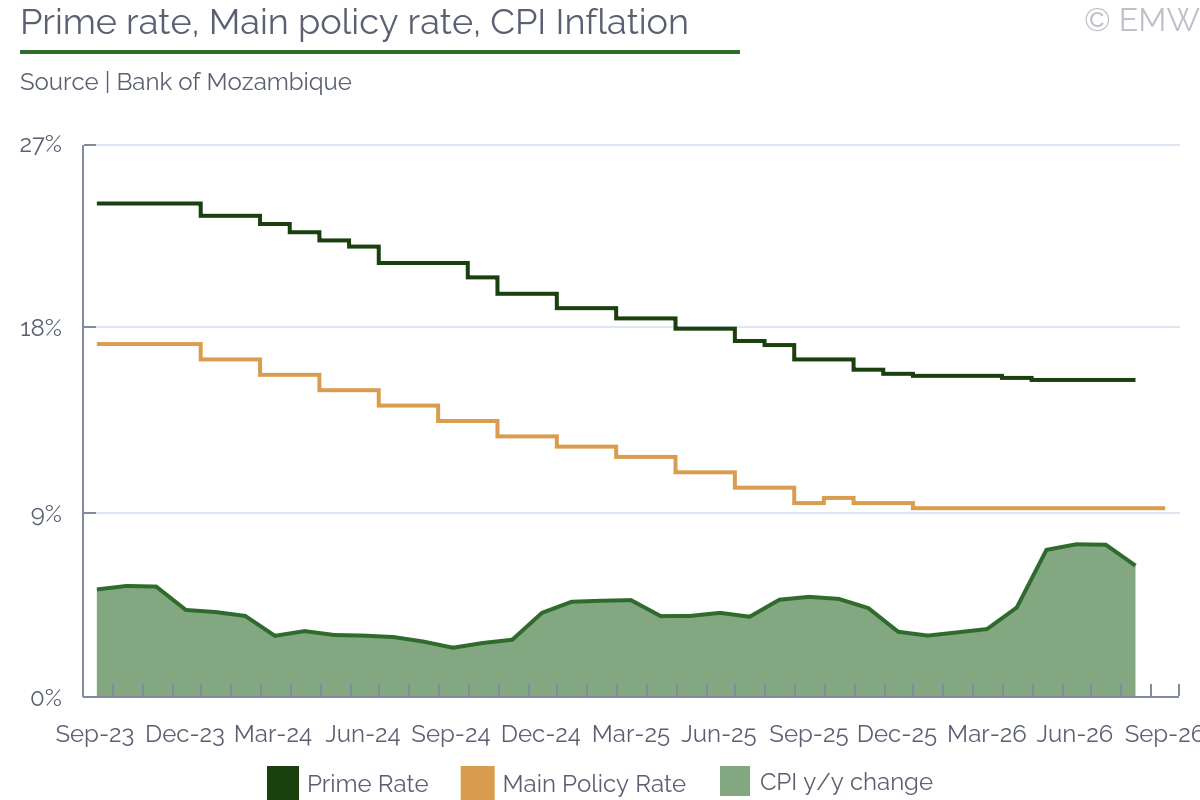 Annual inflation slowed to 6.5% y/y in August from 7.5% in July, while underlying inflation also declined. However, the BoM expects prices to rise in the short term due to imported inflation from major trading partners and higher fruit and vegetable prices after the rainy season. It expects inflation to return to single digits over the medium term, supported by stable metical conditions, contained domestic demand and lower international fuel and food prices. Real GDP growth accelerated to 1.7% y/y in Q2 from 0.1% in Q1, supported by agriculture, extractive industry and services. The BoM expects these sectors and projects in strategic areas to sustain moderate growth. Meanwhile, commercial banks' foreign-currency purchases rose by USD 724mn y/y to USD 5.73bn between January and August, while sales to clients increased by USD 593mn to USD 5.65bn. The maintenance of domestic and external debt arrears continues to affect financial-market functioning, with the BoM citing weak appetite for government securities, rigid money-market rates and higher sovereign risk. Domestic public debt stood at MZN 546.5bn in the latest position reported in the communiqué, up MZN 71.9bn from December 2025 and contributing to higher banking liquidity. Looking ahead, the CPMO will monitor inflation, public debt, climate shocks and geopolitical tensions. The reserve framework adds targeted support for import-substitution and export financing without changing the policy rate. This was also the first rate decision since Felisberto Dinis Navalha became governor and he may have decided to take a more cautious approach given that this was his first rate decision (the communiqué does not link the decision to the leadership transition). The next ordinary CPMO meeting is scheduled for Nov 25. |
|
|
|
| Senegal |
|
| | GDP growth prints at 6.1% y/y in Q2 2026 |
|
| Senegal | Oct 01, 11:35 |
|
- Non-oil GDP expands by 6.4% y/y, slightly faster than overall economy
- Services provide largest sectoral contribution to growth
- Net exports weigh down on activity
- New GDP series uses 2021 base year
Senegal's GDP (s.a.) expanded by 6.1% y/y in Q2 2026 under the new 2021-base national accounts series, while quarterly growth was limited to 0.1%, the latest report from statistics office ANSD showed. Non-oil GDP grew by a slightly stronger 6.4% y/y and also edged up by 0.1% q/q. The tertiary sector was the main driver of annual growth, expanding by 6.0% y/y and contributing 3.1pps to headline GDP growth. The secondary sector grew by 5.1% and contributed 1.3pps, while the primary sector expanded by 1.5% and contributed 0.2pps. Within services, trade grew by 8.0%, public administration by 11.7%, real estate by 6.1% and transport by 5.7%. Extractive industries expanded by 6.8%, but hydrocarbons themselves grew by only 2.1% and contributed just 0.1pps to overall growth. On a quarterly basis, activity was almost flat as a 1.0% q/q increase in the primary sector was largely offset by a 1.4% contraction in the secondary sector and a 0.2% decline in services. Extractive activity fell by 2.6% q/q, including a 0.3% decline in hydrocarbons, while trade contracted by 4.5%. In the expenditure breakdown, annual growth was driven by domestic demand rather than net exports. Final consumption rose by 5.5% y/y and contributed 4.6pps to GDP growth, while gross capital formation increased by 17.1% and contributed 3.9pps. By contrast, exports fell by 2.7% and subtracted 0.7pps, while the 4.8% increase in imports deducted another 1.6pps. We note the latest publication marks the introduction of quarterly national accounts aligned with the new 2021 base year, replacing the previous 2014-base series. | Quarterly GDP growth, % y/y | | Q2 25 | Q3 25 | Q4 25 | Q1 26 | Q2 26 | | Agriculture | 7.4% | 8.6% | 8.1% | 1.0% | 0.8% | | Exctractive industries | 63.3% | 55.8% | 57.5% | 11.0% | 6.8% | | Manufacturing industries | 4.7% | -2.3% | -0.7% | -0.1% | 2.7% | | Trade | -0.2% | 0.2% | 4.8% | 7.0% | 8.0% | | Public administration | 2.0% | 4.4% | 3.8% | 4.0% | 11.7% | | | Quarterly GDP | 6.9% | 3.9% | 7.2% | 4.3% | 6.1% |
| | Source: ANSD |
|
|
|
|
| Faye launches new youth council amid push for greater policy role |
|
| Senegal | Oct 01, 07:29 |
|
- Council to advise government on policies affecting young people
- Faye plans annual meetings with members to assess youth policies
- Govt told to urgently roll out already-approved employment policy
President Faye formally installed Senegal's new Youth Advisory Council (CCJS) on 29 September, creating an institutional channel for young people to contribute to policymaking, according to local news reports. The 1,227-member council comprises representatives elected at municipal, departmental and regional level as well as national representatives, and is intended to collect youth concerns and formulate recommendations on public policies affecting them. It replaces the former National Youth Council. Faye instructed the government to ensure the council is fully operational and to strengthen youth participation in policymaking, while announcing that he will meet its members annually to review and assess youth policies. At the subsequent cabinet meeting, he also called for the urgent rollout of the already-approved National Employment Policy and faster implementation of programmes supporting youth employment and socio-economic integration. The initiative comes as Faye seeks to maintain direct engagement with a politically and economically important young population following the breakdown of his alliance with Ousmane Sonko earlier this year. Youth employment and access to economic opportunities remain prominent policy concerns. |
|
|
|
| Cabinet adopts draft 2027 budget bill |
|
| Senegal | Oct 01, 07:19 |
|
- Govt had projected 2027 deficit at 4.9% of GDP in June, but the target likely to be upped after 2026 deficit revision to 7.6%
- Budget prepared alongside IMF programme and planned debt treatment
- Govt seeks financing for groundnut campaign, addresses unpaid power bills
Senegal's cabinet adopted the draft 2027 budget on 30 September, although its main fiscal or macroeconomic assumptions were not included in the meeting communique. We recall in its June medium-term budget framework, the government had targeted a deficit of 4.9% of GDP for 2027, falling to 3.8% in 2028 and the WAEMU ceiling of 3.0% in 2029. The framework will however likely be updated following the 2026 budget revision, which raised this year's deficit target to 7.6% of GDP and cut revenue projections, as well as the announcement of planned debt treatment and prospective new IMF programme. The cabinet also discussed unpaid electricity bills owed by the central administration and public entities, although no amount or settlement plan was disclosed. Faye called for the urgent rollout of the already-approved new National Employment Policy and instructed the government to ensure adequate financing for the forthcoming groundnut-marketing campaign and implementation of SONACOS's industrial transformation plan. The government will also hold an Interministerial Council on the Diomaye Plan for Casamance in Ziguinchor in November. |
|
|
|
| South Africa |
|
| ABSA Manufacturing PMI rebounds above 50 in September |
|
| South Africa | Oct 01, 12:25 |
|
- New orders recover sharply, while business activity nearly reverses its slump in August
- Underlying picture remains mixed as employment weakens and logistics delays boost the headline PMI
The seasonally adjusted ABSA Manufacturing PMI rose by 4.9 points to 50.7 in September, returning above the neutral 50-point mark after three consecutive months in contractionary territory, the Bureau for Economic Research (BER) said in a statement on Thursday (Oct 1). The improvement was driven by a sharp rebound in new sales orders and business activity, although the BER cautioned that logistics disruptions also mechanically supported the headline reading through the supplier-deliveries component. The business activity index jumped to 49.3 from 40.2 in August, recovering most of the previous month's decline, while new sales orders rose to 50.8 from 40.3. Export orders also improved to their strongest level since early 2025, suggesting that the recovery in demand was not solely domestic. However, respondents continued to report a mixed demand environment, including weak customer commitments, limited major projects and pressure on margins from imports and higher input costs. 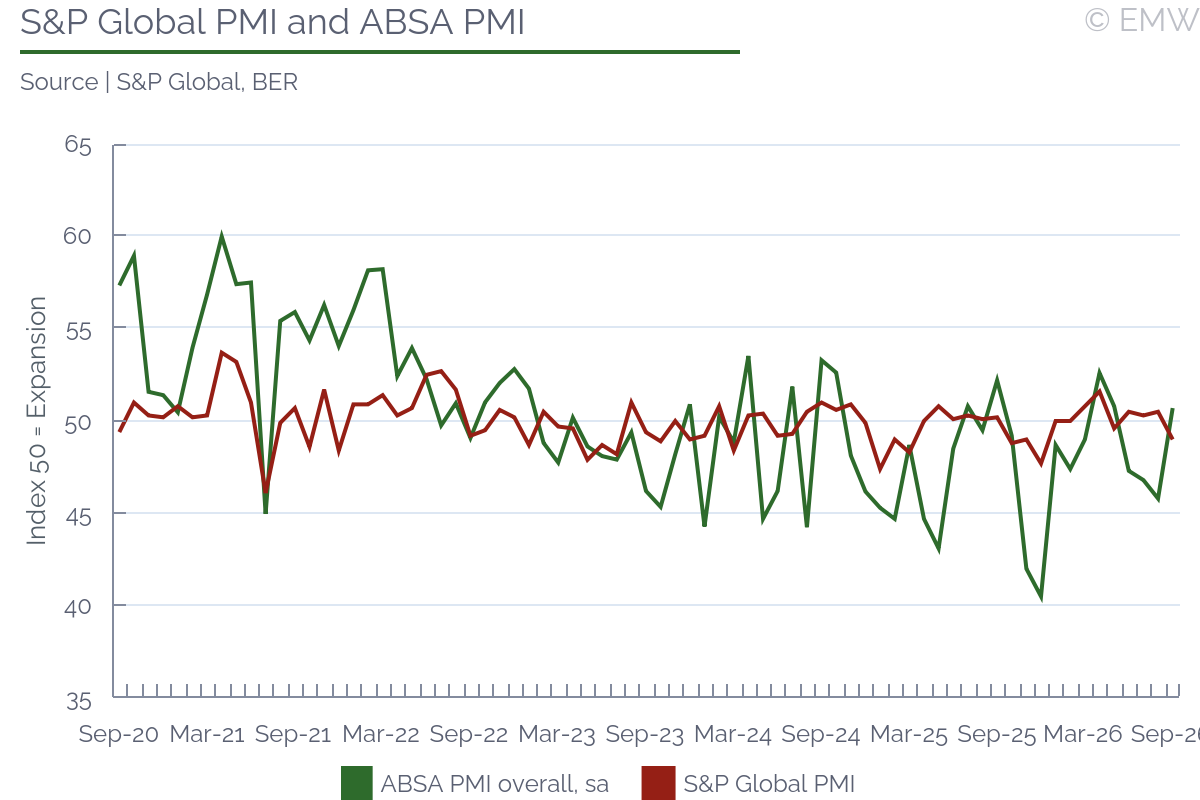 Meanwhile, the improvement did not spread to employment as the index fell to 43.1 from 46.2, indicating continued job shedding and suggesting that manufacturers remain cautious about the durability of the recovery. At the same time, inventories rose sharply to 52.2 from 43.6, potentially reflecting some restocking or preparation for stronger seasonal demand, although subdued order backlogs make it too early to read this as evidence of a broad-based upswing. The supplier deliveries sub-index stayed elevated at 58.4, with respondents citing delays at Durban port, longer shipping schedules and higher freight costs. Meanwhile, the purchasing price index rose to 71.1 from 67.2, reversing its recent decline as higher fuel, transport and logistics costs intensified input-price pressures. Overall, the September reading points to a meaningful improvement from August, but not yet a convincing manufacturing recovery. Business activity remains just below 50, employment is still contracting and part of the headline PMI strength reflects logistics bottlenecks rather than stronger demand. The BER said a sustained period above 50 would provide firmer evidence that the sector is entering a recovery. |
|
|
|
| Real net salaries resume decline in August as cost pressures persist |
|
| South Africa | Oct 01, 06:50 |
|
- Nominal net salaries slip 0.1% m/m to ZAR 21,622; annual growth eases to 1.9%
- Real salaries fall 0.5% m/m and 2.6% y/y, reversing July's brief improvement
- Weak real earnings and rising basic living costs continue to squeeze household spending
The average nominal net salary measured by the PayInc Net Salary Index rose by 0.2% m/m to ZAR 21,642 in July, before slipping 0.1% m/m to ZAR 21,622 in August. Annual nominal salary growth accelerated to 2.2% in July from 0.5% in June, before easing to 1.9% in August. Nominal net salaries were up only 1.6% on average ytd, compared with a 3.7% increase in 2025. Real net salaries increased 0.4% m/m in July, their first monthly gain in nine months, but declined again by 0.5% m/m in August to ZAR 20,164. The annual contraction widened to 2.6% from 2.2% in July, while real salaries were down 2.1% on average ytd, indicating that purchasing power remains under pressure. The squeeze on households persists despite headline inflation easing to 4.3% y/y in July and 4.4% y/y in August from 5.0% y/y in June, underscoring that nominal salary gains remain insufficient to restore lost purchasing power. PayInc expects inflation to move back above 5% in October, which would keep pressure on real incomes and discretionary consumer spending. |
|
|
|
|
| South Africa | Oct 01, 06:33 |
|
Law reform body calls for scrapping of lump-sum medical payouts (Business Day) Iran war wipes R300bn from PIC assets (Business Day) 'Price of conflict': Wages slip while rising food prices hit poor households (Business Day) SA keeps dialogue open after third rebuke of US ambassador Bozell (Business Day) Godongwana rules out scrapping PIC's unlisted investments (Business Day) 'We need our own': Coega could host oil refinery, says CEO (Business Day) November election a chance for SA to 'get out of our own way,' says economist Saville (News24) Gautrain finally gets new operator. More trains, longer hours promised (News24) PIC shoots the lights out with 20% growth, despite 'difficulties' (News24) Mashaba: 'I have unfinished business in Joburg' (Moneyweb) Ad hoc committee: MPs clash over future of IDAC (Eyewitness News) R182m NHI spin deal is a warning of what's to come (Daily Maverick) Freedom Front Plus' apartheid killers should not be elected councillors nor mayoral candidates (Daily Maverick) False white genocide claims divide us and obscure the wider crime crisis (Daily Maverick) Fenced in - why City Power's 'ringfencing' in Joburg is a 30% revenue grab (Daily Maverick) |
|
|
|
| | Trade surplus widens to ZAR 20.5bn in August as imports fall faster than exports |
|
| South Africa | Oct 01, 05:59 |
|
- Surplus remains sizeable, surprising consensus on the upside
- August surplus widening reflects weaker imports rather than stronger exports, however
- Jan-Aug surplus widens to ZAR 149.5bn as export growth continues to outpace imports
- Export gains remain heavily concentrated in precious metals and minerals, while manufactured exports are softer
The foreign trade account recorded a ZAR 20.5bn surplus in August, wider than the revised ZAR 18.0bn surplus in July, as imports contracted more sharply than exports, according to data released by the South African Revenue Service (SARS) on Wednesday (Sep 30). The print slightly exceeded consensus market expectations for a surplus of ZAR 17.0bn. Trade flows weakened overall during the month as exports declined 5.8% m/m to ZAR 181.8bn, while imports were down 7.8% m/m to ZAR 161.3bn. Exports experienced a relatively broad-based decline, including mineral (iron and coal) product down ZAR 4.5bn m/m, precious metals and stones by ZAR 3.6bn m/m and vegetable products by ZAR 1.5bn m/m, while machinery exports also declined. On the import side, the largest decline came from chemicals (-ZAR 3.4bn), original equipment components (-ZAR 2.9bn), machinery (-ZAR 1.8bn), vehicles and transport equipment (-ZAR 1.7bn) and mineral (oil) products (-ZAR 1.3bn). In cumulative terms, foreign trade performance remains relatively strong. The trade surplus increased to ZAR 149.5bn in the first eight months from ZAR 96.1bn a year earlier, with exports rising 7.8% y/y to ZAR 1,452bn, faster than the 4.1% y/y increase in imports to ZAR 1,303bn. The improvement is, however, concentrated in a relatively narrow group of export categories. Precious metals and stones exports are up 35.7% y/y and mineral (iron and coal) products 10.1% y/y, while vehicle exports are down 7.5% y/y and base metal exports 5.3% y/y. Machinery exports have risen a more moderate 5.9% y/y. The SARB also noted in the Q2 bulletin that recent strength in South Africa's trade position has been driven largely by mining and commodity exports rather than a broad-based recovery in manufactured exports. Manufacturing exports had already declined for a third consecutive quarter earlier this year (in Q1). At the same time, energy prices are distorting the import bill. The SARB said that much of the deterioration in the Q2 trade balance to ZAR 146bn surplus in Q2 (leading to net exports subtracting 1.1pps from GDP growth) could be attributed to higher crude oil and refined fuel imports. While the still-large merchandise trade surplus remains supportive of the external position, the data provide limited evidence of a sustained improvement in underlying export capacity as logistics, infrastructure and weak investment continue to constrain a broader recovery. | Foreign trade including BELN, ZAR mn | | Jan-Aug 2025 | Jan-Aug 2026 | % y/y | | Total exports,incl.: | 1,347,376 | 1,452,435 | 7.8% | | Agri/food | 186,834 | 181,825 | -2.7% | | Mineral products (iron, coal) | 327,545 | 360,682 | 10.1% | | Chemicals industry | 76,227 | 77,915 | 2.2% | | Precious metals/stones | 257,064 | 348,761 | 35.7% | | Base metals (copper, steel) | 114,704 | 108,597 | -5.3% | | Machinery | 95,240 | 100,866 | 5.9% | | Vehicles, transport | 188,476 | 174,354 | -7.5% | | | | | | Totalimports,incl.: | 1,251,282 | 1,302,941 | 4.1% | | Agri/food | 93,378 | 89,029 | -4.7% | | Mineral products (oil) | 229,634 | 277,977 | 21.1% | | Chemicals industry | 135,060 | 135,859 | 0.6% | | Base metals (steel) | 64,438 | 65,551 | 1.7% | | Machinery | 282,369 | 288,407 | 2.1% | | Vehicles, transport | 117,985 | 136,124 | 15.4% | | Original equipment components | 106,907 | 98,475 | -7.9% | | | | | | BALANCE | 96,094 | 149,494 | 55.6% | | | | |
| | Note: BELN = Botswana, Eswatini, Lesotho, Namibia | | Source: SARS |
|
|
|
|
| | Main budget deficit narrows to 2.3% of GDP Apr-Aug as revenue outpaces spending |
|
| South Africa | Sep 30, 16:58 |
|
- Revenue growth is driving the improvement, rising 9.5% y/y against 4.6% expenditure growth
- Execution so far remains consistent with the full-year deficit target of 3.7% of GDP
- Income taxes and VAT are leading the revenue gains, offsetting weaker fuel-levy receipts
- Debt service costs remain a major structural constraint despite the better fiscal outturn
The main budget deficit reached ZAR 188.8bn, or around 2.3% of GDP, in Apr-Aug, narrower than ZAR 215.2bn, or 2.8% of GDP, over the same period last year. The improvement extends the stronger fiscal performance seen at the end of 2025/26 and is being driven mainly by revenue, although expenditure growth has also remained relatively contained. Treasury targets a full-year main budget deficit of ZAR 301.2bn, or 3.7% of GDP, down from 4.5% in 2025/26. Execution through the first five months remains consistent with that target, provided the current revenue strength is sustained. 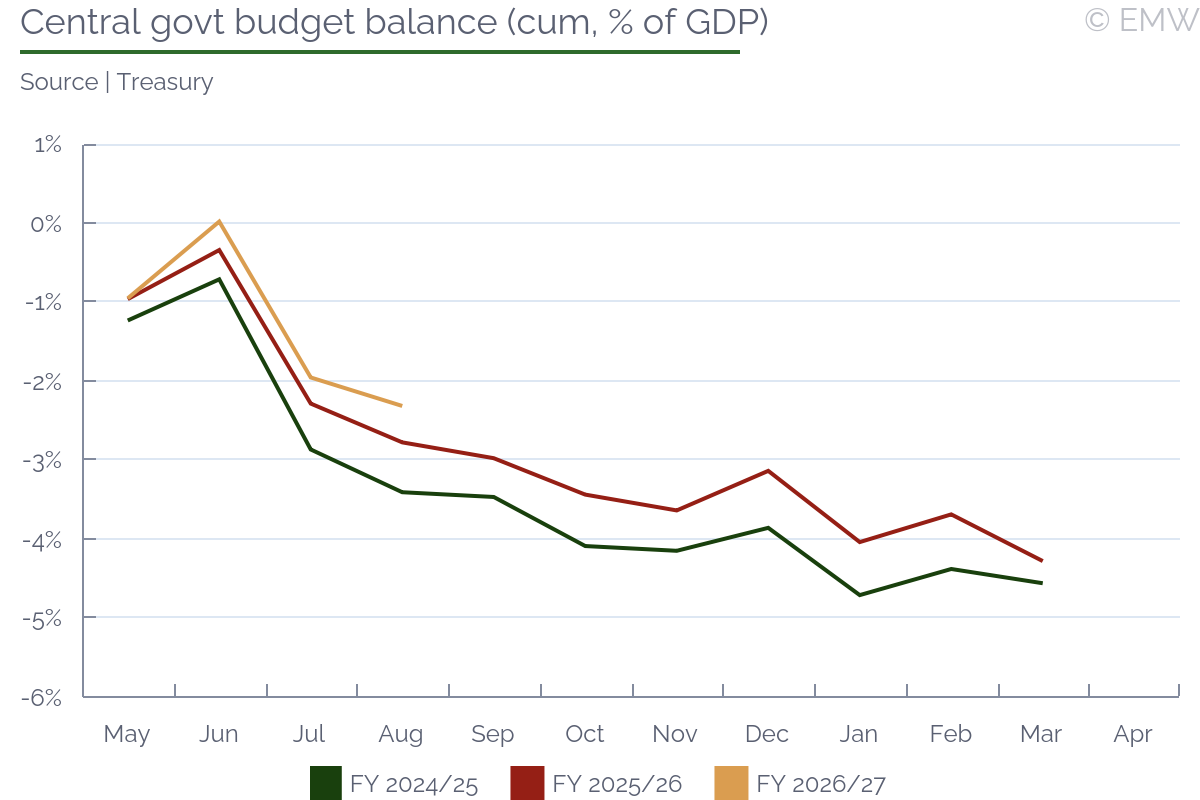 Revenue increased 9.5% y/y to ZAR 812.3bn in Apr-Aug, roughly twice the 4.6% y/y increase in expenditure to ZAR 1,001bn. This allowed the cumulative fiscal position to improve despite the normal seasonal deterioration in July, when the monthly deficit reached ZAR 161.6bn. August was also stronger than a year earlier, with the monthly deficit narrowing to ZAR 29.1bn from ZAR 38.3bn. Debt service costs, however, remained elevated at ZAR 159.9bn, broadly unchanged from the same period last year. The revenue improvement is concentrated in the major tax categories. Taxes on income and profits rose 12.5% y/y, supported by PIT growth of 8.4% y/y and particularly strong CIT receipts, which increased almost 23% y/y. Net VAT collections rose 9.1% y/y, despite higher refunds absorbing part of the increase in domestic and import VAT. These gains more than offset the decline in fuel-levy receipts to ZAR 21.2bn from ZAR 39.4bn, reflecting the partial tax relief, leaving the underlying tax take clearly stronger than a year earlier. On the financing side, the gross borrowing requirement declined to ZAR 197.0bn from ZAR 238.4bn a year earlier, consistent with the smaller cumulative deficit. Domestic long-term borrowing remained the main source of funding, while the GFECRA transfer should be viewed separately as a balance-sheet transaction rather than budget revenue. |
|
|
|
| Uganda |
|
| Government sells T-bills slightly above target again |
|
| Uganda | Oct 01, 06:52 |
|
- Govt sells UGX 357bn, exceeding UGX 350bn target
- Yield on 91-day T-bill falls by 5bps, but yields on other maturities rise 50-75bps
- Securities issued this FY so far reach 26% of full-year plan
The government sold UGX 357bn T-bills at the auction held by the Bank of Uganda on Sep 30, exceeding the UGX 350bn target for a sixth consecutive auction. The bids totalled UGX 574bn, translating into a subscription rate of 1.6x, down from 2.3x at the previous auction on Sep 2. This signalled easing demand, which could be due to two bond auctions held this month, the last just a week ago, selling UGX 1.2tn securities. The yields on the 91-day T-bill decreased by 5bps but the yields on the 182-day and 364-day tenors rose by 50-75bps. The last two treasury auctions indicate some emerging upward pressure on yields amid rising inflation and a weakening shilling. With this auction, the total issuance of treasuries this fiscal year (2026/27) reached UGX 6.8tn, equivalent to 26% of the borrowing plan for the year, which is UGX 25.9tn. | T-bill auction results | | Sep 30 | | 91-day | 182-day | 364-day | | Offer (UGX bn) | 15.00 | 35.00 | 300.00 | | Bids (UGX bn) | 61.18 | 64.68 | 447.80 | | Allocated (UGX bn) | 26.05 | 19.93 | 310.80 | | Money market yield | 9.699 | 10.751 | 11.501 | | Effective yield at cut-off price, % | 10.06 | 11.04 | 11.502 | | Subscription ratio | 4.08 | 1.85 | 1.49 |
| | Source: Bank of Uganda |
|
|
|
|
| Coffee export value falls by 10.3% y/y in August |
|
| Uganda | Sep 30, 17:11 |
|
- Export volume drops by 13.6% y/y and comes below monthly projection
- Average coffee price rises for first time in eight months due to weather risks
- Coffee likely to remain a drag on overall exports in August but impact to be offset by higher gold exports
Coffee exports fell for a sixth consecutive month, according to data from the Uganda Coffee Development Authority (UCDA). The volume of coffee exports fell by 13.6% y/y to 737,766 60kg bags, which is below the UCDA projection for the month which was 850,000 bags. For September, the projection is 700,000 bags, as the main harvest in Greater Masaka and the Southwestern regions has ended. The value of coffee exports fell too, by 10.3% y/y to USD 181.7mn, but the rate of decline eased as the average coffee price rose by 3.8% y/y, the first annual rise in eight months. The increase was partly due to the low base a year earlier but also due to the El Nino-related concerns and tight Arabica supplies which supported prices at the beginning of September. Prices have since retreated on the favourable weather and production outlook in Brazil. We note that the foreign trade statistics for August are yet to be released but the coffee numbers suggest the commodity will remain a downward factor. Total exports still grew in July, albeit at a slower pace as the drop in coffee exports was offset by the increase in gold sales. Coffee is a key agricultural export commodity for the country accounting for about 15% of total exports. |
|
|
|
| | Inflation accelerates to 4.6% y/y in September on higher food prices |
|
| Uganda | Sep 30, 16:53 |
|
- Main upward contributions come from food and fuel prices
- Core inflation picks up to 3.7% y/y, signalling rise in underlying price pressures
- Central bank will likely leave rates on hold again in November unless inflation outlook changes materially by then
The headline inflation rate continued rising in September, to 4.6% y/y from 4.1% y/y in August, the statistical office said. The acceleration was mainly due to faster growth in food and energy prices. Food inflation picked up to 4.7% y/y in September from 3.6% y/y in August, largely driven by higher prices of some grains and meat, potatoes and beans. Transport inflation rose to 9.8% y/y from 9.4% as a result of higher prices of petrol and diesel, as well as new vehicles. At the same time, housing and utilities inflation slowed mainly due to easing growth in charcoal and cement prices. 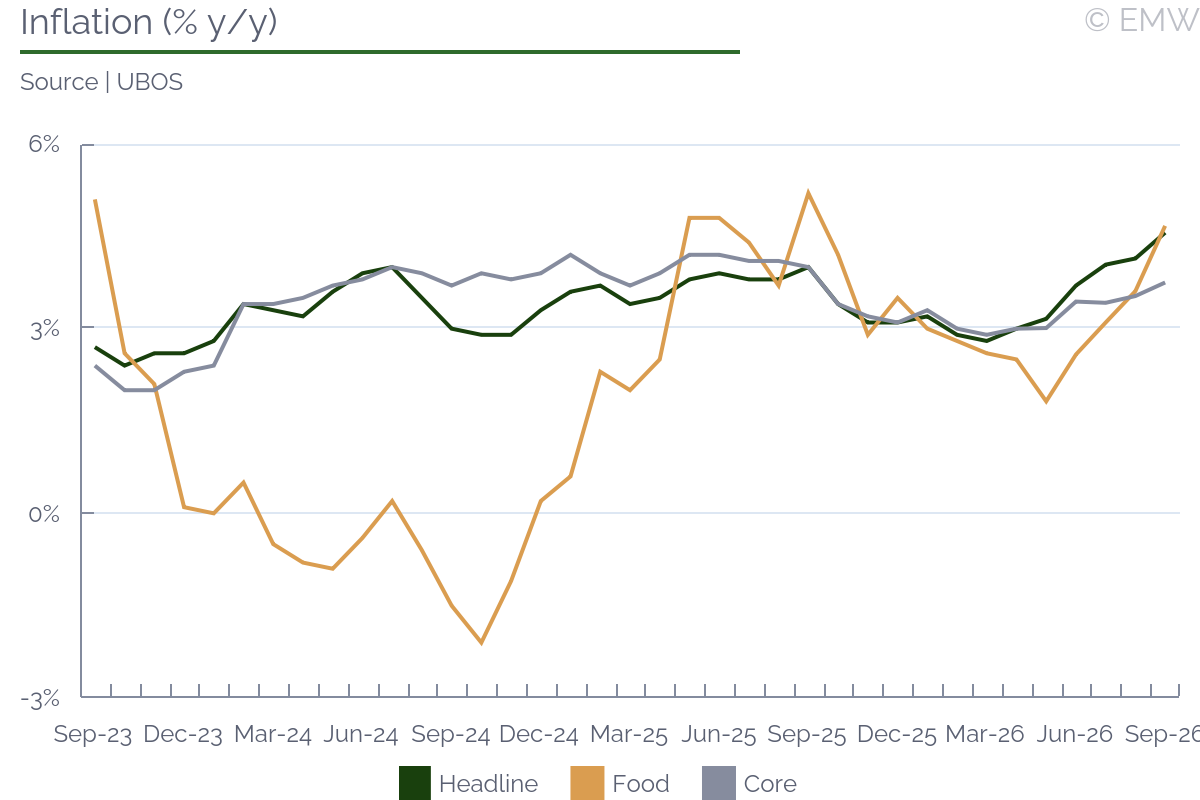 Core inflation picked up to 3.7% y/y in September from 3.5% y/y in August, signalling rising underlying price pressures. Unless there is a more pronounced and entrenched increase in the inflation rate, the central bank will likely keep the policy interest rate unchanged at the next meeting in November. At the last MPC meeting in August, it saw the inflation outlook as improving thanks to the retreat of oil prices back then and the stabilisation of the shilling, and forecast core inflation in the 4.0-4.5% range over the next 12 months, down from 5.0-5.3% projected at the time of the previous MPC meeting in May. It also forecast headline inflation in the 5.5-6.0% range over the next 12 months. The outlook has since worsened a bit but we expect the policy rate to be left at 9.75% as the balance of risks for inflation and growth remains largely the same. | CPI breakdown (% y/y change) | | Weight | Jun-26 | Jul-26 | Aug-26 | Sep-26 | | Food and soft drinks | 27.10 | 2.6 | 3.1 | 3.6 | 4.7 | | Alcoholic beverages & tobacco | 3.90 | 0.6 | 1.0 | 1.7 | 1.7 | | Clothing & footwear | 7.00 | 1.2 | 1.3 | 1.1 | 1.3 | | Housing & utilities | 10.40 | 4.9 | 6.7 | 6.4 | 6.2 | | Household equpiment & maintenance | 4.80 | 2.6 | 2.9 | 2.7 | 3.3 | | Health | 4.70 | 1.8 | 1.6 | 1.5 | 1.7 | | Transport | 10.50 | 8.8 | 9.3 | 9.4 | 9.8 | | Communication | 4.40 | 1.1 | 1.0 | 3.3 | 3.2 | | Recreation and culture | 5.00 | 0.9 | 0.7 | 0.7 | 1.6 | | Education | 5.80 | 5.7 | 5.7 | 5.7 | 5.7 | | Hotels & restaurants | 8.70 | 3.3 | 3.2 | 2.5 | 2.3 | | Insurance and financial services | 2.30 | 12.6 | 10.1 | 10.1 | 10.1 | | Personal care, social protection and miscellaneous | 5.40 | 1.9 | 1.8 | 1.3 | 1.6 | | All items | 100.0 | 3.7 | 4.0 | 4.1 | 4.6 | | | | | | | | Core | 83.96 | 3.4 | 3.4 | 3.5 | 3.7 | | Food crops and related items | 9.51 | 0.0 | 1.6 | 2.1 | 4.5 | | Energy, fuel and utilities | 6.53 | 11.9 | 14.9 | 14.3 | 14.5 |
| | Source: UBOS |
|
|
|
|
| Zambia |
|
|
| Zambia | Oct 01, 08:58 |
|
We may exceed 1,000MW solar target this year - Govt (News Diggers) Foreign firms using Zambians to benefit from Local Content law (News Diggers) Catholic Bishops concerned over "arbitrary arrests" (News Diggers) We'll reform laws that stand in the way of business - HH (News Diggers) Aviation authority urges Zambia Airways to introduce flights to Kasama (Zambia Monitor) ITC, Access Bank partner to support small businesses across 14 African countries (Zambia Monitor) |
|
|
|
| Energy regulator raises fuel prices sharply as tax relief expires |
|
| Zambia | Oct 01, 08:56 |
|
- Petrol rises 24.40% m/m, diesel 23.86%, kerosene 10.14% and Jet A-1 10.94% following excise duty reinstatement
- International petrol prices increased 15.86%, diesel 6.60% and kerosene/Jet A-1 14.93%, while the kwacha depreciated 2.5% to ZMW 19.76/USD
- Excise duty reinstated from Oct 1 after the Sep 30 expiry of fuel tax relief, while VAT reinstatement is delayed to Dec 1
- Sharp pump-price increases are likely to reverse some recent transport-cost relief, with transport inflation already at 5.8% y/y in September
The Energy Regulation Board (ERB) revised national uniform pump prices for the October pricing window, effective midnight Oct 1, marking a sharp reversal from the reductions recorded earlier in the year. Petrol rose to ZMW 31.46/litre (+24.40%), diesel to ZMW 33.27/litre (+23.86%), kerosene to ZMW 29.76/litre (+10.14%) and Jet A-1 to ZMW 31.85/litre (+10.94%). The increases followed sustained geopolitical tensions in the Middle East, which pushed the average international price of petrol from USD 104.94/bbl to USD 121.58/bbl, diesel from USD 150.92/bbl to USD 160.88/bbl and kerosene/Jet A-1 from USD 125.30/bbl to USD 144.00/bbl. The kwacha also depreciated from ZMW 19.28/USD to ZMW 19.76/USD, further increasing domestic import costs. The latest increases were also driven by the expiry of the government's fuel tax-relief measures at end-Sep which had been suspended for several months to cushion consumers from the Middle East shock. Excise duty was reinstated from Oct 1, while VAT will be reinstated on Dec 1, meaning the October adjustment reflects higher international petroleum prices and exchange-rate pressures alongside the partial withdrawal of fiscal support. The effect was particularly pronounced for petrol and diesel, whose pump prices increased by more than the corresponding percentage rises in international benchmarks. ERB said its price-smoothening measures and the temporary suspension of excise duty and VAT had previously moderated the impact of global price and exchange-rate movements, while the latest adjustment was necessary to safeguard security of supply. The sharp increase is likely to place renewed pressure on domestic transport and production costs after the recent decline in fuel prices. Zambia's annual transport inflation had already risen to 5.8% y/y in September from 5.3% in August, while headline inflation eased marginally to 6.1% from 6.2%. With transport accounting for about 5.8% of the CPI basket, higher petrol and diesel prices should feed into passenger transport, freight and distribution costs, while higher diesel costs could increase operating expenses across mining, agriculture and other fuel-intensive sectors. The extent of pass-through will depend partly on the exchange rate and how much of the higher costs businesses absorb rather than transfer to consumers. With geopolitical tensions continuing to elevate global energy-market risks, fuel costs are likely to remain an important source of inflation and operating-cost pressure heading into Q4. | Fuel price changes (ZMW/litre) | | Current (ZMW) | New (ZMW) | Absolute variance | % change | | Petrol | 25.29 | 31.46 | 6.17 | 24.40 | | Diesel | 26.86 | 33.27 | 6.41 | 23.86 | | Kerosene | 27.02 | 29.76 | 2.75 | 10.14 | | Jet A-1 | 28.71 | 31.85 | 3.14 | 10.94 |
| | Source: ERB |
|
|
|
|
| | Private sector credit growth accelerates to 12.9% y/y in Q2 |
|
| Zambia | Sep 30, 16:19 |
|
- Private sector credit growth accelerates as demand for debt refinancing and working capital increases
- Public sector credit also grows at faster pace, mainly due to liquidity management operation linked to 2053 Eurobond buyback
- Credit conditions improve as interest rates decline, although commercial banks' lending rate remains elevated
Domestic credit to the private sector grew by 12.9% y/y in June, picking up from 8.1% y/y in March, the Bank of Zambia said in its latest MPC presentation. It attributed the accelerated growth to debt refinancing and working capital requirements. Overall domestic credit also expanded at a faster pace of 14.4% y/y in June from 7.5% y/y in March, while public sector credit growth rose to 16.0% from 6.6%, mainly due to the Liquidity Management Operation relating to the 2053 Eurobond buyback. 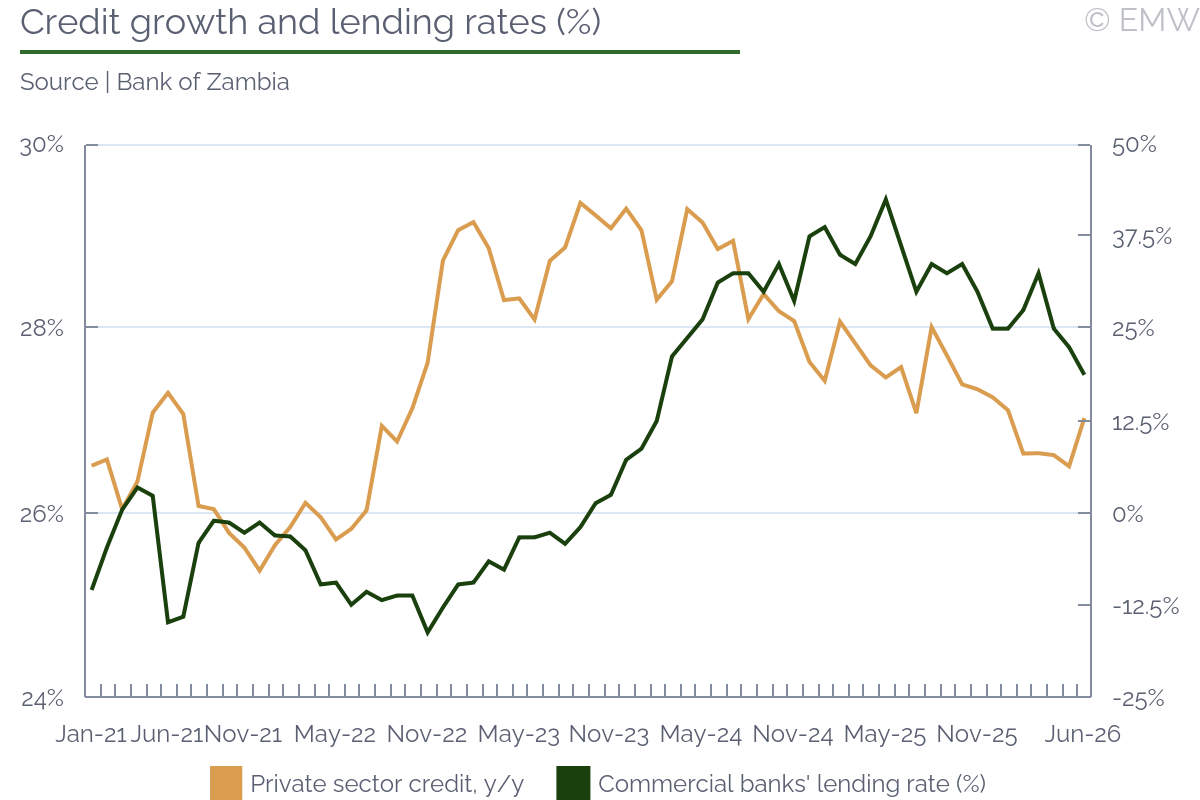 While there has been a recovery in private sector credit growth in recent months, borrowing costs remain elevated, with the commercial banks' average lending rate at 27.3% in August, although this was down from 28.2% in February. The Bank of Zambia noted that nominal interest rates generally declined following reductions in the Policy Rate, supported by improved liquidity conditions. The latest 250bps cut in the Policy Rate to 10.75% should further ease financing conditions and support private sector credit growth, although the transmission to commercial lending rates is likely to be gradual. |
|
|
|
| Gross international reserves rebound to USD 6bn in July |
|
| Zambia | Sep 30, 14:48 |
|
- GIR fell to USD 5.8bn at end-Jun from USD 6.2bn at end-Mar after reaching USD 6.5bn at end-May, before rebounding in July
- Import cover eased to 4.4 months in June from 5.2 months at end-Mar, before recovering to 4.5 months in July
- July reserve rebound was supported by mining taxes, project inflows, Government non-tax receipts, interest on reserves and monetary gold purchases
- June decline reflected the USD 514.8mn bond buyback operation and USD 453.4mn in external debt service
Zambia's gross international reserves (GIR) rose to USD 6.0bn in July, up from USD 5.8bn at end-June, according to the Bank of Zambia (BoZ) Governor's MPC decision presentation dated Sep 30. The presentation showed that reserves had earlier climbed to USD 6.5bn at end-May before easing in June. July's stock was equivalent to 4.5 months of import cover, up from 4.4 months in June but below the 5.2 months recorded at end-March, with the June decline reflecting the USD 514.8mn bond buyback operation and USD 453.4mn in external debt service. 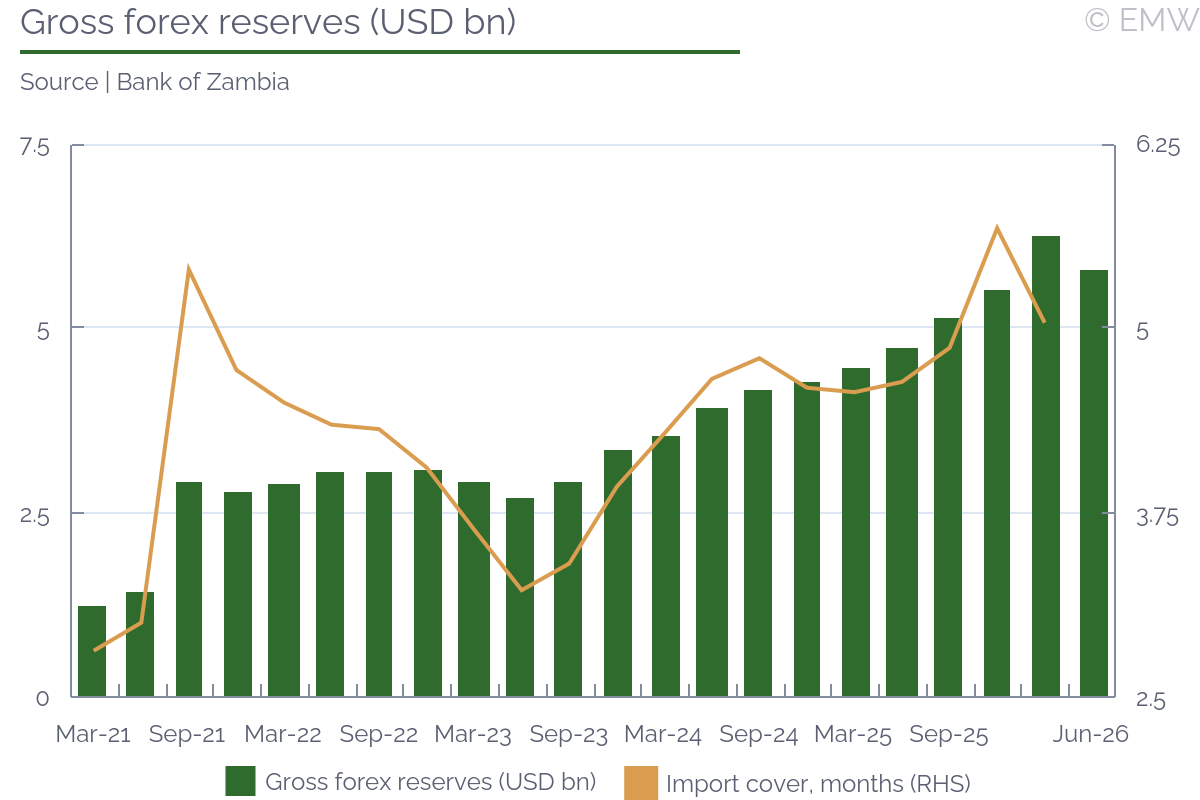 The Bank also provided USD 72.0mn in market support during Q2 to manage exchange-rate volatility, while remaining a net buyer of foreign exchange, mostly through taxes remitted by mining companies. Mining-sector foreign exchange liquidity supplied to the market rose to USD 1.2bn in Q2 from USD 0.9bn in Q1, as net foreign exchange sales by mining companies increased to USD 774.0mn from USD 626.0mn and tax remittances to the BoZ rose to USD 398.7mn from USD 289.7mn. However, interbank turnover declined to USD 375.7mn from USD 396.5mn, while the market shifted to net demand of USD 119.1mn from net supply of USD 230.2mn, as foreign financial institution supply fell to USD 132.1mn from USD 542.3mn following the exhaustion of their allocation in the primary Government securities market. In July, reserves recovered on mining taxes of USD 88.3mn, project inflows of USD 14.5mn, Government non-tax receipts of USD 13.6mn, interest on reserves of USD 13.0mn and monetary gold purchases of USD 8.5mn. The Bank bought 62.21kg of gold worth USD 8.2mn in July, taking total gold holdings to 3,620.43kg with a market value of USD 468.7mn. As of Sep 29, the average gold price stood at USD 4,160.00 per ounce. |
|
|
|
|
|