| BCRA to keep policy rate and crawling peg moving closely in line with m/m CPI |
| BCB directors vow caution as inflation picks up, but one more cut still likely |
| Rising inflation pressure likely to force CNB to raise policy rate again |
| Regional uncertainty may force MPC to hold rates again in October |
| MPC to hold in October, but rate cuts are still possible in Nov-Dec |
| RBI to pre-emptively hike rate by 25bps in October |
| BI wants to stand pat, but may raise key rate in October/November |
| CB holds rate without forward guidance, governor defends current MPR position |
| MPC cuts main policy rate by 350bps to 23% |
| SBP looks through oil shock, but October hike remains possible |
| Hike by 25bps, hold decision both possible in October |
| MPC still set to hold in October, but may discuss scenario for rate hikes |
| CBT likely to cut 100bps but to remain cautious amid risks |
| BCCh to hold at 4.50% on Sep 8 and likely through 2026 as risks stay balanced |
| BanRep likely to hold rates on Sep 30; politics, not data, drive the call |
| BCCR to decide on MPR amid persistent deflation and high external risks |
| Inflation supports continuation of monetary easing so far |
| NBK cuts base rate by 50bps, sees limited scope for further easing |
| BOK seems likely to hold rates steady in October, after rare back-to-back hikes |
| BNM to keep policy rate unchanged in November, but hike remains possible in 2027 |
| MPC likely to hold at 9.25% as easing inflation offsets energy, climate risks |
| NBR to consider rate cuts no sooner than early 2027 as inflation stays high |
| Inflation and fiscal uncertainty remain key arguments against further rate cuts |
| NBS to hold rate at 5.75% on energy risks, expected low-base-led inflation spurt |
| October fuel shock worsens inflation outlook, pressuring MPC response |
| CBSL to hold rates in September despite inflation edging higher |
| BOT’s MPC likely to maintain policy rate at 1.00% in October |
| BCT likely to hold at 7.00% in September but oil shock raises policy risks |
| Central bank under pressure to increase key rate again |
| BCRA to keep policy rate and crawling peg moving closely in line with m/m CPI |
- BCRA to raise quickly next time CPI inflation comes at 7.0% m/m or close
- BCRA needs to keep monthly effective rate and crawling peg closely in step with inflation to reduce export delay and portfolio dollarization incentives
- Unsustainable deficit+debt dynamics keep BCRA from pursuing positive real rates or depreciation
- BCRA can only passively respond to rising inflation, this status quo likely remains until regime change
The BCRA's future monetary policy rate decisions will remain bounded by the evolution of effective inflation, expected inflation for the short-term, and the interest rate limitations the central bank faces if it is to keep the official real exchange rate steady in the coming year, which is something the bank is paying close attention to. The BCRA hiked its benchmark 28-day bill rate by 300bps to 78.0% in mid-March to accommodate the monthly effective rate at 6.5%, up from 6.3%, in what was the first move for the rate since last September. The decision was taken following the release of a surprisingly high 6.6% m/m CPI inflation print for February and with market expectations of a similar reading for March. The BCRA is likely to raise another 200bps or 300bps if the CPI reading for March is close 7.0% m/m, unless high-frequency price trackers show a deceleration in early April.
Monetary policy has been passive for most of the past three years, sitting under the weight of massive fiscal dominance and past policy mistakes, and there are no prospects for this to change until the end of this government in December. To put it in short, the BCRA needs to keep its monthly effective benchmark rate and the official exchange rate crawling peg moving right in step with CPI inflation, and it doesn't have room to deviate much or for too long, which means monetary policy should be fairly predictable this year. The BCRA has slightly more room to delay rate cuts if inflation declines than it has room to delay rate hikes if inflation rises, but it seems very unlikely that inflation will decline this year anyway.
The dangerous inflation spiral and the massive real exchange rate appreciation that took place in 2021-22 put pressure on the BCRA to raise nominal interest rates and push the pace on the crawling peg when inflation rises. If the crawling peg lags versus inflation, the government would be increasing the incentives for exporters to withhold sales abroad and wait for an inevitable devaluation, while also reducing competitiveness (most exporters are forced to convert their FX income into local currency). This would add to an FX market crisis that has the government burning through its low FX reserves. However, if the nominal crawling peg is to move faster, interest rates also need to rise in step to avoid creating incentives to delay exports. Interest rates that at least match inflation are also key to discourage portfolio dollarization through parallel exchange rates, which are an increasingly important benchmark for price-setting practices.
The BCRA also needs to be careful of not going too high with real rates because it would contribute to the explosiveness of public debt dynamics and inflation. With the government running a fiscal deficit of more than 4.0% of GDP every year despite having virtually no access to market financing, the deficit has been covered by a mix of inflation tax and central bank balance sheet deterioration. The higher the real interest rate goes, the faster the deterioration of the central bank's balance sheet and the growth of the federal government's short-term debt. However, the evolution of market financing for the government and the BCRA's remunerated liabilities suggests that the room to get financing through these avenues is pretty much closed now, which only leaves inflation tax as an option. In this scenario, nominal interest rate hikes are inflationary as long as there are no drivers to increase the private sector's willingness to finance the government.
| Ask the editor | Back to contents |
| BCB directors vow caution as inflation picks up, but one more cut still likely |
- Copom meeting: Nov 3-4, 2026
- Current policy rate: 13.75%
- EmergingMarketWatch forecast: 25-bp cut (to 13.50%)
Brazil's IPCA-15 inflation rose to 4.47% y/y to mid-September in 12-month cumulative terms, approaching the 4.50% upper limit of the +/- 1.50-pp fluctuation band around the 3.00% target, pressured up by higher housing, transport, and food prices. The increase came after two consecutive months of deceleration, taking the cumulative print to just below the upper limit sooner than the BCB had expected. The acceleration is, however, broadly aligned with the Copom's forecast that inflation will increase through year-end and that it will go above that limit for two consecutive quarters, which would require a letter from the BCB governor to the finance minister at some point in Q1 2027. Although the inflationary outlook is challenging, the Copom has highlighted the economic deceleration in recent months as proof of monetary tightening transmission, which is still likely to support another 25-bp Selic cut to 13.50% at its next policy sitting on Nov 3-4.
BCB Monetary Policy Director Nilton David said on Sep 23 that monetary policy must be conducted cautiously amid the elevated uncertainties, though remain smooth and predictable. He also reaffirmed that the ongoing cycle is one of calibration rather than of easing, strengthening our expectation that the cycle is likely to proceed gradually. BCB Director of International Affairs and Corporate Risk Management Paulo Picchetti said the next day that the Selic rate will remain at a restrictive level to ensure inflation converges back to the target midpoint.
Another data point that is likely to bring about a gradual cycle is the robust labor market. Unemployment held at 5.3% in the rolling quarter ended in August. Still, the Copom has said of late that, despite the labour market's resilience and real wage gains that exceed productivity, employment growth shows signs of decelerating amid its tight monetary policy. In addition, the Copom noted the deceleration in the credit market in its latest minutes, especially in long-term unsecured loans, while directed lending continued to expand. All of this would tend to point to caution, but at the same time the BCB seems to feel comfortable enough to continue cutting by 25bps.
Additional demand-driven inflationary pressures, however, could reduce the overall magnitude of the coming rate cuts. The government's recent measures to ban online betting platforms and its new debt-relief program are likely to increase household disposable income, raising the likelihood that the Copom will perceive a greater risk of inflationary pressure from demand, which the Copom has noted could weaken traditional monetary policy transmission channels. However, the impact of these measures is unlikely to be reflected by November.
Overall, Brazil's inflationary outlook remains challenging, with the inflation balance of risks tilted to the upside as the government continues to implement measures to sustain demand that lead to additional inflationary pressure. At the same time, economic deceleration and easing signals from the labor and credit markets suggest additional room for the Copom to continue its ongoing calibration cycle at a gradual and slow pace. Thus, we expect another 25-bp Selic cut to 13.50% at the Nov 3-4 meeting, which will come only a few days after the presidential election runoff on Oct 25. Potential FX volatility and an increase in demand from government measures are more likely to affect policy decisions after that date.
| Copom structure and latest voting results | ||||||||||||||||||||||||||||||||||||||||||||||||||
| ||||||||||||||||||||||||||||||||||||||||||||||||||
| Source: BCB |
| Ask the editor | Back to contents |
| Rising inflation pressure likely to force CNB to raise policy rate again |
- Next MPC meeting: Nov 5, 2026
- Current policy rate: 3.75%
- EmergingMarketWatch forecast: 25bp hike
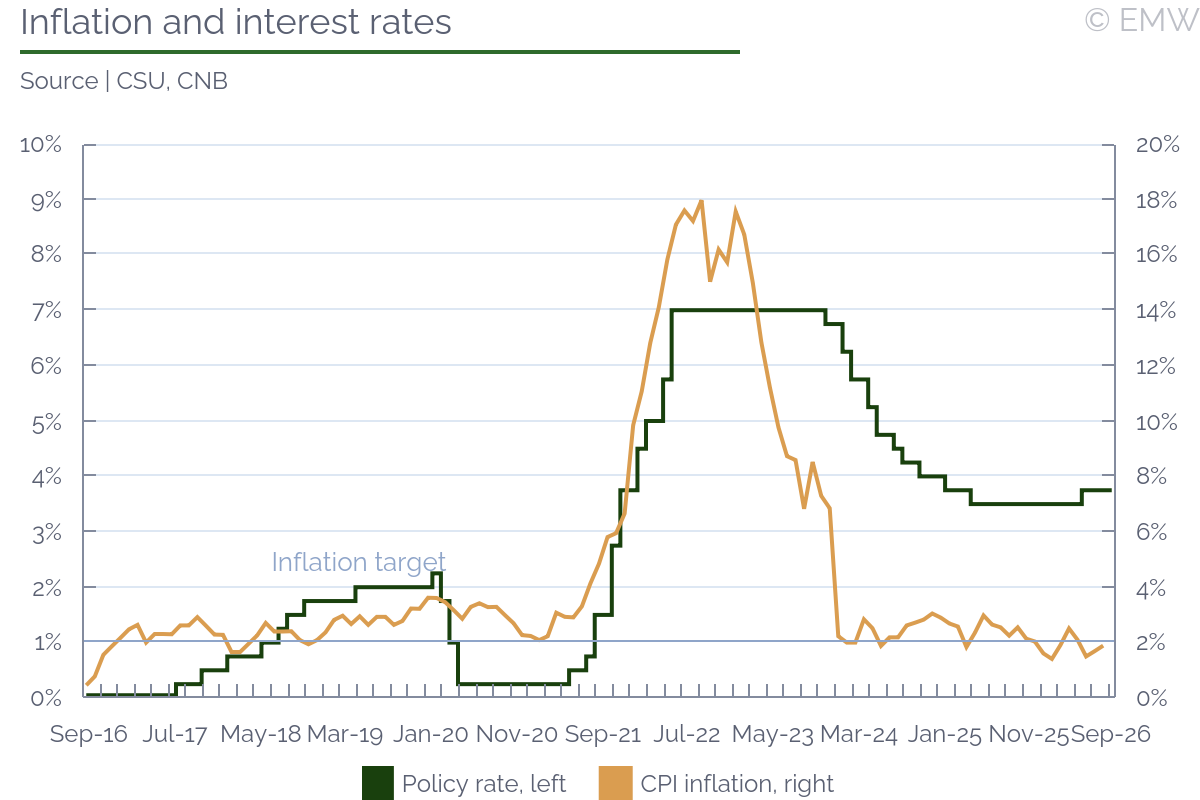
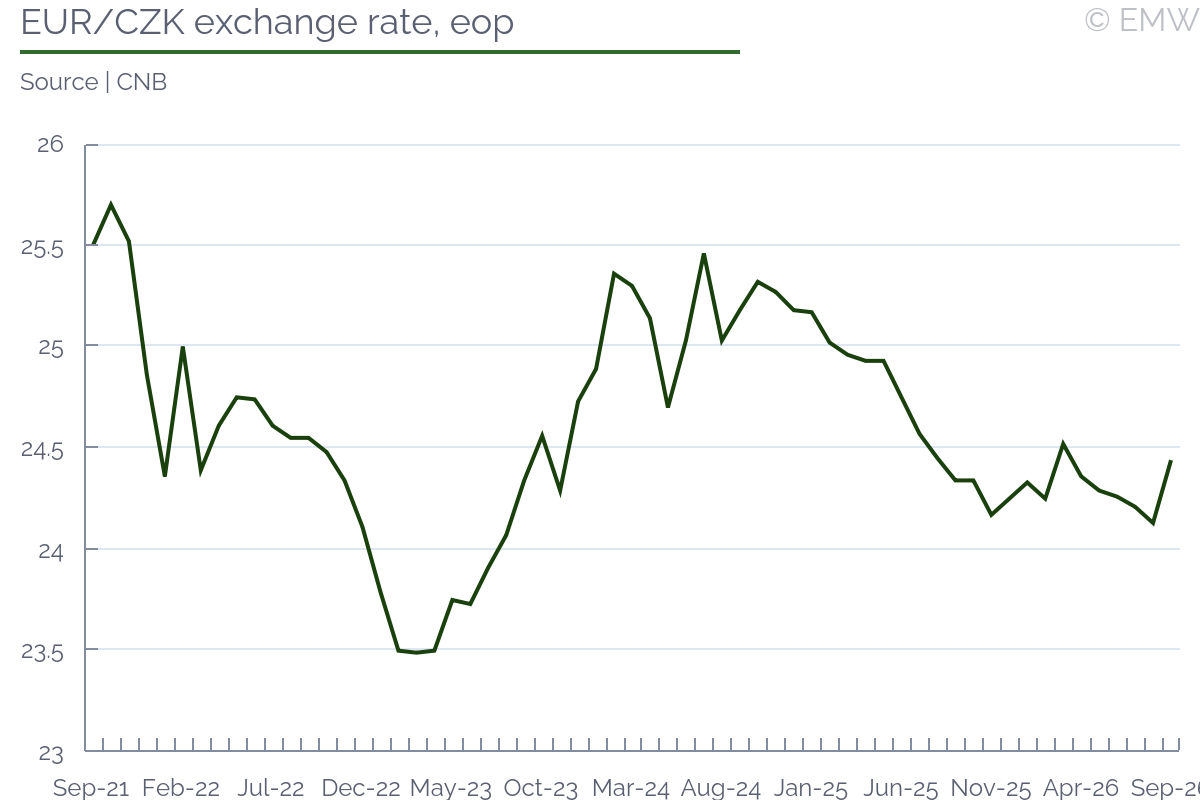
Rationale: The CNB board maintained its hawkish tone, but it took a somewhat harder stance on inflation risks after the MPC meeting on Sep 17 when it left the policy rate unchanged at 3.75%. Mounting inflation pressure is the main difference, and it appears almost inevitably that the CNB will need to tighten monetary policy further. The post-meeting statement said outright that the debate at the next MPC meeting on Nov 5 will be between holding interest rates and a rate hike, which is something the CNB doesn't communicate often. We saw some remarks from board members before the MPC meeting in September that suggested another rate hike is only a matter of time.
We are not entirely confident about the timing, and we could have a situation where the CNB pauses again in November but delivers a hike in December. However, we expect that inflation risks will increase enough to justify a hike as soon as the next MPC meeting. After all, the CNB has been arguing that it needs to be proactive, which was one of the justifications for the 25bp hike in June. This time around, we expect that inflation will start accelerating much more noticeably, and we believe it will start beating the CNB's projections. The combination of rising natural gas prices due to reduced supply and low European gas storage levels has already been fuelling a sharp increase. In turn, domestic energy suppliers have started to announce energy price hikes, and we expect more to come in Q4. Food prices, which have been mitigating inflation thus far, will likely reverse course soon, as this year's harvest was poor due to a heavy drought and hot weather.
On the policy front, the government has chosen this time to boost spending even further, effectively targeting a general government deficit of 3.5% of GDP in 2027 (2.8% of GDP is the ratio when the escape clause is applied). Wage growth in the public sector will be in the 5-9% range, and pensioners will get about a 9% bonus payment in 2027, even if a one-off one. All this will apply pressure on the labour market, which remains relatively tight, so the odds are nominal wages will keep rising at a robust rate. In a nutshell, the rest of 2026 and 2027 are shaping up to be a combination of a pro-inflationary external environment and pro-inflationary domestic policy. With that in mind, we don't see how the CNB could avoid more monetary tightening.
The only question is how far the CNB would go. Our base scenario suggests one more 25bp hike this year, and quite possibly another one in early 2027. However, any escalation of the current energy crisis will force the CNB to react faster, and at a greater magnitude. If natural gas prices reach levels similar to 2022, then we cannot rule out 50bp hikes or larger. Monetary policy in major economies will also provide some guidance, as we doubt the CNB will want the interest rate differential to close too much. We still consider market bets of four rate hikes in the next 12 months as excessive, but two hikes appear to be a smart bet, maybe even three if conflict escalation continues.
Further Reading:
CNB board statement from latest MPC meeting, Sep 17, 2026
Post-meeting press conference, Sep 17, 2026 (in Czech)
Q&A after the latest MPC meeting, Sep 17, 2026
Minutes from the latest MPC meeting, Sep 17, 2026
Monetary Policy Report, August 2026
Macroeconomic forecast, August 2026
Meeting with analysts, Aug 7, 2026
CNB board members' presentations, articles, interviews (Czech)
CNB board members' presentations, articles, interviews (English)
| Ask the editor | Back to contents |
| Regional uncertainty may force MPC to hold rates again in October |
- Next MPC meeting: Oct 29, 2026
- Current policy rate: 19.5%
- EmergingMarketWatch forecast: 18.5% - 19.5%
The next MPC meeting is on October 29, and we think the committee is more likely to hold rates instead of delivering a rate cut because of the elevated geopolitical uncertainty, high energy prices, and possible international food supply disruptions. Inflation is also driven by structural factors such as surging housing rents, persistent fiscal deficits, and infrastructure bottlenecks. Tighter monetary stances across advanced and emerging markets are also putting strain on Egypt's external account and its currency. While urban CPI inflation slowed unexpectedly to 14.5% y/y in August, we think that inflationary pressures, as evidenced by a higher core inflation rate, remain elevated and would warrant a more cautious approach because of supply-side risks. On the other hand, demand-side inflationary pressures have moderated and the MPC thinks they will remain limited in the short term.
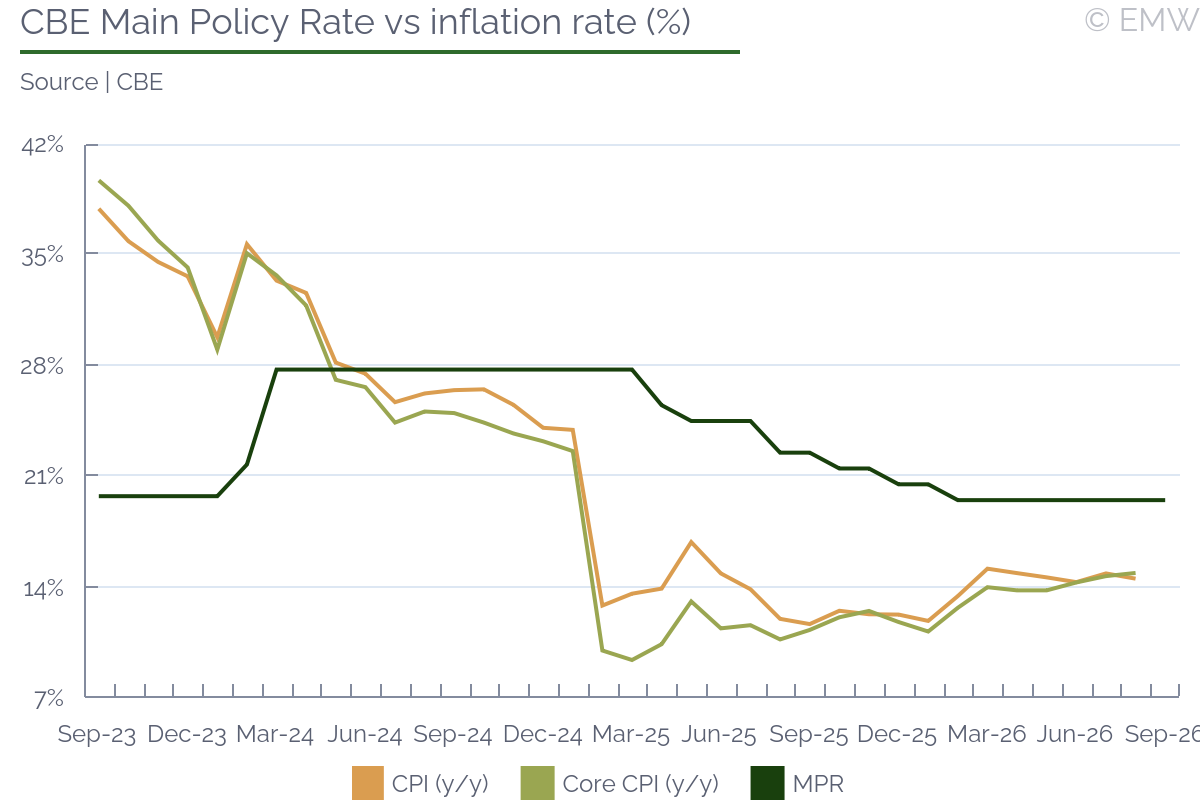
The central bank expects that annual inflation will stabilize in Q3, before gradually moderating and then converging to the 5-9% target range during H2 2027. However, the forecasted inflation trajectory remains subject to upside risks, including escalating regional hostilities and a higher-than-expected pass-through from fiscal consolidation measures.
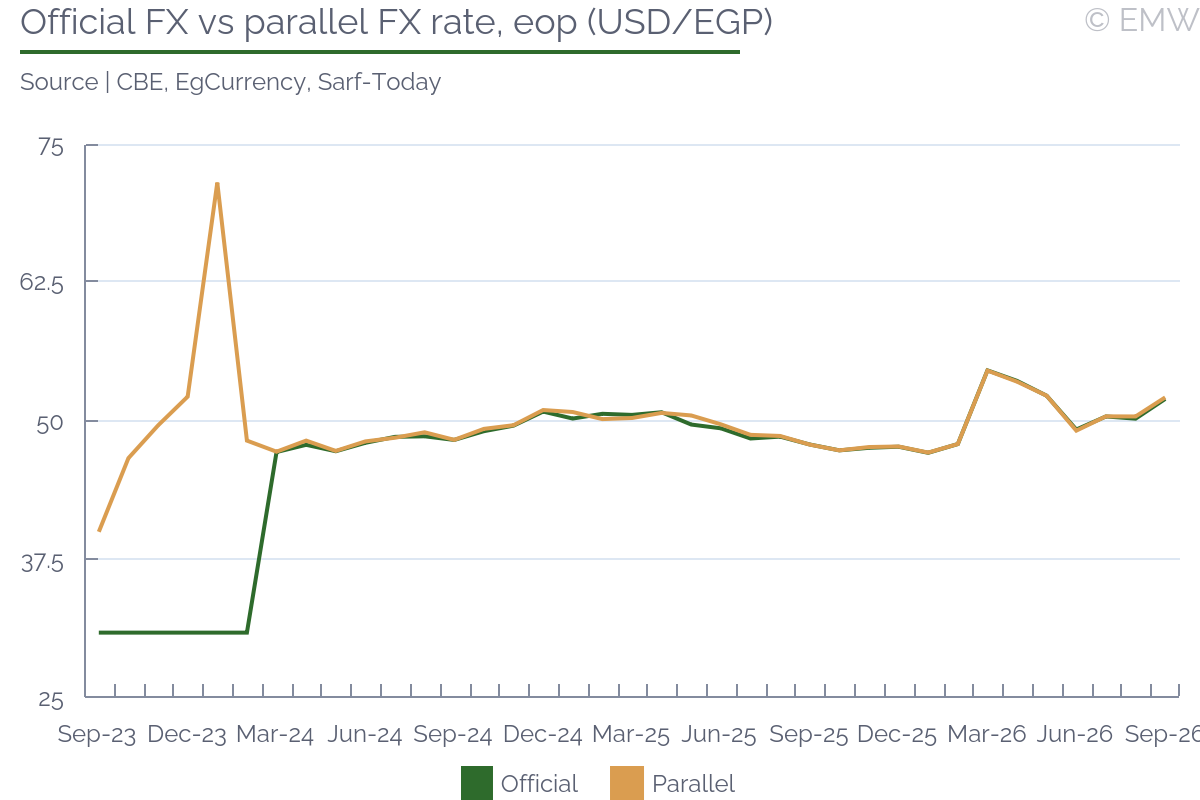
Overall, the global outlook remains vulnerable to escalating risks, particularly resurgent regional conflict, tighter financial conditions, and supply chain disruptions. Despite months of heightened uncertainty and energy shocks, Egypt appears stable and resilient to the ongoing Middle East crisis. This is not the first time the CBE has been confronted with capital flight triggered by a major external shock, but external financing support, an appropriate monetary stance, and government commitment to fiscal consolidation have all helped Egypt navigate the current crisis. Importantly, the CBE has refrained from intervening in the FX market to shore up the pound, consistent with its commitment to a flexible FX regime and the broader policy framework agreed with the IMF. The pound has weakened in recent weeks, reflecting the surge in energy prices, while we think that portfolio outflows and costly summer gas imports were partly offset by robust remittances, stable tourism revenues, and growing Suez Canal earnings.
| Ask the editor | Back to contents |
| MPC to hold in October, but rate cuts are still possible in Nov-Dec |
- Next MPC meeting: Oct 20, 2026
- Current policy rate: 5.50%
- EmergingMarketWatch forecast: Hold
- Rationale: NBH to wait for market reaction to mid-term fiscal framework before deciding on rates
The MPC is set to keep the policy rate on hold in October after the hold decision in September. The hold decision in September was based on the intensification of the global energy price risks, which were one of the reasons for the deterioration of the inflation outlook. The NBH revised its inflation forecast for 2027 significantly up with the September Inflation Report due to higher fuel prices and the government's hike of the excise tax on tobacco. Another important decision in September was the revision of the mid-term inflation target from 3.0% to 2.5% as of the beginning of 2028. The lowering of the target had been expected after a number of signals from key NBH officials and was justified by the need for gradual convergence to the ECB target in view of the government's ambition to fulfil the eurozone convergence criteria by 2030. The new mid-term target was expected to be reached in a sustainable manner in mid-2028, based on disciplined monetary policy, stable exchange rate and a decline in energy prices.
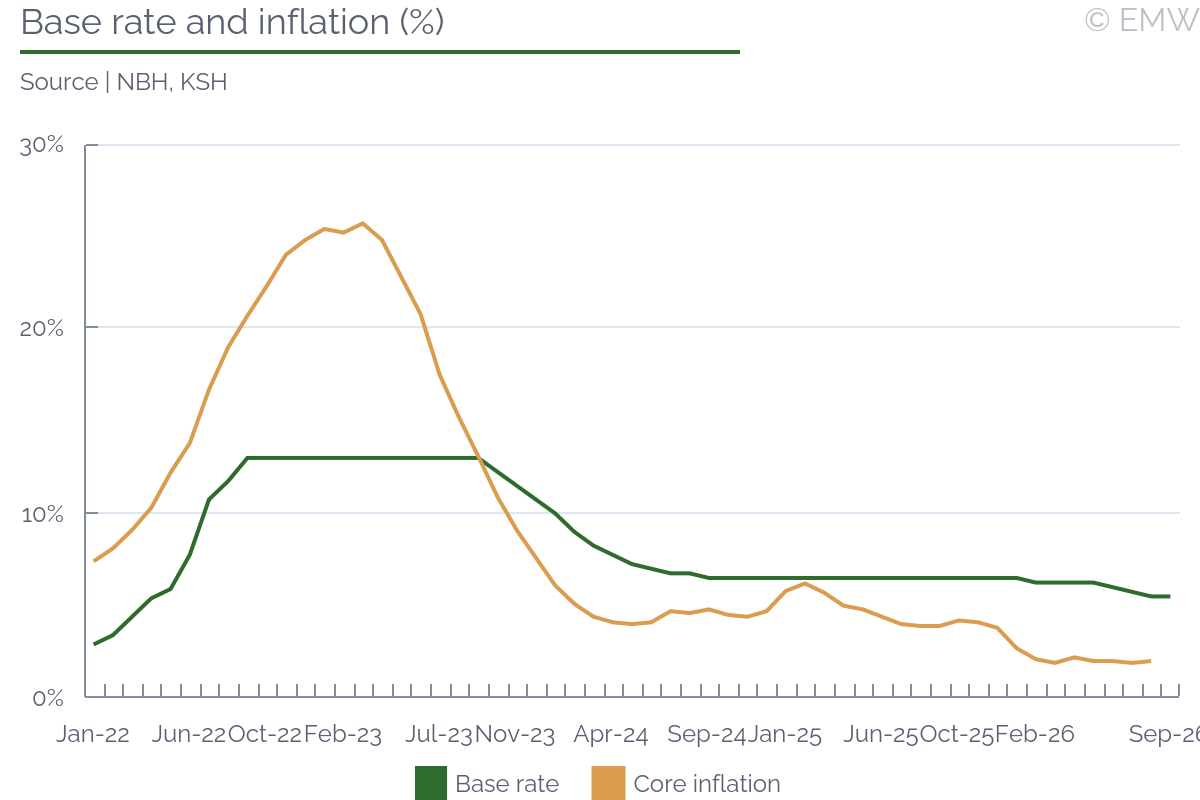
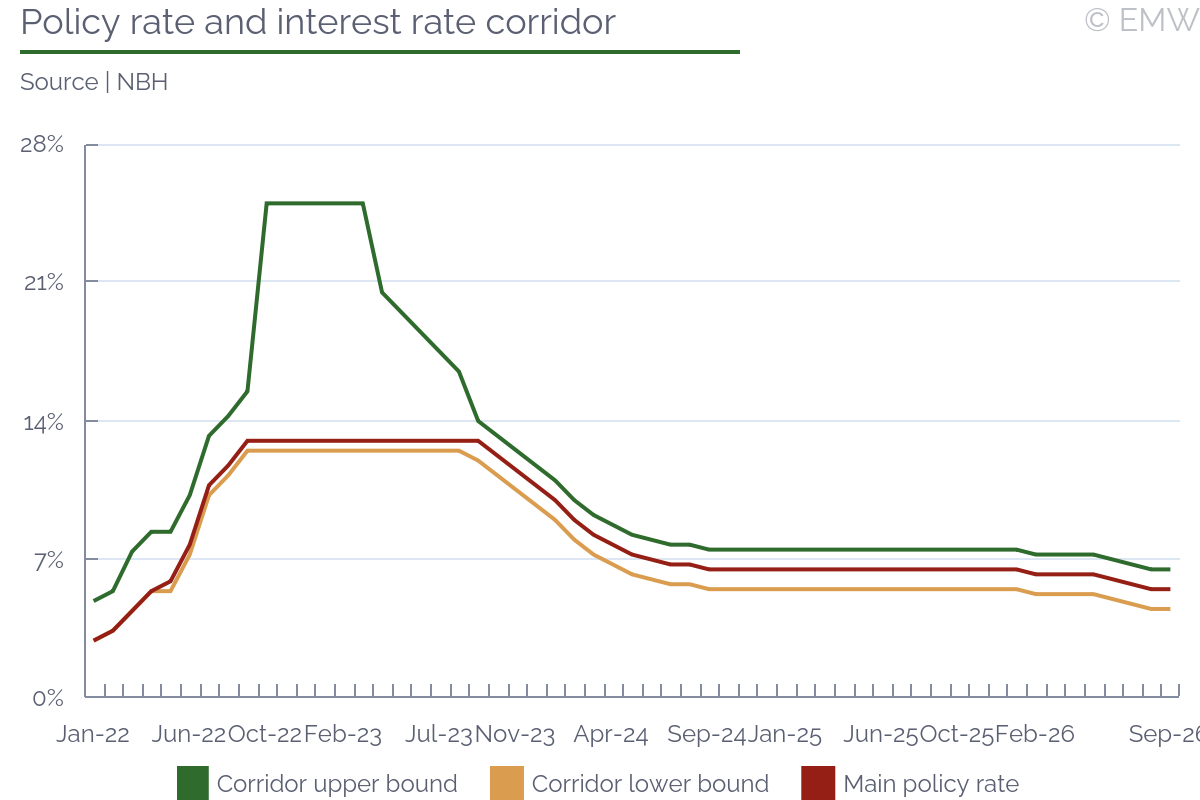
The NBH did not close the door for further policy loosening though. The MPC will use a data-driven approach in the next months, which will allow either a hold or a cut in the short term, NBH governor Mihaly Varga said at the background discussion after the September rate-setting meeting. Deputy governor Zoltan Kurali later elaborated that the possibility for another rate cut by the end of the year depended on the credibility of the government's eurozone ambitions, as presented in the upcoming mid-term fiscal framework. The NBH will wait to assess the market reaction to the mid-term fiscal framework whether it will realistically support the government's convergence criteria target before moving on the policy rate, Kurali explained. The mid-term fiscal framework will be published in the second half of October, so we believe there will be no technical time for the NBH to react on its October meeting. Our baseline scenario is therefore for a policy rate cut not earlier than November, depending on the market reaction to the mid-term fiscal framework, in other words the development of domestic yields and the forint exchange rate. Meanwhile, further deterioration of the global energy price outlook and rate hikes by global central banks could also preclude another rate cut.
The MPC maintained in September that it will keep the real interest rate positive in the next months, pointing out that it was important for keeping the forint stable and anchoring inflation expectations. In this sense, the monetary policy guidance was not much changed in September, while the stance shifted to wait-and-see because of uncertainty regarding the fiscal consolidation path and the global energy price risks. The MPC also expected the lowering of the inflation target to have a guiding impact on inflation expectations going forward, fostering disinflation after mid-2027.
| MPC Members | ||||||||||||||||||||||||||||||||||||||||||||||||
| ||||||||||||||||||||||||||||||||||||||||||||||||
| Source: NBH, EmergingMarketWatch estimates |
Post-meeting MPC statement from September rate-setting meeting
Background presentation of NBH governor Varga after September rate-setting meeting
| Ask the editor | Back to contents |
| RBI to pre-emptively hike rate by 25bps in October |
- Next MPC meeting: October 5-7, 2026
- Current policy rate: 5.25%
- Last decision: Hold (August 5)
- Our forecast: 25bps hike
- Rationale: Inflation is reaccelerating, crude oil has moved back towards USD 100/barrel and sustained INR weakness is increasing imported-price pressures. With growth still resilient, we expect the RBI to begin a cautious tightening cycle in October.
The case for an October rate hike has strengthened since the August meeting. The MPC kept the repo rate unchanged at 5.25% and retained a neutral stance, but the minutes made clear that the debate has shifted away from further easing. Several members warned that repeated food, fuel and input-cost shocks could broaden into underlying inflation, while Governor Sanjay Malhotra acknowledged that a normalisation in inflation could eventually require a recalibration of the policy rate.
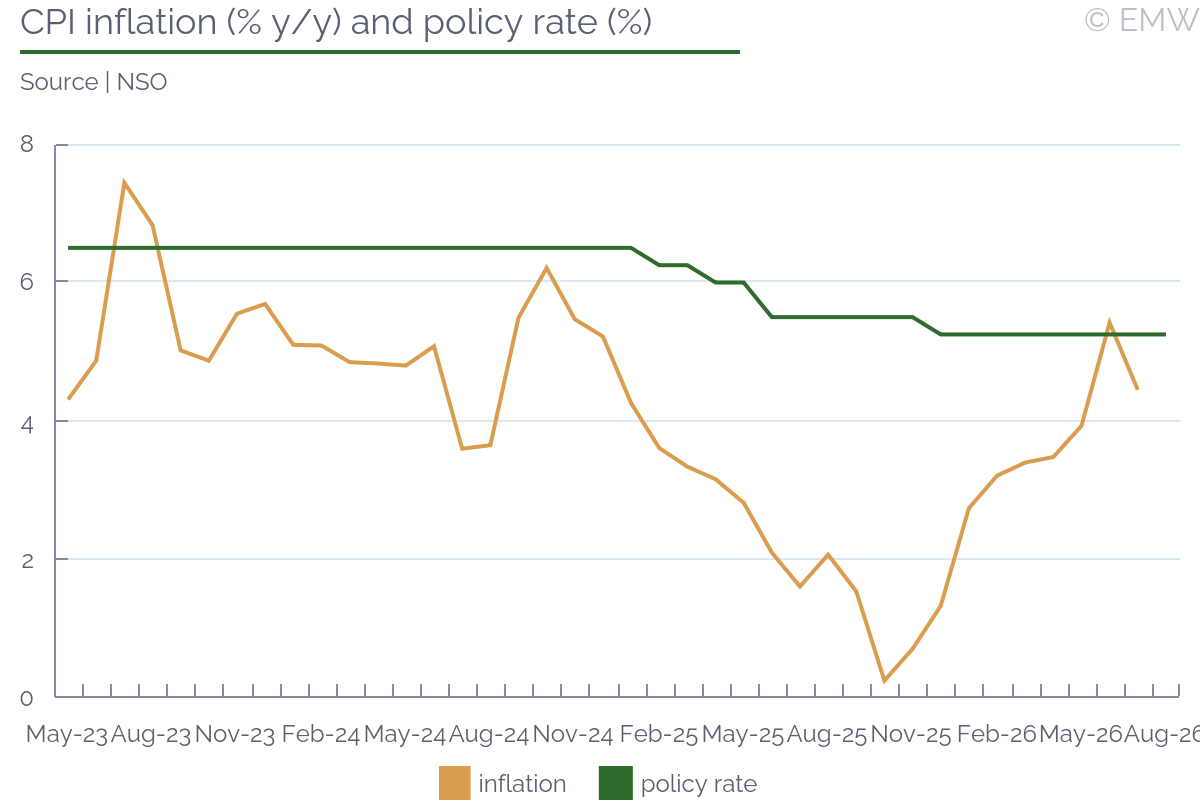
The repo rate has now been unchanged since the 125bps of cumulative easing delivered between February and December 2025. The standing deposit facility rate remains at 5.00%, while the marginal standing facility rate and bank rate are at 5.50%.
Since the August decision, the inflation-growth trade-off has moved further in favour of precautionary tightening. Inflation has remained above target, oil prices have risen sharply again and the INR has weakened beyond USD/ INR 95. At the same time, Q1 FY27 GDP growth surprised on the upside at 7.8%, giving the MPC greater room to prioritise price stability.
Inflation environment
Consumer inflation rose to 4.45% y/y in July, from 4.38% in June, marking a second consecutive reading above the RBI's 4% target. The next inflation release is likely to show a further acceleration: a September Reuters poll expects August CPI inflation at around 4.8%, which would be the highest in 20 months and the third consecutive month above target. Food and fuel are expected to remain the main drivers.
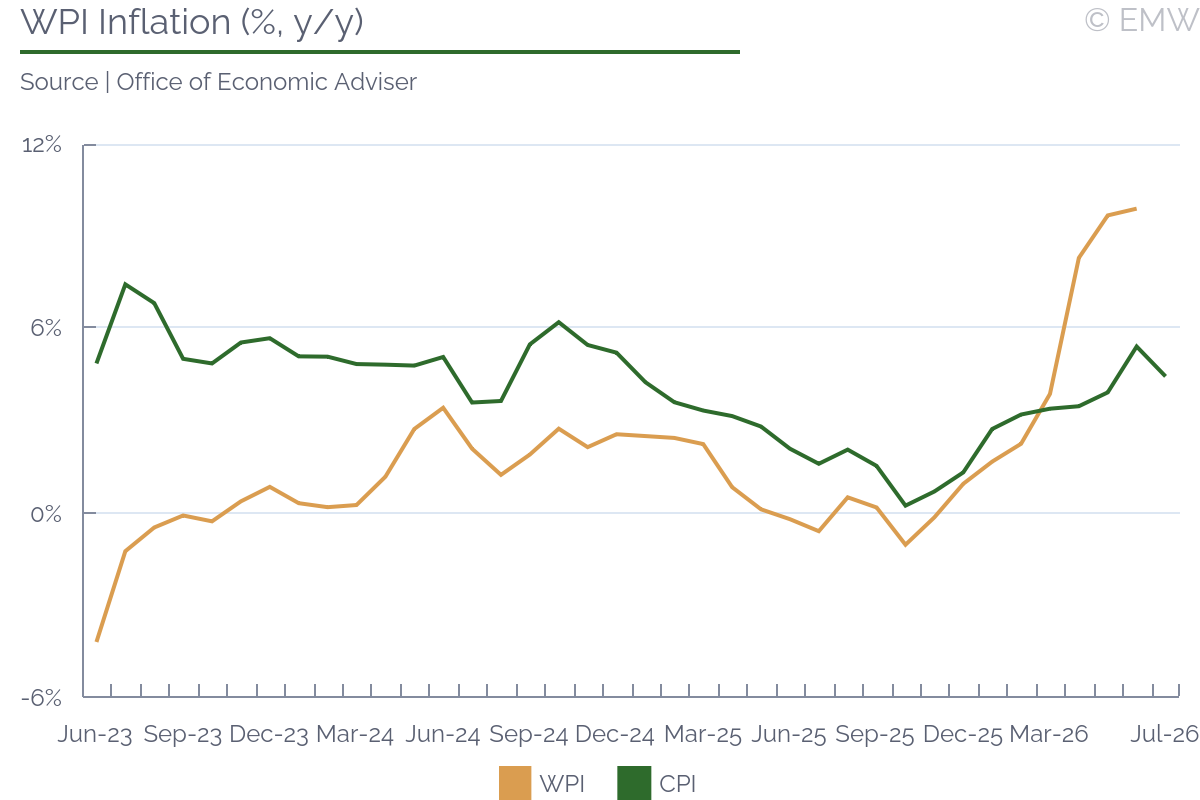
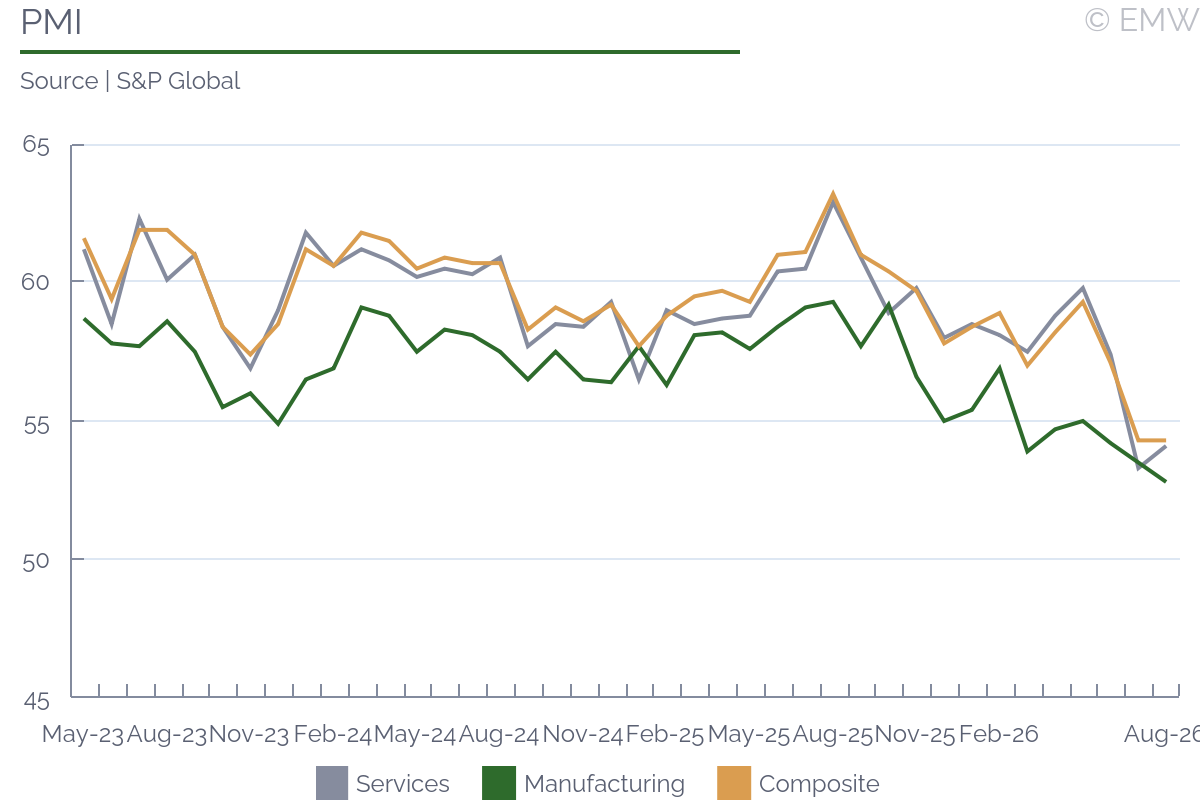
The inflation pipeline remains uncomfortable. Recent PMI data provide a mixed but still cautionary signal. Manufacturing input-cost pressures eased in August, but services firms continued to report higher labour, electricity, digital-platform and other operating expenses. Services selling prices increased at the fastest pace since March, suggesting that some firms retain the ability to pass higher costs to customers. The Services PMI rose to 54.1 from 53.3 in July.
Food remains exposed to uneven rainfall and crop-specific supply disruptions. Onion prices, for example, have remained elevated despite government buffer releases, while an uneven monsoon continues to pose risks to cereals, pulses and oilseeds. The larger near-term shock, however, is energy.
Brent crude moved back above USD 100/barrel on September 9 as renewed US-Iran hostilities raised concerns about supply disruptions. This materially increases the risk of higher fuel, freight and production costs for India, which remains heavily dependent on imported crude. The RBI's August projection already pointed to a difficult second half. It expects CPI inflation at 4.7% in Q2 FY27 before rising to 5.9% in Q3 and 5.5% in Q4. In our view, the latest oil and currency moves have increased the risk that inflation follows, or exceeds, this trajectory.
Growth
Growth has proved stronger than anticipated, reducing the cost of a modest tightening move. Real GDP expanded 7.8% y/y in Q1 FY27, up from 6.9% a year earlier. The composition was also relatively strong: gross fixed capital formation increased 11.9% y/y, manufacturing GVA rose 9.2% and services expanded strongly, while private consumption grew 7.1%.
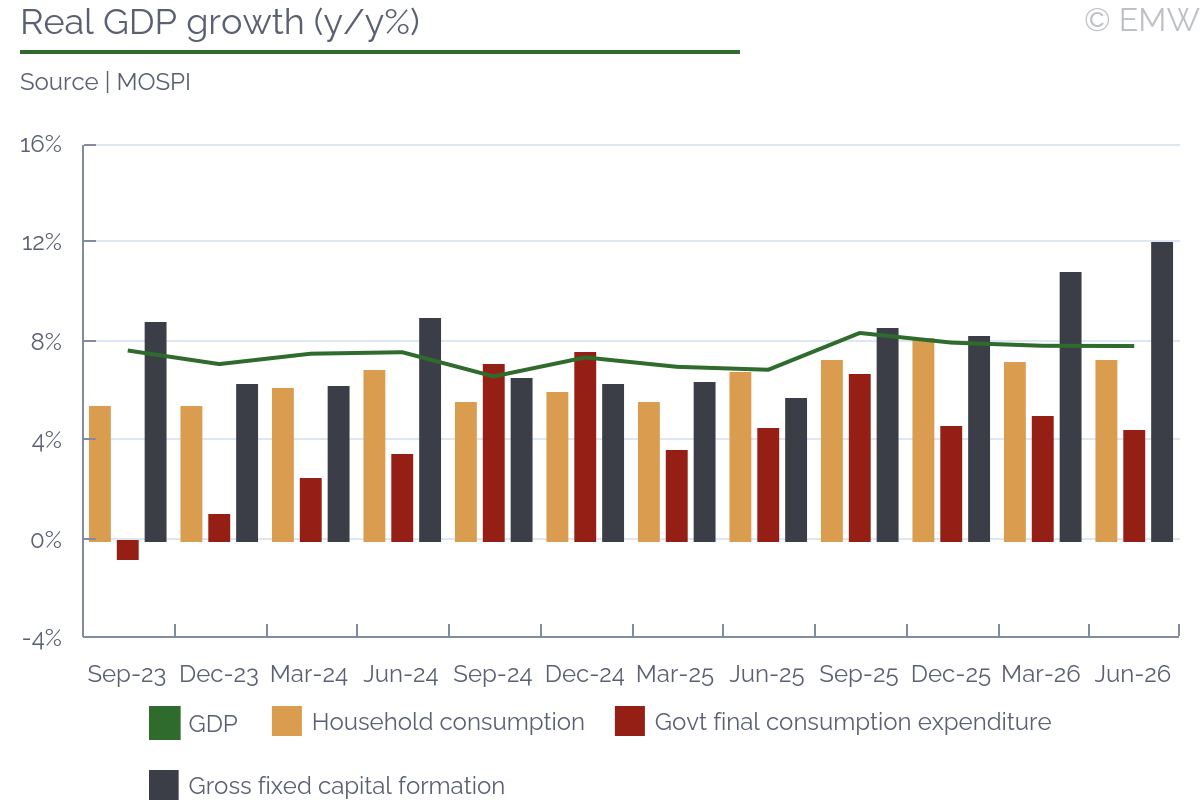
This is stronger than the RBI's previous Q1 projection of 7.0% and reinforces the view that domestic demand can absorb a limited increase in borrowing costs. High-frequency indicators nevertheless show some moderation. The manufacturing PMI fell further to 52.8 in August from 53.5 in July, its lowest level in five years, with output and new-order growth among the weakest since 2021. Services performed somewhat better, with the PMI recovering to 54.1 from 53.3.
The Composite PMI remained at 54.3, however, signalling continued expansion despite slower momentum. Employment strengthened, with aggregate private-sector hiring reaching its fastest pace in 14 months and services employment its strongest in 15 months. This combination matters for policy. Growth is slowing at the margin, which argues against an aggressive tightening cycle, but activity remains sufficiently resilient for the MPC to deliver a precautionary 25bps hike without materially threatening the expansion.
External sector
External pressures have become a stronger part of the October policy case. India's merchandise trade deficit widened further to USD 31.98bn in July, a six-month high, from USD 30.43bn in June. Exports rose 19.6% y/y to a record USD 44.24bn, but imports increased 17.5% to USD 76.22bn as elevated commodity costs and strong domestic demand boosted the import bill. Electronics imports were particularly strong, while higher oil prices and shipping costs linked to the West Asia conflict remain an important vulnerability.
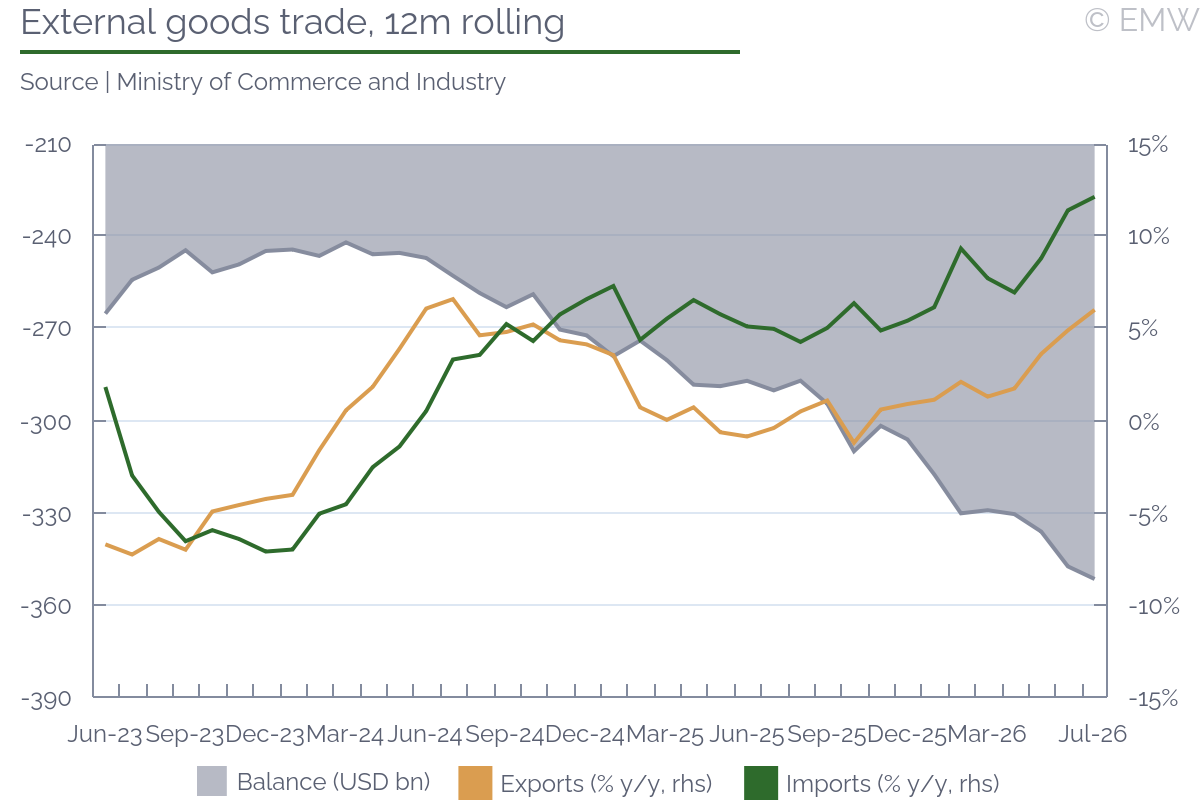
The Q1 current account remained manageable despite the wider merchandise gap. The deficit stood at USD 4.2bn, or 0.5% of GDP, compared with USD 3.4bn, or 0.4%, a year earlier. Strong services receipts and remittances provided substantial offsets, although portfolio investment recorded a USD 9.6bn net outflow and reserves declined by USD 8.1bn on a balance-of-payments basis during the quarter. The more immediate concern is the currency. The INR fell through 95/USD on September 9, touching around USD/INR 95.23 intraday before suspected RBI intervention limited losses. It closed around USD/INR 95.10 as Brent moved above USD 100/barrel. The RBI has been intervening through dollar sales and foreign-exchange swaps to contain volatility.
The RBI nevertheless has substantial room to manage disorderly moves. Foreign-exchange reserves reached a record USD 740.8bn in the week ended August 28 after two consecutive weekly increases of more than USD 11bn. The large reserve buffer reduces external financing risk but does not eliminate the inflationary consequences of sustained INR depreciation.
Policy outlook
Following these dynamics, we continue to expect the MPC to raise the repo rate by 25bps to 5.50% at its October 5-7 meeting. The case has become stronger since August. The August minutes also suggest that the MPC's reaction function is becoming more hawkish. Members increasingly focused on the risk that supply shocks could become generalised, with some explicitly warning that delaying action could eventually require a larger tightening response. The main argument for another pause would be the still supply-driven nature of much of the inflation increase and the moderation visible in manufacturing and parts of private-sector activity. A sharp decline in oil prices, substantial improvement in food supply or clear weakening in domestic demand before the October meeting could therefore delay tightening.
However, in our view, the balance of risks now favours a pre-emptive move. With Brent around USD 100/barrel, the INR around 95/USD and headline inflation moving further above target, another prolonged pause would increase the risk that the RBI falls behind the inflation cycle. We therefore expect a 25bps hike in October, followed by a cautious and data-dependent approach rather than an aggressive tightening cycle.
Further Readings
| Ask the editor | Back to contents |
| BI wants to stand pat, but may raise key rate in October/November |
- Next policy meeting: Oct 20-21
- Current policy rate: 5.75%
- Our forecast: Hold
- Last decision: Hold (Sep 21-22)
- Rationale: BI focuses on macroprudential measures to support rupiah, wants to avoid another rate hike as GDP growth remains solid
Bank Indonesia wants to stand pat at its next MPC meeting on Oct 20-21, as another rate hike could exert pressure on economic growth, in our view. However, it may have to raise the key rate by 25bps in October or November, reflecting the pressure on the rupiah and the hawkish Fed, which raised the federal funds rate by 25bps in September for the first time in three years.
New BI governor Destry Damayanti wants to show policy continuity and independence from the central government, which likely led to the hold decision in September. On the other hand, BI has previously caught markets asleep with both rate hikes and rate cuts, hence Destry has a chance to surprise markets, in our view. We remind that BI raised the key rate by 100bps cumulatively in May-June, after which it has been kept flat at 5.75%.
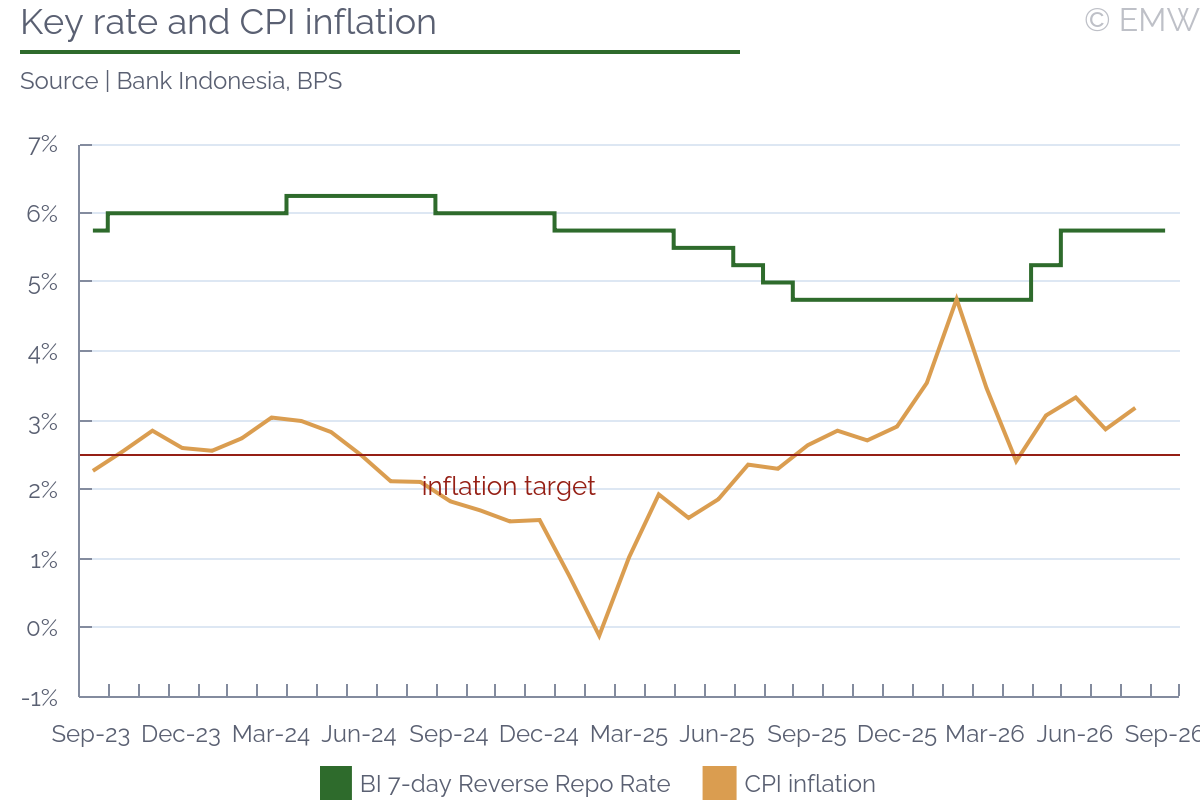
The rupiah is the big question in Q4, as it remains quite volatile. The local currency regained significant ground against the USD in August, before losing nearly 1% in September after the US-Iran conflict reignited, oil prices surpassed USD 100 per barrel and the Fed raised the federal funds rate.
CPI inflation has clearly taken a backseat in monetary policy decision-making, as it remains firmly anchored within the central bank's 2.5+/-1% target band. So far, the inflation outlook remains benign, as the government has contained the direct impact of the high oil prices, while second-round effects are limited.
GDP growth
GDP growth slowed to 5.29% y/y in Q2 from 5.61% y/y in Q1 2026, which brought the H1 expansion to 5.45% y/y. Government spending continues to support GDP growth, though private consumption and investment remain the main growth drivers. BI has maintained its GDP growth forecast at 4.9-5.7%, which seems realistic at present.
On the other hand, the government spending contribution will gradually decline as it scales down its free lunch programme (MBG). So far, the government insists it will have no significant impact on GDP growth, though some marginal slowdown could be expected in H2, in our view.
Exchange rate stability
The rupiah has depreciated by about 7% against the USD since the beginning of the year, making it one of the worst-performing EM currencies globally. It regained some ground in August, as back in July the depreciation reached close to 8%, but again returned to the depreciation path in September.
As a result, so far BI's measures to stabilise the rupiah seem to have had a limited effect, as the local currency has depreciated significantly since the beginning of the year and regained only a fraction of its losses. We should note that apart from the rate hikes, BI regularly carries out its so-called triple intervention, which includes purchases on the spot FX market, domestic non-deliverable forwards (DNDF) and buying government bonds on the secondary market. BI also increased coordination with the government, with the government also starting bond buybacks on the secondary market to boost FPI inflows.
The central bank also introduced a range of other measures aimed at stabilising the rupiah, such as reducing the FX purchase limit from USD 100,000 in the beginning of the year to USD 10,000 from Jul 1. In addition, it also raised the cap on banks' foreign funding portfolio to 40% from 35% previously, aiming to attract more FX inflows.
Inflation environment
CPI inflation accelerated to 3.19% y/y in August from 2.88% y/y in July, remaining within BI's 2.5+/-1% target band, but approaching the upper end. CPI inflation is mainly driven by food prices, which reflect both the rupiah's depreciation and second-round effects from the oil price spike following the US-Iran war. Core inflation also accelerated to 2.92% y/y in August, moving away from the midpoint of BI's target band.
Looking forward, we think the outlook remains benign as the government keeps subsidised fuel prices flat, carrying the burden from the oil price spike. The central bank expressed confidence that CPI inflation will remain under control and within the target band in 2026.
As a result, we think CPI inflation has largely taken a backseat in Bank Indonesia's monetary policy meetings.
Conclusion
Looking forward, we expect BI to stand pat as long as possible, until pressure on the rupiah subsides. On the other hand, should the local currency continue to lose ground against the USD, it will have to match the Fed's 25bp rate hike either in October or in November, in our view. Once again, CPI inflation concerns have diminished, with imported inflation likely the main factor to take into account.
Further reading
| Ask the editor | Back to contents |
| CB holds rate without forward guidance, governor defends current MPR position |
- Next MPC meeting: November 5
- Current policy rate: 6.50%
- EmergingMarketWatch forecast: Hold
The CB held its Monetary Policy Rate (MPR) at 6.50% last week, as expected. The decision was unanimous, as we anticipated, but breaking with some local reports that claimed one board member could vote differently.
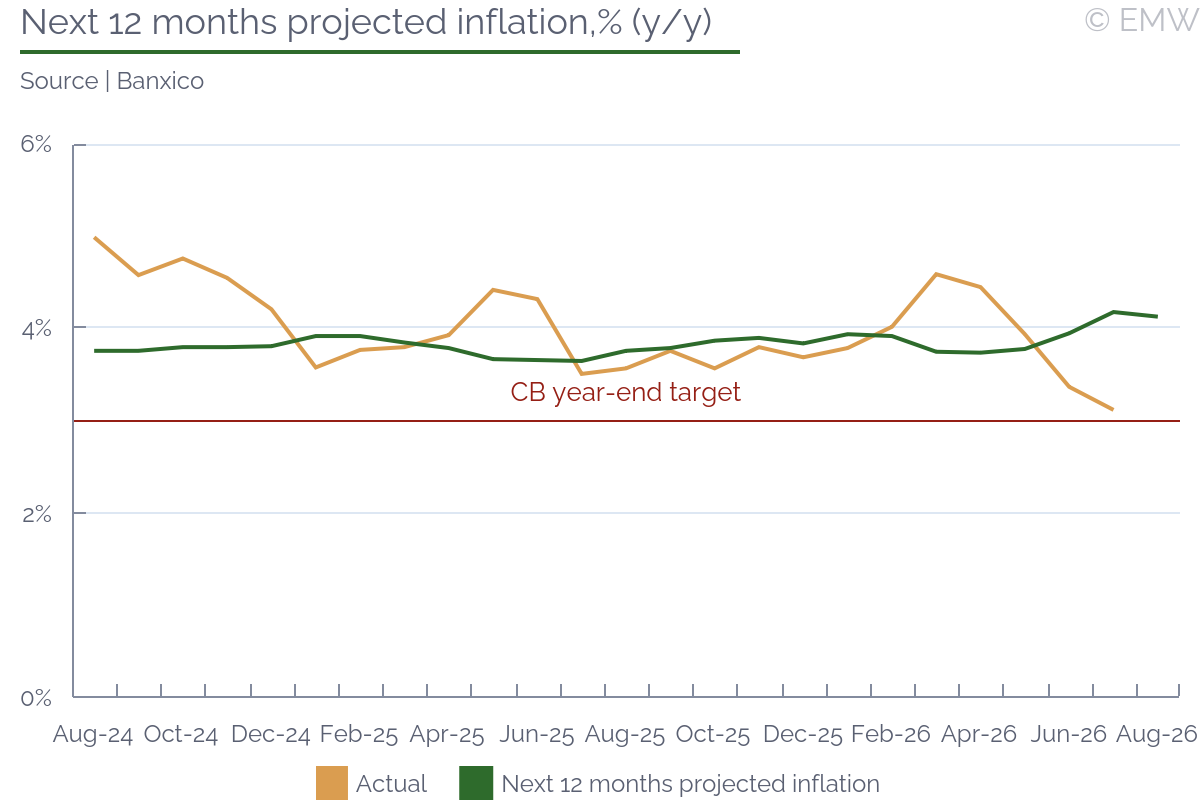
The decision statement did not include clear forward guidance, saying the Monetary Policy Council (MPC) will be making its next policy decisions in response to the disinflation process and to the performance of inflation determinants, including the exchange rate's impact on prices, the output gap, and inflation expectations. This is a significant change from the August policy statement, where the MPC said it sees fit to hold the policy rate at its current position moving forward.
This change suggested that the CB may be pondering monetary policy adjustments moving forward, depending on inflationary data or the performance of its determinants. However, we have not given this change much weight, considering we do not expect the CB to adjust its policy rate so soon after having ended its easing cycle in May.
The Federal Reserve's decision to raise its policy rate by 25bps in September might be the more relevant change to the context in which the CB changed its tone. The CB's decision statement is clear: Mexico's macroeconomic conditions differ from the US and, thus, the MPC doesn't have to mechanically follow the Fed. However, with the market now seemingly expecting further tightening by the Fed, pressure on the CB to change its discourse mounts, risking this pressure being enough to push it to raise its MPR.
The narrower interest-rate differential between the CB and the Fed seems to explain much of the currency depreciation seen recently, with the peso slipping by 6.92% in the last 20 days, closing Tuesday at USD/MXN 18.06, its worst position in six months. We insist the magnitude of the recent depreciation is not too worrying, considering the recent depreciation only erases the appreciation seen earlier in 2026 and recalling the currency posted massive appreciation in 2025, of 13.40%. However, the driver of the depreciation is surely something being pondered by the MPC, in our view, considering the currency may weaken much further if the expectation remains for further tightening by the Fed that narrows the interest-rate differential further.
Indeed, CB Governor Victoria Rodríguez headed a media blitz on Monday and Tuesday to assure the market she is content with the current monetary policy. Both interviews were very similar, with Governor Rodríguez defending the CB's latest decision to hold and seemingly giving arguments for further MPR stability, arguing that 1) CPI inflation continues to perform as the CB expected, 2) the recent currency depreciation doesn't materially worsen the inflationary outlook, and 3) Banxico doesn't have to follow the Fed mechanically.
These interviews do not establish that the CB governor's view is shared by all in the MPC, in our view, considering she stands on the dovish side of the board. Indeed, the latest meeting minutes, to be published by Banxico on October 8, might give a clearer view of the tensions dominating the MPC. In the minutes, we wouldn't be surprised to see one board member pondering the possibility of rate hikes over the coming months, perhaps worried about the interest-rate differential. However, we are confident this won't be the stance of the majority.
In the upcoming minutes, we'll be particularly interested in trying to identify the positions taken by deputy governors Galia Borja and José Gabriel Cuadra, considering they're likely to be the kingmakers if there is pressure on the board to ponder rate adjustments. We'll be surprised to see any of them pondering a rate hike outright. However, at least one might present a path for monetary tightening ahead, something that would greatly change our view of the MPC, which has been rather dovish so far.
Identifying the position of Borja and Cuadra is particularly relevant considering they're unlikely to give interviews where they present their policy outlook more clearly, given they have a minor media presence. However, we expect deputy governors Jonathan Heath and Omar Mejía to appear in local media soon, perhaps once the governor's blitz concludes. We expect opposing views from these deputy governors, as we consider Deputy Governor Heath to be the most hawkish board member, while we see Mejía as the most dovish. Thus, we believe statements from either Heath or Mejía should be taken with a grain of salt, unless Heath dismisses the chances of monetary tightening or Mejía ponders raising the MPR.
All in all, we highlight that the CB has made it clear that no monetary easing should be expected this year. Conditions have changed because of the Fed and the currency's volatility. However, the CB's governor has made it clear that these changes do not alter her view of the inflationary outlook and, thus, should not change MPR expectations.
Overall, we continue to expect the board will hold the policy rate at 6.50% throughout the rest of the year and through early 2027. The chances of a hike over the next six months have certainly increased and will become relevant if the currency slides much more. While we assume the dovish majority would like to cut the policy rate in late 2027, this scenario seems unrealistic amid monetary tightening by the Fed. Thus, we now expect the CB will hold its policy rate at 6.50% throughout 2027.
| Monetary Policy Council members | ||||||||||||||||||||||||||||||
| ||||||||||||||||||||||||||||||
| Note: Overall bias calculated from voting behavior and comments | ||||||||||||||||||||||||||||||
| Source: Banxico |
| Ask the editor | Back to contents |
| MPC cuts main policy rate by 350bps to 23% |
- Next MPC meeting: 23 - 24 November
- Current policy rate: 23%
- EmergingMarketWatch Sep forecast: 26.5%
The MPC voted for an unexpectedly large reduction to the benchmark interest rate on Tuesday (Sep 22), cutting it by 350bps to 23%. This is the largest single cut in our dataset that begins in Jan 2013. The second largest decline occurred in Nov 2015 when the MPC reduced the rate by 200bps. Sep 2026's reduction follows two consecutive holds at the May and July meetings that were largely in response to the economic fallout from the Middle East war. Economists widely expected the committee to hold the rate again this week given the ongoing geopolitical uncertainty, in addition to persistent risks from food and energy prices in Nigeria. The latest MPC meeting comes after August's inflation print showed only a minor drop to 15.39% y/y from 15.43% y/y in July. However, this was the third consecutive month of disinflation and the naira has also maintained relative stability against the dollar this year. Speaking at a briefing after the MPC meeting, CBN governor Olayemi Cardoso said the committee is satisfied with progress on disinflation.
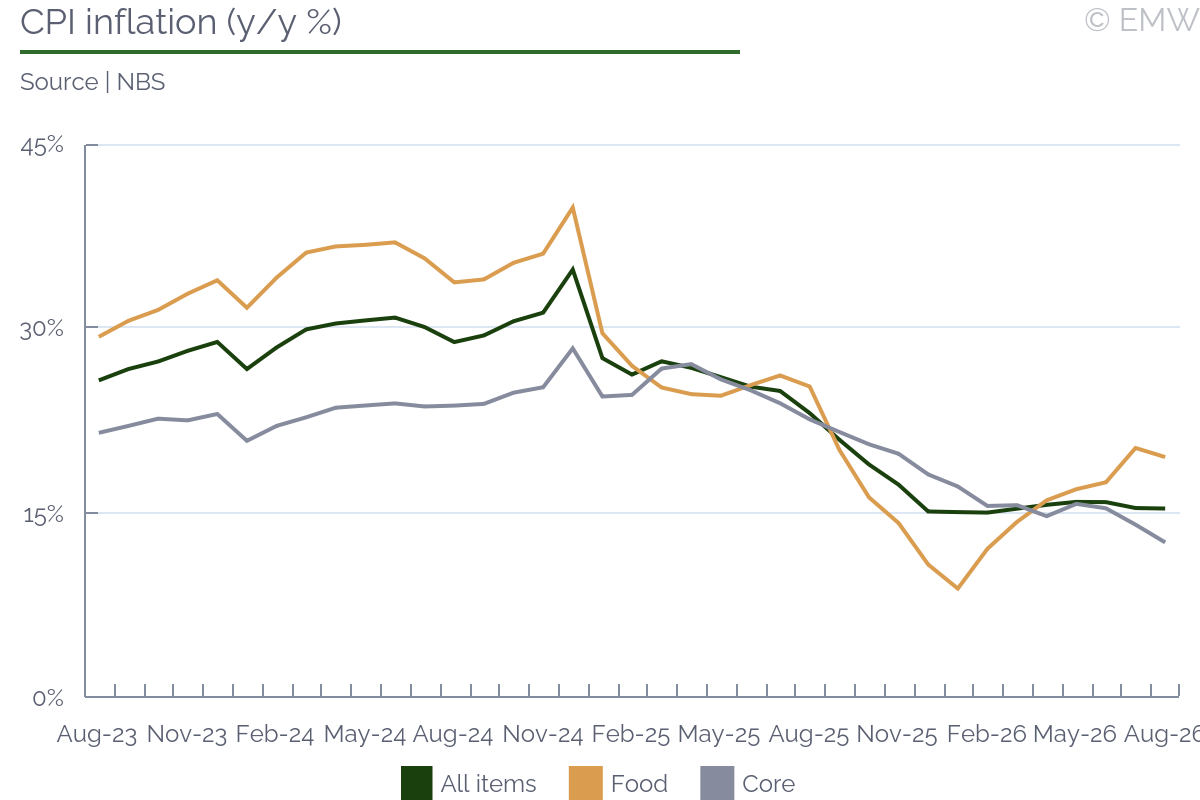
Cardoso told the press briefing that the rate cut represents an "operational reset" intended to improve the effectiveness of monetary policy and support the transition towards an inflation-targeting framework. He said the MPC found that market interest rates had diverged from the benchmark rate, weakening the effectiveness of monetary policy. All 11 members of the MPC attended the two-day meeting. (We note that Lydia Shehu Jafiya is no longer an MPC member due to her retirement from the civil service in December, and she has not been replaced).
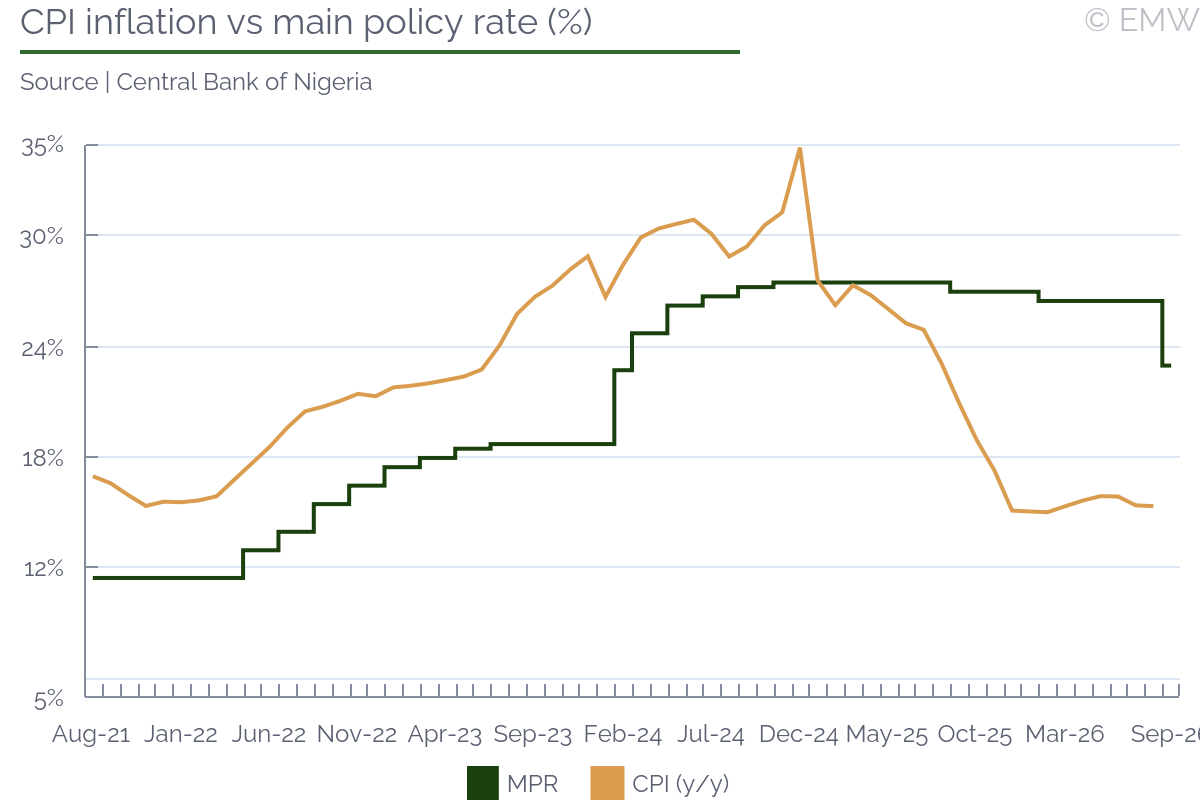
Aside from the rate cut, the committee also adjusted the standing facilities corridor to +50/-300 basis points around the new MPR. The CBN retained other key monetary parameters. The MPC decided to keep the cash reserve requirement (CRR) for deposit money banks at 45% and merchant banks at 16%, and the CRR on non-TSA public sector deposits at 75%.
In summary, the MPC voted to:
- Reduce the main policy rate to 23%
- Adjust the standing facilities corridor to +50/-300 around the MPR
- Keep the CRR at 45%
Monetary Policy Committee Statement
Monetary Policy Committee Meeting Schedule
| MPC vote by members (bps) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Source: CBN |
| Ask the editor | Back to contents |
| SBP looks through oil shock, but October hike remains possible |
Next policy meeting: Oct 26, 2026
- Current policy rate: 11.50%
- Last decision: Hold (Sep 14, 2026)
- Our forecast: Hike by 25-50bps
- Rationale: Persistently elevated global oil prices could force SBP to raise its key rate
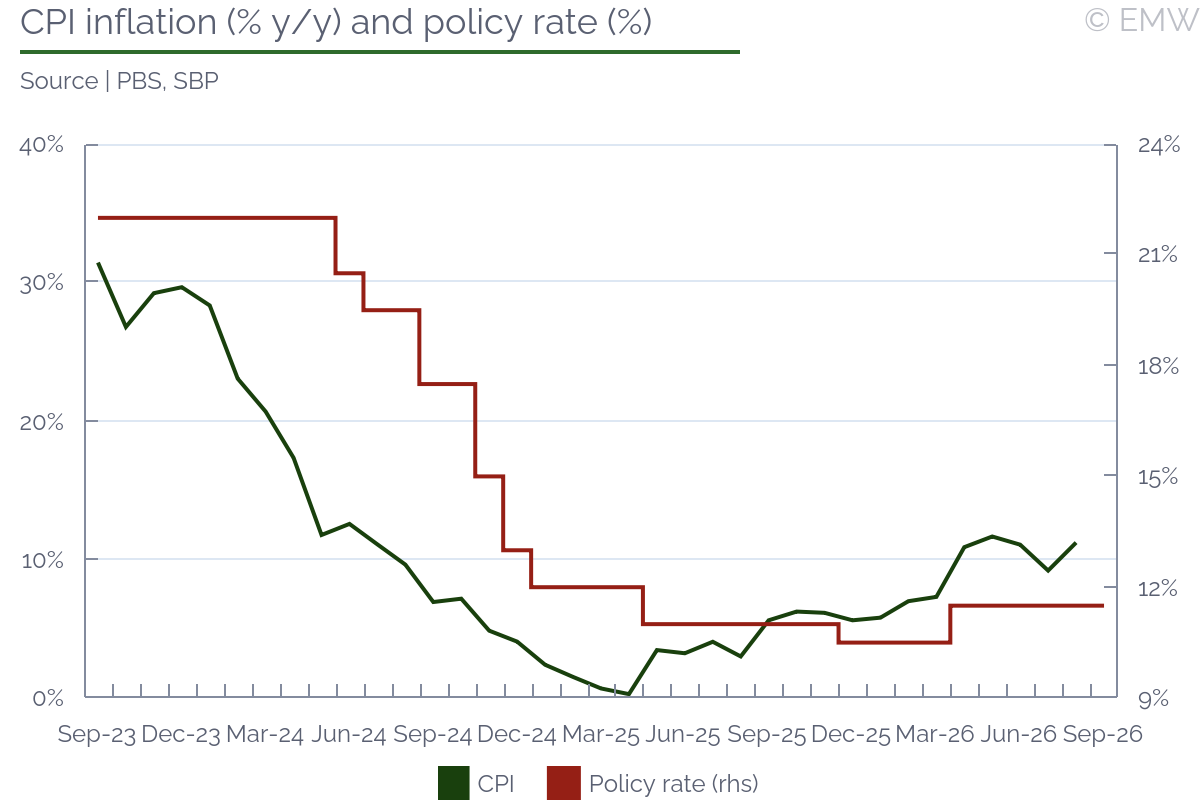
The State Bank of Pakistan (SBP) on Sep 14 kept the policy rate unchanged at 11.5% for the third consecutive meeting. The decision was in line with market expectations. We had predicted a 25-50bps hike, arguing that renewed hostilities in the Middle East and the subsequent rally in global oil prices would prompt the central bank to raise its key rate, as it did in April. Instead, the central bank chose to look through the latest supply shock, taking comfort from the stronger external sector and benign year-ahead inflation outlook. However, the vote showed growing concern within the MPC: three of its members voted against keeping the rate unchanged, compared with none at the July meeting. This suggests disagreement over the risks that higher global commodity prices pose to inflation and the external account.
Inflation environment
CPI inflation accelerated to a three-month high of 11.1% y/y in August, driven largely by higher food, fuel and electricity prices. It has now remained above the SBP's 5-7% target range for six consecutive months. Nevertheless, the SBP continued to see inflation gradually easing to the upper bound of the target range by June 2027. This implies a firmly positive real interest rate on a forward-looking basis, as stressed by the IMF. The central bank said the restrictive monetary stance would likely keep demand-side pressures in check and contain the second-round effects of food and energy inflation. We think the SBP considers the latest rise in inflation to be primarily supply-driven rather than a result of overheating demand. Its forecast also appears to assume that the latest global oil price shock will be temporary and will therefore neither generate second-round effects nor unanchor inflation expectations. Although inflation expectations rose further in September, they remained well below their pre-conflict 12-month average. Planned wheat imports could also help ease food inflation, which reached a nearly two-and-a-half-year high in August.
External sector
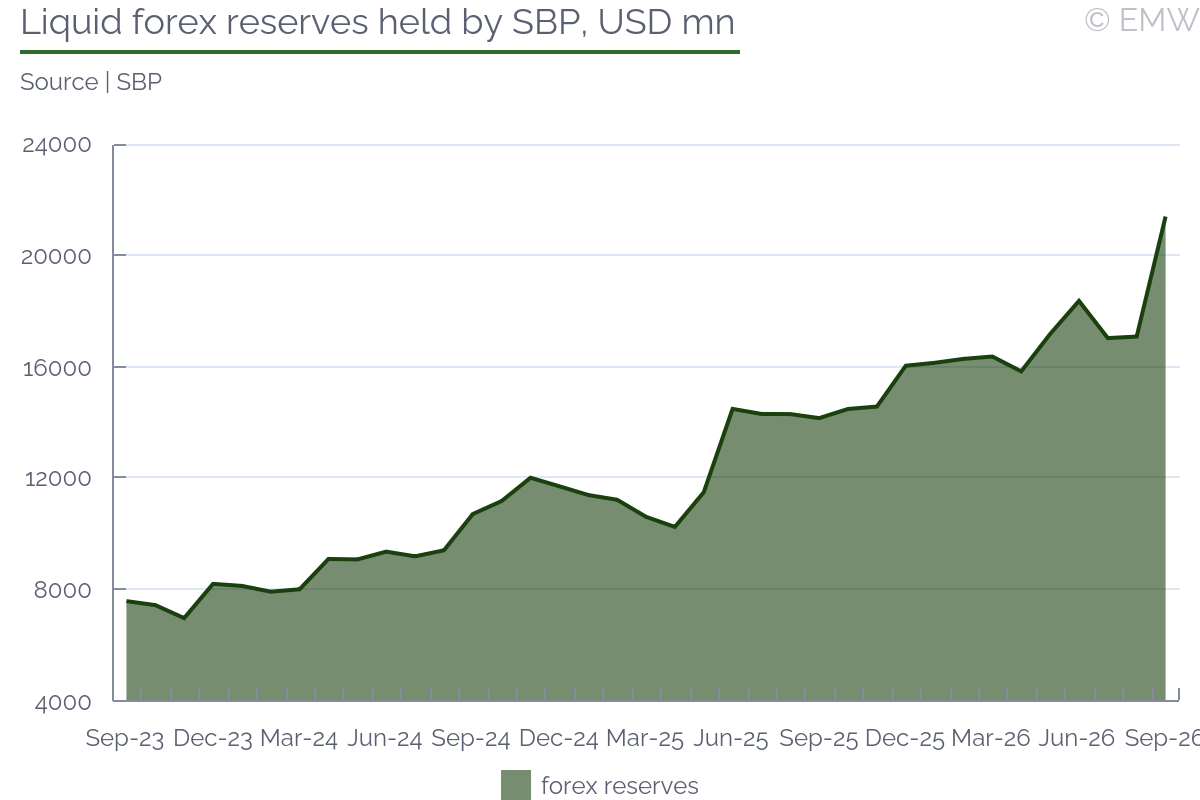
The SBP expected external sector pressures to remain modest, supported by robust workers' remittances and higher financial inflows. It maintained its current account deficit forecast at 0-1% of GDP in FY27. Foreign exchange reserves rose from USD 18.3bn on Sep 4 to a record USD 21.4bn following the government's USD 3bn Eurobond issuance. However, much of this increase may be temporary, as the government is reportedly considering using the proceeds to repay a USD 3bn Saudi loan due next month. This appears plausible, given that the SBP had earlier projected reserves of USD 20.2bn at end-Dec 2026. The next major inflow is expected from the IMF, which is likely to disburse USD 1.2bn under its two programmes before the end of this year. This, together with further global bond issuance and continued dollar purchases by the SBP, should support reserves despite the possible repayment of the Saudi loan. Meanwhile, pressure on the rupee remains limited. The currency has appreciated, albeit marginally, against the US dollar in recent months, with the USD/PKR rate falling by 1% year-to-date to 277.30 as of Sep 15.
GDP growth
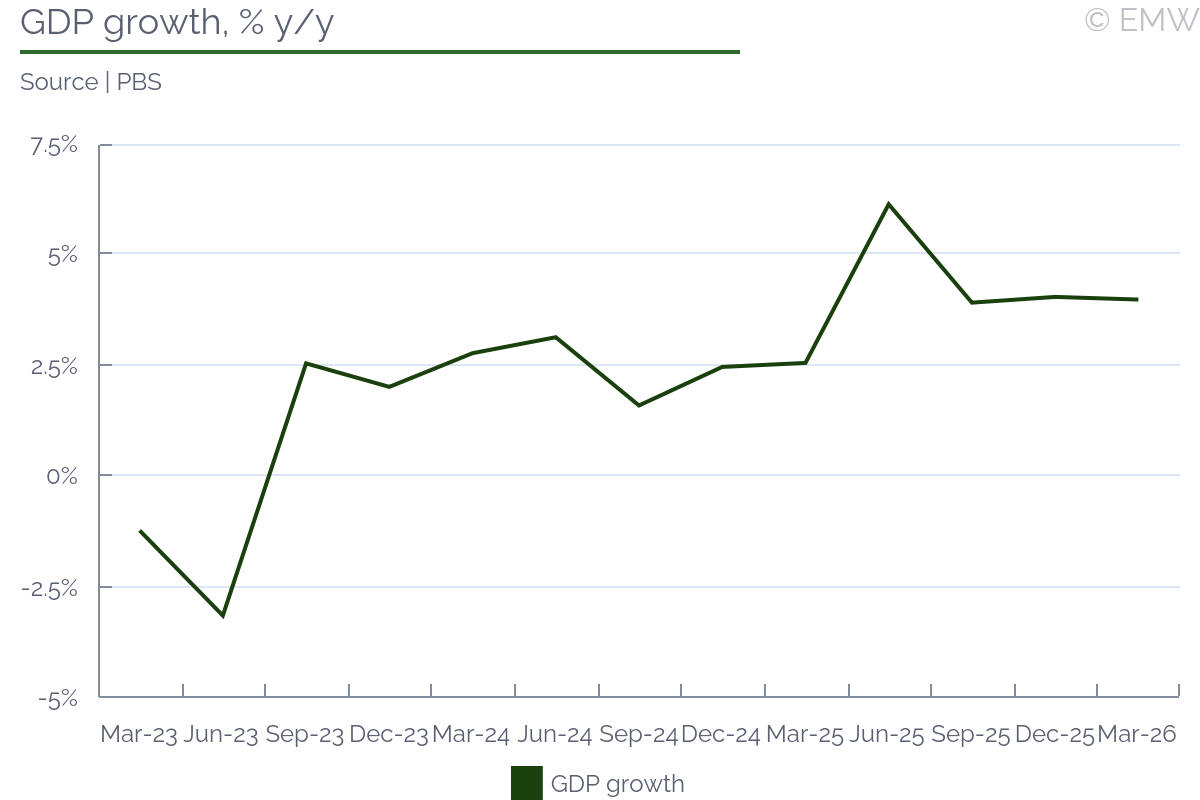
The SBP also retained a positive view of growth, noting that economic activity began to recover in July after weakening during the Apr-Jun quarter. It pointed to solid growth in high-frequency indicators, including fuel sales, private-sector credit and textile exports, as well as improved business sentiment and satellite data on nighttime lights and gas emissions, as evidence that growth momentum was picking up. Prospects for agriculture have also improved due to increased acreage under rice and sugarcane and higher cotton output. As a result, the SBP kept its FY27 GDP growth forecast unchanged at 3.5-4.5%, compared with estimated growth of 3.7% in FY26. However, risks to the outlook are tilted to the downside, given rising fuel prices and the government's plan to revive austerity measures, including early market closures. Since Sep 8, petrol and diesel prices have risen by 11.1% and 10%, respectively.
Conclusion
Overall, the stronger external position and expectations that the Middle East conflict will ease soon gave the SBP enough confidence to keep the policy rate unchanged. However, if global oil prices remain elevated until the next meeting in late October, the central bank may be forced to raise rates to protect its hard-earned macroeconomic stability.
Further Reading
| Ask the editor | Back to contents |
| Hike by 25bps, hold decision both possible in October |
- Next monetary policy meeting: Oct 22
- Current policy rate: 5.00%
- EmergingMarketWatch forecast: Hike by 25bps or hold
- Rationale: Monetary Board statement of Aug 27; continuing peso depreciation
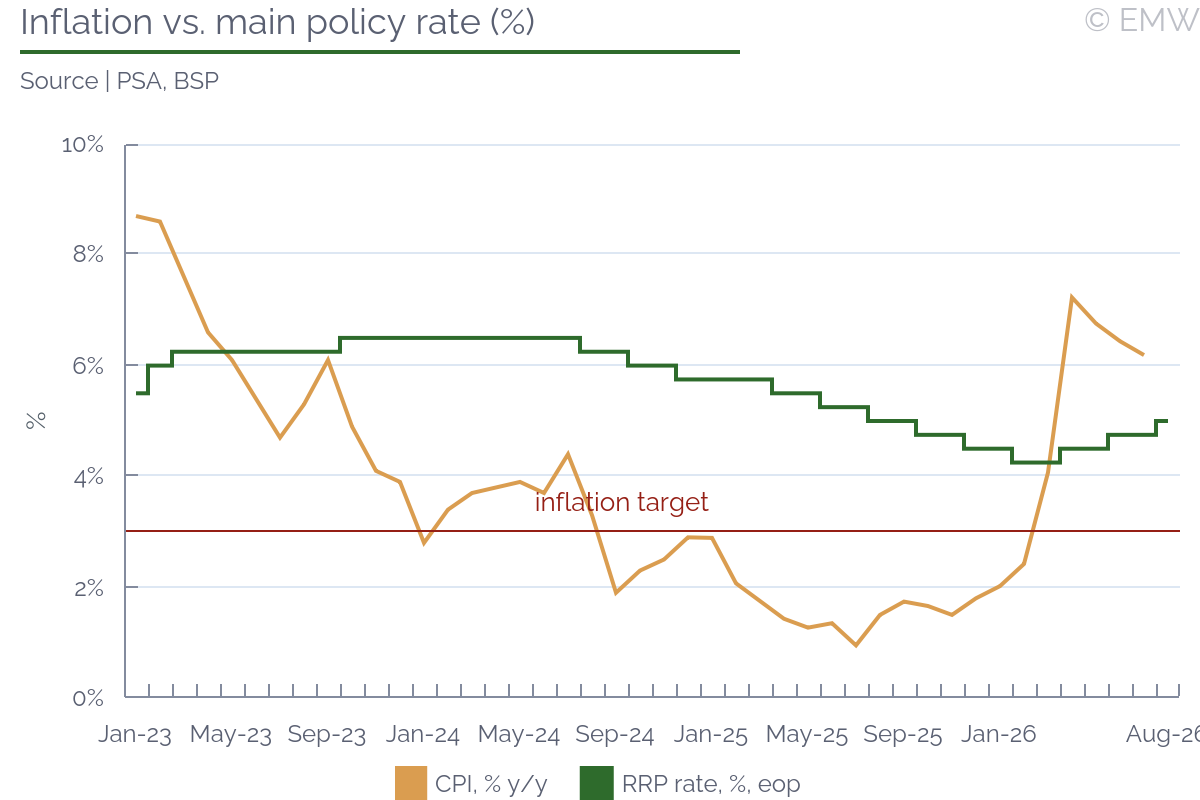
We think that a hike by 25bps and a hold decision are both possible at the next meeting of BSP's Monetary Board (MB) on Oct 22. On Thu., the MB raised the policy interest rate by 25bps to 5.00%. This was the third consecutive rate hike. The MB said that pre-emptive monetary action is needed due to several underlying price risks.
These risks include oil prices that continue to be volatile and the possible effects of severe El Niño conditions on farming prices. There is also a need for close monitoring of potential wage adjustments, including their impact on broader price setting and second-round effects.
The measured policy rate hikes will continue to anchor inflation expectations and reduce the risk of further second-round effects, the press release said. Going forward, the MB said it is ready to take monetary policy action if needed to ensure the return of inflation to the 3.0% target, in line with its price stability mandate.
After the MB meeting, BSP Governor Eli Remolona Jr. said they are hoping that they will not need another increase in the key rate, local media reported.
Inflation
The MB still expects the average headline inflation to be above the upper end of the 3±1% tolerance band in 2026 and 2027. The latest core inflation estimates also suggest broadening price pressures. Nevertheless, the MB expects headline inflation to ease and settle near the 3.0% target by 2028.
The BSP's latest CPI inflation forecast is 6.1% in 2026, 5.4% in 2027 and 3.3% in 2028. The central bank's previous projection was 6.4% this year and 4.5% next year.
The central bank projects August inflation to settle within the 5.5-6.5% y/y range. CPI inflation slowed to 6.2% y/y in July from 6.4% y/y in June. The CPI rose by 5.0% y/y in Jan-Jul. Annual core inflation was 4.2% in July, decelerating from 4.4% in June.
Economic growth
The growth fundamentals seem to be intact over the medium term, in spite of the slow growth in H1, the press release said. The MB expects growth to accelerate in H2 with the support of fiscal measures.
GDP increased by 2.3% y/y in Q2, slowing down from 2.8% y/y in Q1. The GDP expanded by 2.6% y/y in H1. The government targets GDP growth of 3.5-4.5% for 2026.
Exchange rate
The peso is trading at USD/PHP 62.603 at the time of writing, which compares with USD/PHP 61.897 on Aug 27. The exchange rate was USD/PHP 58.856 on Dec 31, 2025.
Further reading
Press release after Aug 27 monetary policy action
Schedule of monetary policy meetings
| Ask the editor | Back to contents |
| MPC still set to hold in October, but may discuss scenario for rate hikes |
- Next MPC meeting: Oct 6-7, 2026
- Current policy rate: 3.75%
- EmergingMarketWatch forecast: 3.75%
Rationale: Fuel prices have pushed up CPI inflation, and it jumped to 4.0% y/y in September from 3.4% in August, rising above the 1.5-3.5% range around the central bank's 2.5% target for the first time since Jun-25. The inflation rise is predicated on what is a supply shock, but the Monetary Policy Council might prove sensitive to it due to the sheer scale of the increase, the fact the key rate is 3.75%, and the threat of knock-on effects, especially with other potential inflationary factors out there (i.e., food, tariffs, fiscal policy). The hawkish turn of events is likely to lead the MPC to begin discussing rate hikes as soon as the October sitting, as suggested recently by MPC member Ludwik Kotecki, but a hike doesn't seem likely yet.
The MPC will likely focus sharply on how much threat there is that the fuel shock will impact other areas of the economy. NBP and MPC head Adam Glapinski often focuses on a macro picture that includes wages, which have slowed of late and thus won't push the council towards a hawkish decision. He does focus too on fiscal policy, though here a high deficit is likely to make the MPC more hawkish than otherwise. The broader economy looks fair, though forecasts continue to be for a slowdown next year.
Other factors may loom large as well. Food prices have helped cap inflation in recent months, something Glapinski has noted at his monthly pressers. But the prospect for food price increases is clear, especially as diesel prices have soared to recent levels. Fertilizer prices have also jumped due to the war in the Middle East. Whereas this year's crops were based on fertilizer bought before the US and Israel's decision to attack Iran, next year's crops will reflect the much higher prices. Diesel and fertilizer together would seem likely to boost prices, especially in light of recent drought, heatwaves, and the global impact of El Nino.
Tariffs are another question. Power tariffs do look likely to rise next year, though the scale of this is an open question. The regulator URE is controlled by someone appointed by the ruling coalition and that would seem to make it likelier they seek to limit any tariff increases in order not to hurt the ruling coalition parties' chances in the autumn 2027 elections. The same goes for natural gas. Still, there is some scope for household tariff increases due to the big rise in wholesale prices, with the question how much at this stage.
In the end, Glapinski expressed a stance in September that clearly displayed the preference for rates to be kept on hold for some time, and to mid-2027. This is tantamount to meaning he would prefer the MPC waited out the runup inflation and then could return to easing later next year as the inflation outlook for 2028 is still good. But inflation has accelerated more than expected when the July inflation projection was done, and so that could worsen the outlook. This makes the November inflation projection update important. Any sharp deterioration in the outlook and the MPC could very well hike in November or later this year. That said, there are many uncertainties out there and if oil prices fall, this will take pressure off of headline inflation and might allow the MPC to keep rates flat for a longer period.
| MPC breakdown | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Source: NBP |
Latest NBP inflation report (July 2026)
| Ask the editor | Back to contents |
| CBT likely to cut 100bps but to remain cautious amid risks |
- Next MPC meeting: Oct 22, 2026
- Current policy rate: 37.0%
- EmergingMarketWatch forecast: Cut by 100bps
- Rationale: Easing underlying inflation supports cut, but financial, external and administered-price risks warrant cautious 100bps move
We expect the CBT to decrease the policy rate by 100 bps to 36.0% at the Oct 22 MPC meeting. The case, however, has become less clear-cut since the September meeting, we note. The domestic inflation outlook still seems generally consistent with gradual easing. Our latest September CPI nowcast stands at 2.22% m/m and 30.2% y/y, while the CBT market participants survey points to 2.12% m/m. Turk-Is food inflation also fell substantially to 1.10% m/m in September, lowering the annual rate by 2.8pps to 35.1% y/y. We feel that the newest signs are still substantially in line with the CBT's September judgement that the underlying inflation trend is moderating, along with a reduction in domestic demand.
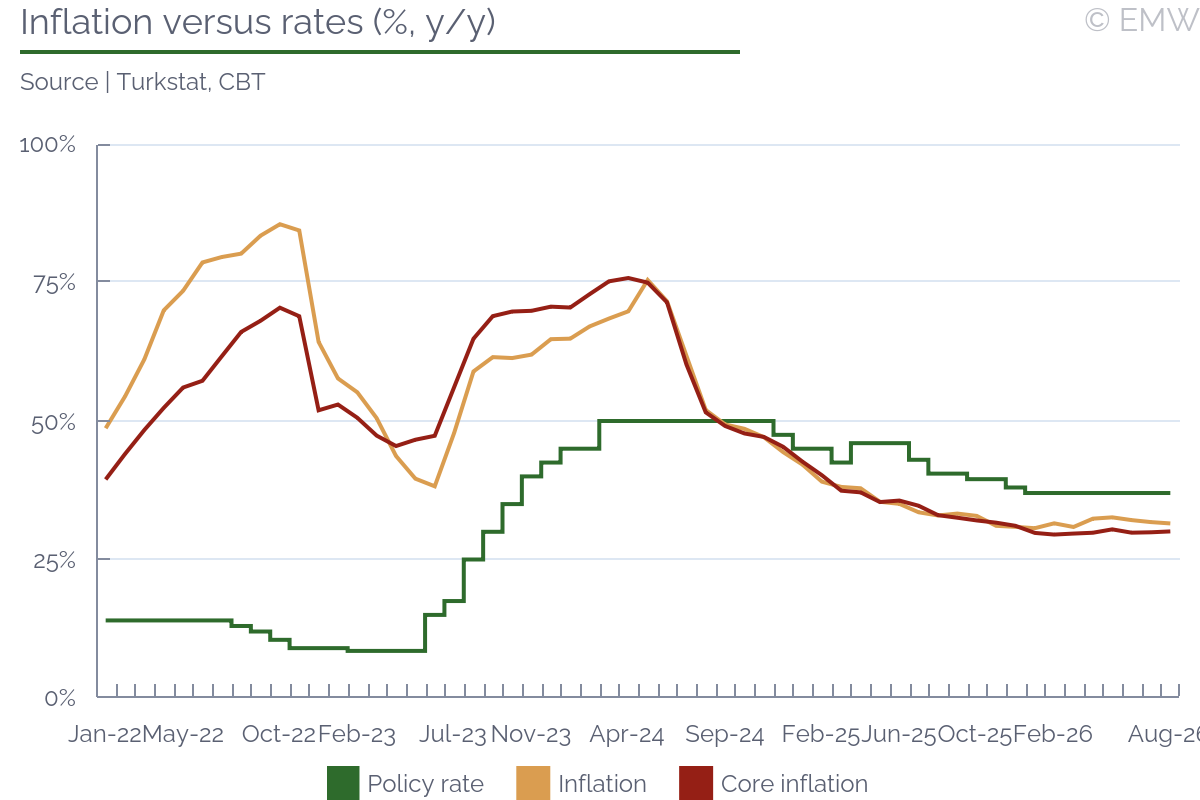
The near-term inflation situation is getting a little more difficult, however. We estimate that the gasoline tax reset that starts on Oct 1 will lead to a noticeable first-round rise in fuel prices and might add roughly 0.25pp directly to October CPI, assuming full pass-through. We would expect the CBT to distinguish this mostly tax driven price level shock from a deterioration in underlying inflation. For monetary policy, the most pertinent question will be whether increasing fuel costs generate major second-round impacts through transportation costs, inflation expectations and broader pricing behaviour. The October CPI will not be out when the MPC meets but it will have much more information on the transmission through the leading indicators.
That said, the investment fund crisis has added a fresh source of domestic concern, we think. If the losses or constraints on access to wealth are large enough, the consequent negative wealth effect could, in our assessment, weigh on spending and consolidate the decrease in domestic demand. We would be wary about mechanically converting the reported loss amount of USD 20bn into a consumption effect however, given the actual impact would depend on realised losses, the distribution of affected assets and the spending response of affected households and savers.
An even more important factor for monetary policy might be confidence in TRY-denominated assets. The market instability has already prompted a number of measures to calm financial circumstances, with the CBT already providing more liquidity and intervening in the FX market following the initial shock. Should fears about investment funds undermine confidence in TRY assets more widely, this might be an incentive to move into FX, gold or other safe-haven assets, we think. Such a move would boost pressure on the exchange rate and reserves and could eventually flow back into inflation expectations, we note. The fund crisis could therefore work in opposite directions for monetary policy as its wealth effect may depress consumption and prove disinflationary, while reduced confidence in TRY assets and increased FX demand would decrease the CBT's room to soften, we underline.
This is on top of the external uncertainty already outlined at the September meeting. The CBT continues to face the risk that geopolitical tensions and higher energy prices feed inflation through cost pressures, while at the same time weakening the current account and reserve prospects. Uncertainty also derives from weather, we highlight. For instance, the near-term food price path is subject to unfavourable weather and agricultural supply conditions. As the tourist high season ends and winter energy consumption starts to rise, seasonal conditions for current account will also become less supportive in the coming weeks, we note. Moreover, headline reserves could also be impacted by gold valuation effects. Thus, we continue to believe that the reserve trajectory will be increasingly important for the speed of monetary easing, but the possible source of pressure is now broader than the external background alone.
All told, the important question for the coming weeks will, in our view, be if financial conditions are contained enough. We believe that if the fund situation settles down without a persistent surge in FX demand, while energy prices and geopolitical concerns remain manageable, the CBT will have enough space to resume its easing. A further session of market stress, however, that erodes trust in TRY assets, fuels FX demand and results in more reserve losses could convince the CBT to adopt a wait-and-see stance even if the underlying inflation path remains favourable. At this point, we continue to view this balance as consistent with a cautious re-start of easing and maintain our prediction for a 100bps rate decrease to 36.0% in October. With more than three weeks to go until the meeting and many of these risks still evolving, we will review our call if conditions change dramatically.
Summary of September rate-setting meeting
MPC rate decision in September
Quarterly Inflation Report for Q3 (Only overview available in English)
| Ask the editor | Back to contents |
| BCCh to hold at 4.50% on Sep 8 and likely through 2026 as risks stay balanced |
- Next MPC meeting: Sep 8
- Current policy rate: 4.50%
- EmergingMarketWatch forecast: 4.50%
Summary
We expect the BCCh's Monetary Policy Council to keep the MPR at 4.50% on Sep 8, and we believe it will remain on hold throughout the remainder of 2026. The July CPI release that saw inflation come down to 3.5% y/y weakened the case for a hike, while persistently high services inflation and renewed external risks continue to make a cut difficult to justify. With medium-term inflation expectations anchored at the 3.0% monetary policy target and activity weaker than expected, the balance of risks remains broadly neutral.
Minutes from the BCCh's last meeting reinforce this view. Although the post-meeting statement adopted a more cautious tone due to renewed conflict in the Middle East and higher oil prices, minutes showed that the MPC did not actively consider a hike. All members agreed that maintaining the MPR was the only plausible option because higher external inflation risks were offset by weaker domestic activity and investment. The current guidance remains meeting-by-meeting, with no bias toward either a hike or a cut.
The market consensus is similarly strong. All but one of the 53 analysts surveyed by the BCCh in August expect a hold in September, and all but two expect the MPR to remain at 4.50% for at least the next two meetings. Some 81% forecast that the rate will remain unchanged through year-end.
Inflation moving closer to target
Headline inflation eased to 3.5% y/y in July from 4.3% in June, slightly below expectations. Much of the decline reflected lower energy inflation and the fading contribution from the large electricity tariff adjustments implemented in 2025. The result indicates that the June acceleration was not the start of a broad inflationary trend and reduces the probability of a rate hike.
Core inflation also remains broadly consistent with a gradual return to target. The BCCh's preferred core measure was 3.2% y/y in July and remained within a narrow 3.2%-3.4% range for ten months. Its annualized increase over the last three months was 3.3%, suggesting that underlying inflation has remained relatively stable despite considerable volatility in energy prices.
Still, the inflation breakdown does not support a dovish shift. Services inflation stood at 4.3% y/y, with dining, healthcare and education prices rising by more than 5.0%. Food inflation remained at 4.0%, while fruit and vegetable inflation accelerated following a harsh July storm, potentially creating additional short-term pressure.
Inflation expectations tell a similar story. Expected inflation one year ahead increased slightly to 3.1% in the latest consensus poll, while expected core inflation held at 3.2%. However, expectations at longer horizons remain anchored at the 3.0% target. This combination gives the MPC room to look through temporary food and energy shocks, but not enough evidence to convincingly support a cut.
Weak activity offsets inflation risks
The consensus GDP growth forecast for 2026 remained at 1.3% in August after substantial downward revisions during the previous four months. There was a positive activity surprise in June, but it followed several readings that were weaker than expected, and was insufficient to change the annual outlook.
The slowdown has also spread beyond the natural resource sectors that initially drove the weakness of activity. The BCCh mentioned that realized investment was weaker than projected in Q2, particularly in energy and real estate, while consumption lost momentum amid deteriorating confidence, weaker real income growth and a soft labor market. The July storm will probably weigh temporarily on activity, although reconstruction efforts should allow part of that decline to be recovered later.
Investment fundamentals remain favorable for 2027 onward, supported by a large project pipeline and the recently approved omnibus bill. However, the BCCh has emphasized that planned projects have not yet translated into stronger realized investment. For the September decision, current demand weakness matters more than the prospect of a recovery next year.
This weak domestic environment reduces the likelihood that temporary increases in food or energy prices will produce broad second-round effects. It also makes a rate hike unnecessarily restrictive unless there is a more persistent external shock or evidence that inflation expectations are becoming unanchored.
External risks still argue for caution
The main upside inflation risk remains the conflict in the Middle East. Oil prices had returned to around USD 100 per barrel by the July meeting, while renewed US tariffs and higher global interest rates added uncertainty. A sustained increase in oil prices could again raise local fuel prices, weaken the peso and delay inflation convergence.
However, pass-through from fuel prices has remained consistent with historical patterns so far, and the earlier shock is partially reversing. The MPC can therefore continue to treat external price pressure as a risk scenario rather than the baseline.
A hike would become more plausible if oil prices rise further, the CLP depreciates sharply, or the resulting pass-through begins to affect services and inflation expectations. Conversely, a cut would require clearer evidence that services inflation is easing, headline inflation is converging sustainably toward 3.0%, and external energy risks have subsided.
Under the current baseline, neither condition is likely to be met by Sep 8. We expect the MPR to remain at 4.50% through year-end, with a 25bps cut toward 4.25% becoming more plausible during H1 2027 if inflation convergence continues and domestic activity remains soft.
| Ask the editor | Back to contents |
| BanRep likely to hold rates on Sep 30; politics, not data, drive the call |
- Next board meeting: Sep 30, 2026
- Current policy rate: 12.00%
- EmergingMarketWatch forecast: Hold
BanRep is likely to hold its policy rate on Sep 30. That is not the decision implied by the data, but it is the most likely outcome given the political backdrop, a deeply divided board, and the unpredictable voting behavior of some members.
Markets have struggled to build a consensus on BanRep's policy decisions in 2026, and with good reason. The board has diverged from the pre-meeting consensus in four of five decisions this year. Former President Petro repeatedly criticized decisions backed by a narrow majority comprising Governor Leonardo Villar, Mauricio Villamizar, Olga Acosta and Bibiana Taboada. Former Finance Minister Germán Ávila unexpectedly walked out of the Mar 31 meeting, before the board surprised the market by holding the rate on Apr 30. The political uncertainty surrounding the board has made its decisions harder to forecast.
| BanRep 2026: Pre-meeting consensus vs. board decisions vs. EMW forecast | |||||||||||||||||||||||||||||||||||
| |||||||||||||||||||||||||||||||||||
| Source: EmergingMarketWatch; BanRep; Bloomberg; Reuters; press reports |
In our view, several factors will shape the Sep 30 decision, and they point in different directions, thus making the outcome hard to call:
- The finance minister, who chairs the board, has not publicly disclosed his monetary-policy position. His fiscal stance suggests a preference for orthodoxy and discipline, but it remains unclear whether he fully supports the central bank's technical team, led by Villar and backed by Villamizar. That group has favored a rate increase as inflation rises and components including services and food rebound.
- Two factors cut against an immediate hike. First, the Aug 10 earthquake prompted businesses and other borrowers to seek relief from the financial system. Some banks, including Bancolombia, the country's largest, lowered lending rates for affected clients. The government, through statements by the finance minister and President Abelardo de la Espriella, also coordinated with Asobancaria on assistance for borrowers.
- Second, July retail sales, industrial production and broader activity data were weaker than the market expected. The case made by Villar and Villamizar for front-loading rate increases rests on an economy growing at a robust and sustainable pace, with employment continuing to rise. The third quarter appears to have started weakly. The earthquake is also likely to weigh on activity, while employment could soften as hiring carried over from the previous administration loses momentum and the current government pursues austerity.
- One member broke with the narrow majority on Jul 31, leaving the board to hold the rate when the market had expected an increase. We believe that member was Olga Acosta, but it is unclear whether she will maintain that position or rejoin the majority. We read her vote as an attempt to prevent an excessive increase after policy tightening had outpaced the acceleration in inflation and the strong peso had encouraged carry trades at exporters' expense.
- The peso has weakened in recent days, potentially easing those concerns and making a return to rate increases more likely. The decision may hinge on whether the swing voter sees the depreciation as cyclical or structural, and on how that member assesses the policy rate's effect on the currency. The official exchange rate on Sep 24 was USD/COP 3,264, the highest level since before July 10. At the time of writing, the peso was trading near USD/COP 3,335 after touching 3,361 intraday.
Acosta is not the only potential swing vote. With Ávila no longer on the board and a new government in office, Laura Moisá and César Giraldo, particularly Moisá, are no longer bound to the dovish position favored by the Petro administration. The final vote therefore remains open.
On technical grounds, the continued rise in inflation and persistently high services prices would justify an increase of at least 100bps on Sep 30. Such a move would face backlash from several quarters. Exporters would be concerned that a wider interest-rate differential could renew carry-trade inflows and strengthen the peso. The interest-rate differential had narrowed only days earlier after rate increases by the Fed, the BoJ and the ECB. Higher borrowing costs would also draw opposition, particularly from borrowers affected by the earthquake. As a result, a hike appears unlikely, though it cannot be ruled out.
Overall, BanRep can hold the rate, but doing so would prolong the fight against inflation. El Niño would likely push food and energy prices higher, and the minimum-wage increase is still feeding into services prices. A hold would delay inflation's return to target and keep monetary policy tight for longer.
| Ask the editor | Back to contents |
| BCCR to decide on MPR amid persistent deflation and high external risks |
- MPR meeting: Sep 24, 2026
- Current policy rate: 3.00%
- EmergingMarketWatch forecast: 25bp cut or hold
Costa Rica's Central Bank (BCCR) is set to decide on the monetary policy rate (MPR) this Thurs., which is likely to be either another 25bp cut to 2.75% or a hold at 3.00% after delivering a cut at the previous meeting. The backdrop is marked by persistent deflation, economic deceleration, and elevated external risks stemming from the Middle East conflict and its impacts on US monetary policy.
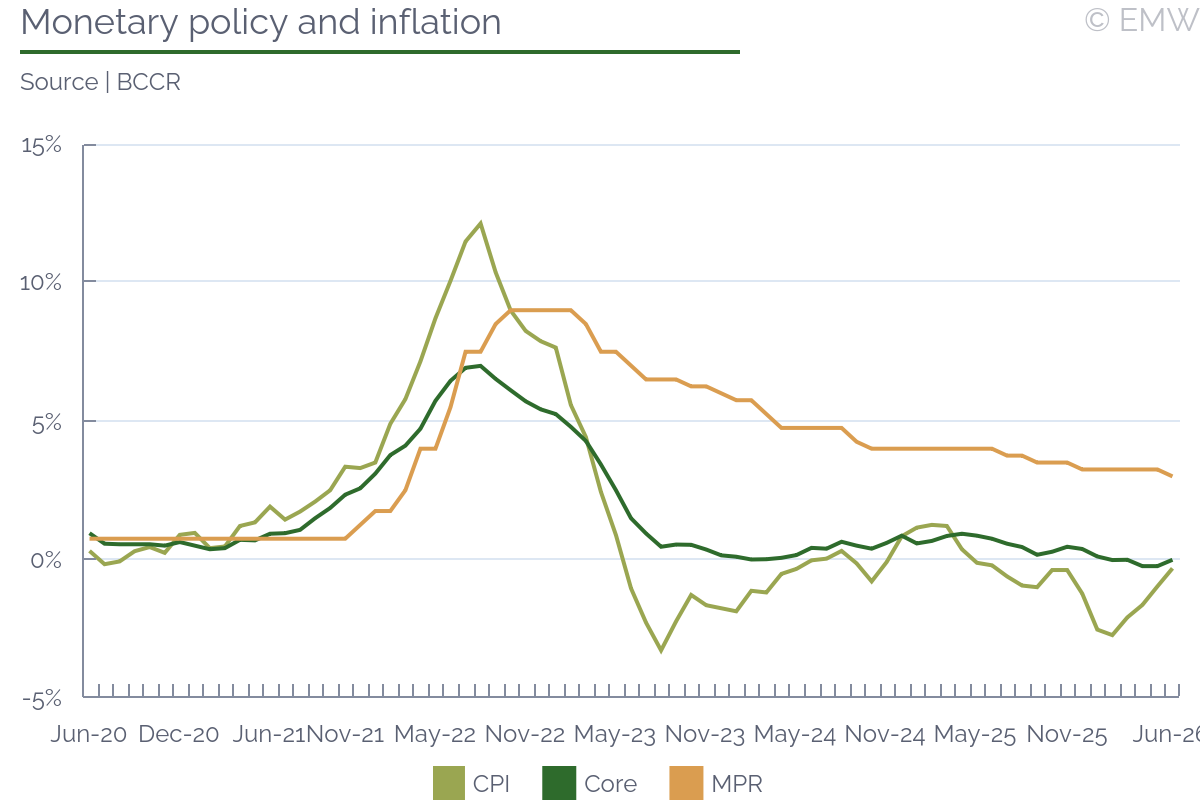
Looking at inflation, there are some mixed signals that could support either another cut or an MPR hold. CPI fell 0.11% m/m and 0.17% y/y in August, driven by lower fuel prices as the initial impact of the global energy shock began to dissipate. Although remaining persistently in negative territory, deflation narrowed from -0.28% y/y the month before, and core inflation rose to 0.0% y/y and 0.3% m/m in July. Meanwhile, inflation expectations remained within the 2.0%-4.0% band in July and August, though closer to the lower bound, which weighs in favor of an MPR hold.
Economic activity, in turn, is likely to weigh in favor of another MPR cut, in our view. Economic activity continued to decelerate in July amid moderate growth in free trade zones, rising 0.6% y/y. Although the month was marked by a high comparison base, as exports of medical devices posted exceptional growth in June and July 2025, it is a clear sign of the impacts of cooler external demand. In our view, economic deceleration, unanchored inflation expectations, and persistent deflation are the main factors that could prompt the BCCR to cut the MPR once again.
On the other hand, renewed tensions in the Middle East, which increased fuel prices, and US monetary policy could weigh against another cut. The recent decision by the US Federal Reserve to raise interest rates could pressure the BCCR to hold the MPR to mitigate FX depreciation, though the CRC has appreciated in recent months and could have room to depreciate without major shocks.
Overall, the previous MPR cut by the BCCR followed the recommendation from the bank's Economic Division, which suggested the cut due to decelerating economic growth, unanchored inflation expectations sitting below the 3.0% target, and persistent deflation. The division acknowledged elevated external risks, but noted that they did not have a significant impact on core inflation. In our view, the scenario remains broadly unchanged, which could support another MPR cut by the BCCR. However, the recent decision by the Fed to raise interest rates and renewed tensions in the Middle East could weigh in favor of a more cautious stance, thus prompting an MPR hold. We believe that the most likely decision is an MPR hold, but another cut cannot be ruled out, especially as the previous one was a surprise amid a hawkish tone by the committee and elevated external risks.
| Ask the editor | Back to contents |
| Inflation supports continuation of monetary easing so far |
- Current policy rate: 3.25%
- Next monetary policy meeting: Oct 21, 2026
- Expected decision: Hold or 25bps cut
The MPC continued the monetary easing on Sep 1 by cutting the policy rate for the third consecutive meeting and for the fifth time in the past year to 3.25%, the lowest level since November 2022. Deputy Bank of Israel (BoI) governor Andrew Abir explained that this was due to the continuing easing in inflation in July, in contrast to world developments and linked further monetary easing to the inflation developments and further gains of the shekel against the USD. The latest inflation figures for August came in lower than expected and thus support the monetary easing to continue but one more inflation release is due before the next MPC meeting so it is too early to make a reliable forecast what would happen next. Abir also noted that the benchmark interest rate may remain around its current level if the CPI inflation stabilises or edges up in the coming period. He added that the forthcoming general elections (due on Oct 27, less than one week after the next MPC meeting) would not have an effect on the decision.
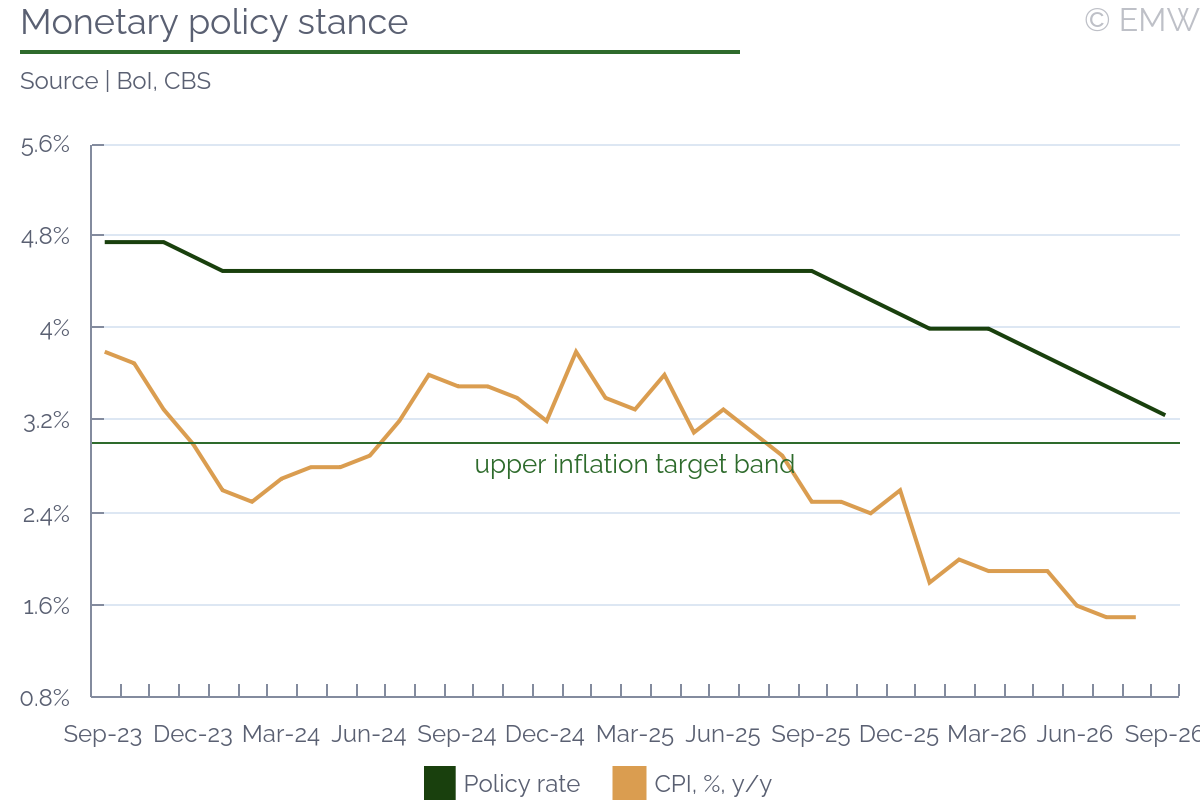
CPI inflation stabilised at 1.5% y/y in Jul-Aug, falling from 1.6% y/y in June and 1.9% y/y in Mar-May. The August print was lower than expected and might have been even lower had it not been for energy prices and flight tickets. It was also pulled down by the heavyweight housing component, which remains the major contributor to CPI developments in Israel, and when excluded, inflation has been even below the lower end of the 1-3% target range since June. BoI governor Yaron mentioned last month that expectations are for inflation to increase towards 2.0% in the coming months (which apparently failed to materialise in August), which is the centre of the target band. In the latest forecast from early July, the research department cut the inflation forecast to 1.8% y/y in Q4 2026 with the factors that can affect inflation in either direction being the geopolitical developments and their effects on economic activity and on energy prices, the risk premium and the exchange rate, the development of demand alongside supply constraints, and fiscal developments. Yaron warned that if the government eventually adds NIS 25bn more to the defence budget, in line with the demands of the defence establishment, this can boost inflation by 0.3pps in the next year.
GDP posted a strong recovery in Q2 jumping 14.9% in saar terms (seasonally-adjusted annualised rate), much higher than expected. Concerns that growth was supported by the activity of multinational companies, which was outside the country's borders, should have eased as they had a significantly lower effect in Q2, in line with BoI expectations that the growth base would expand with the release of reservists that eases supply constraints. Yaron assessed that GDP was very strong in Q2 but warned there were caveats addressing the above issue. The output was still below the pre-war potential but the gap was at just 1% from its pre-war long-term trend, the governor also stated. After the latest rate decision, deputy governor Abir said that the economic growth figure in Q2 is reasonable but not exceptional and that the BoI will carefully monitor the effects of the new policy rate cut on the economy and the reaction of the foreign exchange market. At the same time, finance ministry chief economist said that growth might be higher than 4%, the latest government official forecast. Thus, economic developments are rather neutral in taking monetary policy decisions.
Board statements, press briefings, minutes from MPC meetings
| Ask the editor | Back to contents |
| NBK cuts base rate by 50bps, sees limited scope for further easing |
- Current policy rate: 16.25%
- Next monetary policy meeting: Oct 23
- Expected decision: hold
On Sep 4 the NBK cut the base rate by 50bps (to 16.25%), following the 25bp cut delivered in July. It is not surprising that the bank chose to continue the easing cycle, though the ultimate cut was somewhat steeper than initially expected. We think the NBK chose to front-load the cycle with one decisive move, as opposed to relying on successive small cuts for the rest of the year. Overall, September's cut was based on the consistent deceleration of inflation in recent months and the moderation of household inflation expectations. At the same time, the NBK has said there is limited scope for further monetary easing.
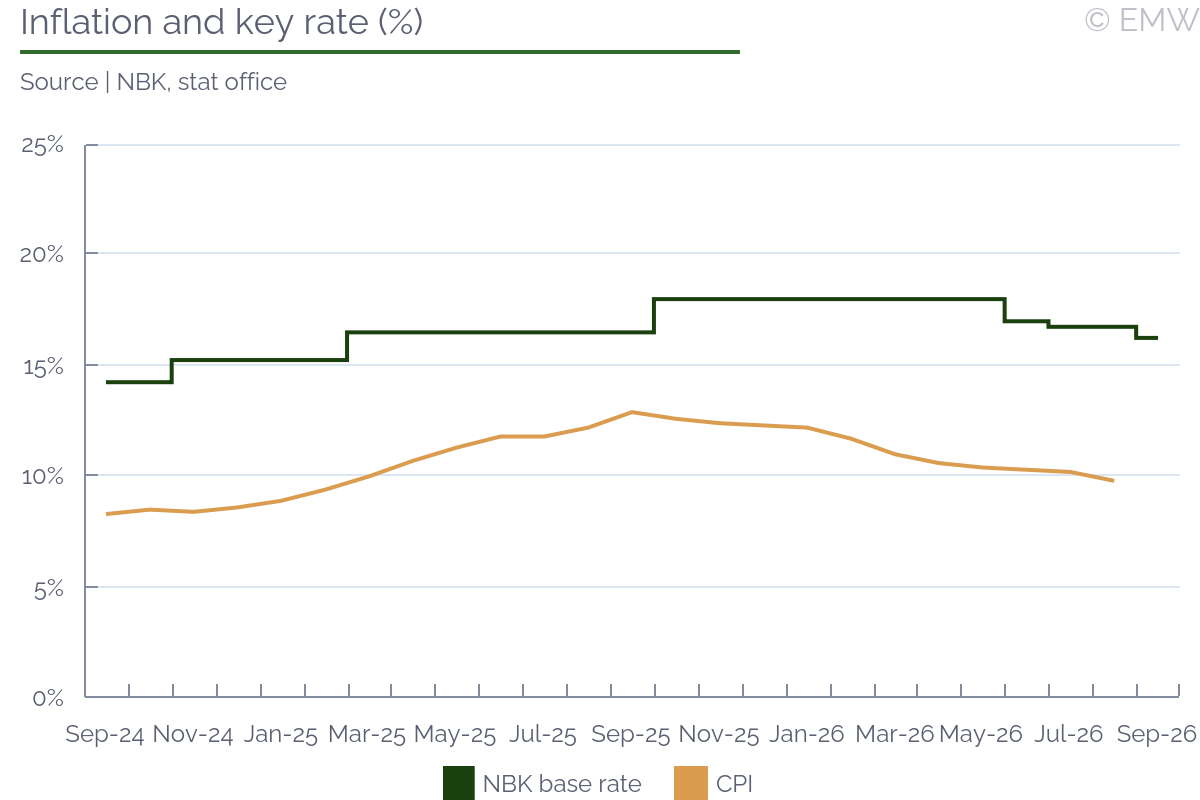
This stance reflects concerns about inflationary tendencies. Domestically, the main risks are related to demand trends amid a more active fiscal stimulus. Fuel prices, tariff amendments, and poorly anchored inflation expectations are among contributing factors as well. External risks stem from food and energy prices, according to the NBK. It has raised the year-end inflation forecast for 2027 to 6.5-8.5% (from 5.5-7.5%). The 5% medium-term target is only deemed achievable around end-2028 at this stage.
Looking forward, the NBK's comments indicate the easing cycle may be paused in October. In his earlier statements, governor Suleimenov signalled the base rate may be cut to 16% by the end of 2026, assuming favourable inflation dynamics. In this context, we do not completely exclude another small rate cut this year. Nevertheless, we believe the NBK will be even more sensitive to the balance of market factors, as the government's expansionary fiscal stance will affect inflation management in 2027.
| Ask the editor | Back to contents |
| BOK seems likely to hold rates steady in October, after rare back-to-back hikes |
- Next policy meeting: October 22
- Current policy stance: 3.00%
- Last decision: Aug 27 (25bps hike)
- Forecast: Hawkish hold
- Rationale: BOK executed rare back-to-back rate hikes framed as pre-emptive, inflation is expected to ease in September, yields are stabilising, as is the KRW/USD exchange rate
The Bank of Korea (BOK) is more likely than not to leave its policy rate unchanged at 3.00% on October 22, in our view, after raising rates by 25bps in two consecutive meetings. The August decision to hike again after July was backed by six of the seven Monetary Policy Board members, with Hwang Keon-il dissenting in favour of keeping the rate unchanged at 2.75%. The BOK justified the move with stronger-than-expected growth, inflation likely to remain above the 2% target for a considerable period, and persistent financial-stability risks. It also raised its 2026 GDP growth forecast sharply to 3.3% from 2.6%, while leaving headline CPI inflation at 2.7% for 2026 and 2.3% for 2027, but raising core inflation forecasts to 2.5% for both years.
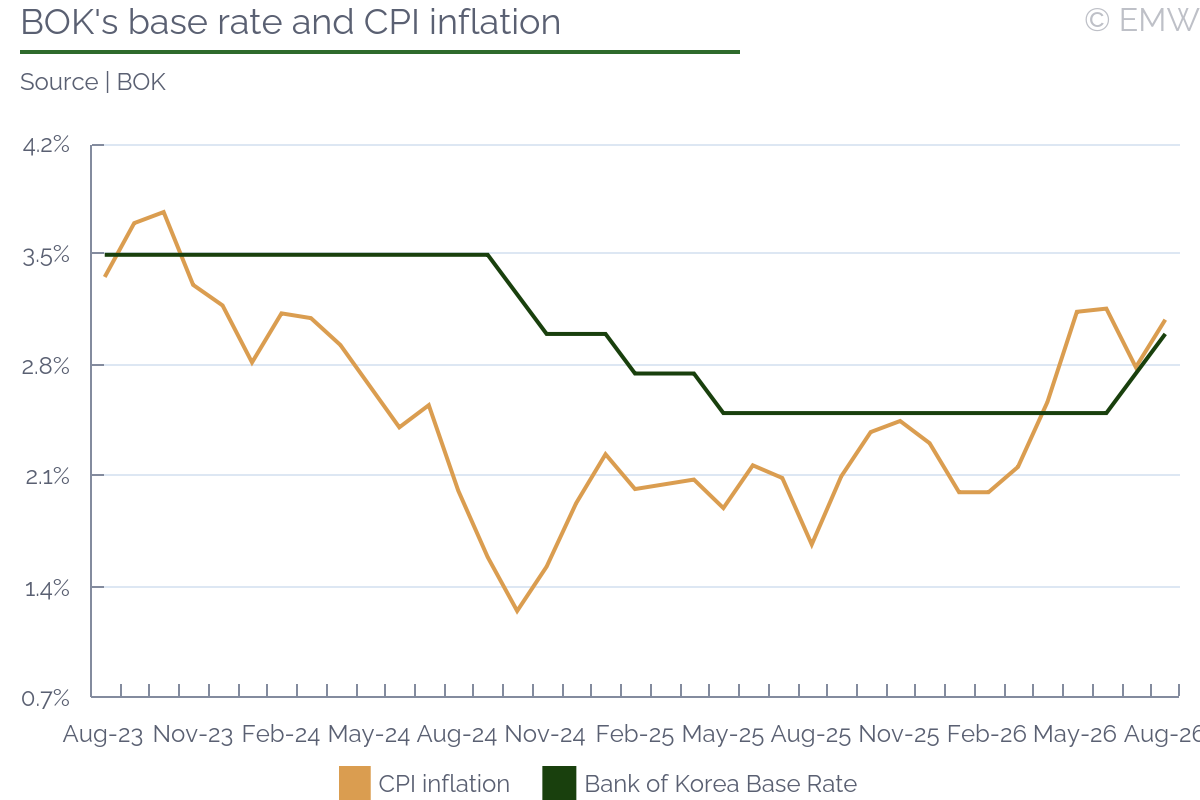
We note that Governor Shin Hyun-song's post-meeting message was hawkish but not very aggressive. He pointed to the dot plot median of 3.25% over the next six months, implying one more 25bps hike, and also suggested the tightening path ahead would be gradual. We think this signals that the BOK is more likely to wait before hiking again. The August dot plot showed 10 of 21 dots at 3.25%, six at 3.50%, and five at 3.00%, meaning most board-member scenarios included at least one more hike, but not necessarily immediately in October. Reuters reported after the August meeting that Korea Investment Securities' Ahn Jae-kyun saw the outcome as relatively dovish despite the hike and argued that the board would now hold steady in October. In our view, the cycle is not over, but the case for another back-to-back hike on October 22 is weaker than the case for maintaining hawkish optionality and waiting for more evidence.
Headline inflation has rebounded, but the signal is mixed
The strongest argument for another hike is the August CPI data. Headline inflation rose to 3.1% y/y in August from 2.8% in July, returning above 3% after just one month below that level. More importantly, CPI excluding food and energy accelerated to 3.4% y/y, while the index excluding agricultural products and petroleum rose 3.1% y/y. However, we would not interpret the August data as automatically forcing an October hike. The statistics office itself attributed part of the reacceleration to a base effect from telecom-fee discounts in August 2025, which pushed public-service inflation higher this year.
The key question for October will therefore be whether September CPI confirms that August's core acceleration was more than a one-off statistical distortion. If September headline inflation remains above 3% and core inflation stays near or above 3%, the case for a 25bps hike in October would strengthen materially. If the September data show some reversal of the telecom-related base effect and a moderation in underlying services or durable-goods inflation, the BOK can credibly argue that August's back-to-back hike should be given time to transmit.
Growth revised sharply higher
Based on growth alone, the case for continued tightening remains convincing. The BOK now expects the Korean economy to grow by 3.3% in 2026 and 2.9% in 2027, compared with previous forecasts of 2.6% and 2.1%, respectively. The central bank attributed the revision to the semiconductor boom, strong exports and investment, and a gradual broadening of the recovery into consumption as income conditions improve. Recent trade data support that assessment. August exports rose 68.7% y/y to USD 98.25bn, staying above USD 90bn for a third consecutive month, while semiconductor exports reached a record USD 46.65bn and increased by 209.0% y/y. The export cycle therefore continues to validate the BOK's upgraded growth view and increases the probability that stronger income and investment will feed into demand-side inflation.
At the same time, there are some early signs that the domestic demand impulse may not be uniformly strong. The BOK's August consumer sentiment index fell to 104.5 from the previous month, marking the first decline in four months, and housing-price expectations also eased modestly. This is not enough to make policy dovish, but it supports the argument that the board can pause in October while assessing whether tighter rates are already cooling parts of the economy.
Financial stabilityissues paint a mixed picture
Financial-stability risks remain the main reason an October hold would not be dovish. In its August statement, the BOK said capital-region housing prices continued to rise at a high pace and household loans had increased substantially. If housing prices and mortgage lending accelerate further through September and early October, the board could judge that a pause would undermine the financial-stability signal sent in July and August. But if household loan growth slows and the housing market becomes more mixed, the BOK can leave the policy rate unchanged while keeping the statement focused on housing and leverage risks.
FX developments are less urgent than they were before the July hike. In its August statement, the BOK noted that the USD/KRW rate had fallen significantly as FX supply conditions improved and the US dollar weakened. The strong export surplus also supports the won and reduces the imported-inflation argument for another immediate hike. This does not remove the BOK's FX sensitivity, but it lowers the probability that exchange-rate pressure alone forces action in October.
We think that market reaction also supports a hold baseline. Although the August hike and dot plot confirmed that the tightening cycle has not ended, Korean bond yields fell across the curve after the meeting as investors interpreted Shin's comments as pointing to a more gradual path rather than a rapid sequence of hikes. In other words, markets appear to have accepted that 3.25% is likely, but not necessarily that the move has to come at the October meeting.
Conclusion
Our baseline expectation for now is a hold at 3.00% on October 22, accompanied by distinctly hawkish communication and probably one or two dissenting votes for a 25bps increase. The BOK has already delivered two consecutive hikes, and the August decision was explicitly framed as pre-emptive action to reduce the eventual cost of controlling inflation. In our view, this gives the central bank room to wait in October, especially because Governor Shin has signalled gradual tightening and because the dot plot implies one more hike over a six-month horizon rather than at every meeting.
| Ask the editor | Back to contents |
| BNM to keep policy rate unchanged in November, but hike remains possible in 2027 |
- Next policy meeting: November 5, 2026
- Current policy rate: 2.75%
- Our forecast: Hold
- Last decision: Hold (Sep 3, 2026)
- Rationale: BNM gives no indication about an imminent rate hike in September policy statement
Bank Negara Malaysia (BNM) is likely to keep its interest rate unchanged in the last monetary policy meeting for the year on November 5, but a rate hike remains possible in early 2027, depending on the inflation and growth situation, in our view. BNM chose to keep the policy rate unchanged at 2.75% in the last meeting on Sep 3, keeping the policy rate unchanged for the 8th meeting in a row. Furthermore, the policy statement released after the meeting gave no indication about an imminent rate hike in November. BNM commented that inflation has been contained by "domestic policy measures and stable demand conditions amid limited spillover of external sector strength to wages."
At the same time, BNM hinted that changes to its policy stance are possible after it removed the word "appropriate" from the statement saying that the "MPC considers the monetary policy stance to be appropriate and consistent with the outlook of continued price stability." Overall, we think that the statement leaves BNM with plenty of flexibility to decide the future course of monetary policy, but at the same time, BNM showed no signs of being concerned about the inflation situation.
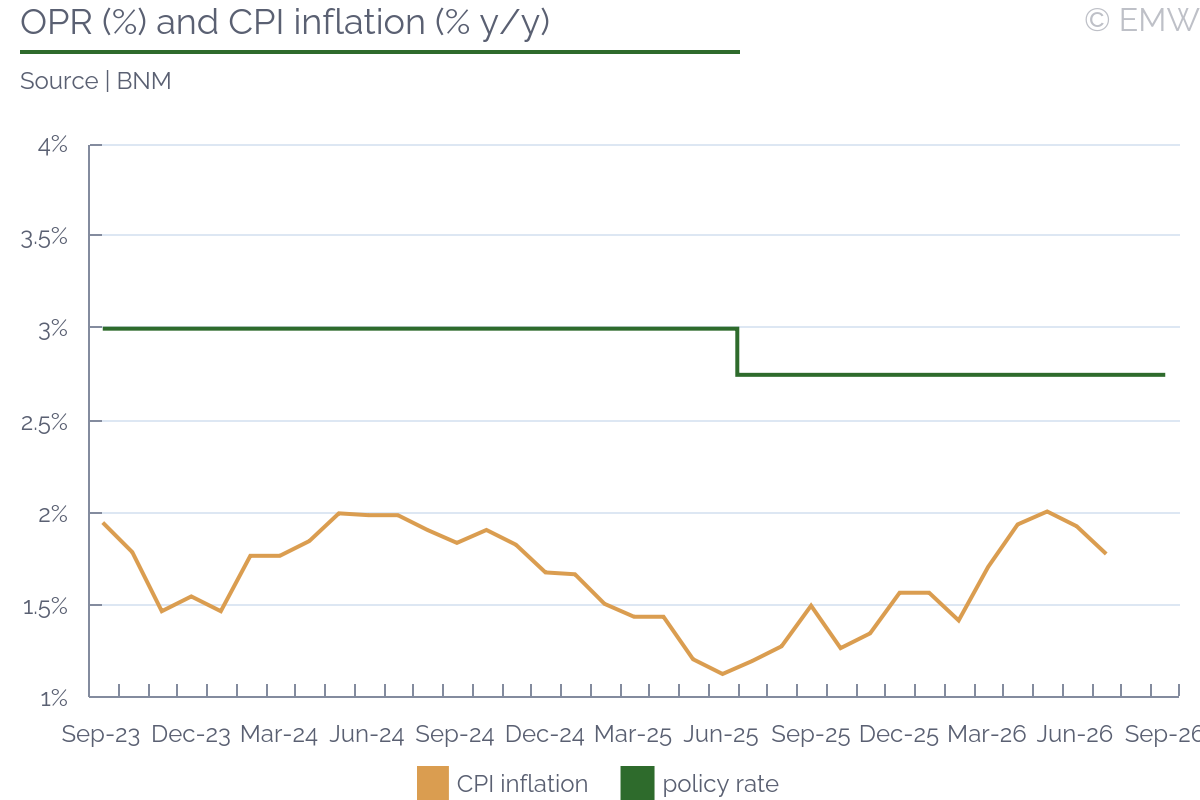
Inflation remains contained mainly thanks to fuel subsidies
The main factor that pushed BNM to stay on the sidelines so far in 2026 is the fact that headline inflation has remained contained (1.8% y/y in July) despite the energy price shock that occurred in Q1 and the strong growth reported in H1. In fact, CPI inflation has stayed at or below 2% since July 2023 as the government has been able to limit inflation movements mainly thanks to fuel subsidies. Transport price inflation peaked at 4.1% y/y in April before subsiding to 1.4% y/y in July as the government kept subsidised petrol prices unchanged throughout the energy crisis and expanded diesel subsidies in July.
Another factor that helps to explain the lacklustre inflation situation is the fact that the Malaysian economy has been mainly growing thanks to the booming semiconductor sector, which has limited impact on wage growth in the broader economy. Thus, demand pull inflation has remained rather contained, with core inflation standing at 1.8% y/y in July compared to 2.3% y/y at end-2025.
However, headline inflation continues to hide the build-up of inflationary pressures throughout the economy as PPI inflation rose by 9.7% y/y in July, the highest rate in more than 4 years. PPI inflation remained high in July on the back of surging crude material and intermediate material prices (up by 24.1% y/y and 8.4% y/y, respectively) because producer prices remain unaffected by government subsidy measures. Thus, we think that we may see pent-up price increases in the future, as producer price increases spill into final consumer prices, especially as the Iran war situation remains unresolved.
Economic data remains upbeat, driven by semiconductor upcycle
The Malaysian economy has benefited greatly from the semiconductor AI supercycle. GDP growth surprised on the upside in H1 2026, rising by 5.7% y/y. However, growth is expected to decelerate somewhat in Q3 due to high base effects. BNM now expects that GDP will rise by around 5% in 2026 compared to its previous forecast for growth in the 4-5% range.
Exports have surged by 17.0% y/y in Q2 led by rising demand for semiconductors. At the same time, both household consumption (up by 4.8% y/y) and gross fixed capital formation (up by 4.6% y/y) have remained relatively contained in Q2. Industrial production has remained upbeat throughout 2026, rising on average by 5.7% y/y in Jan-Jul. However, industrial production surprised on the downside in July when production rose by 4.7% y/y at the slowest pace in 4 months. This further reinforces our expectations that BNM will remain on hold in November.
Meanwhile, bank lending has continued to accelerate to 6.1% y/y in July, the highest level in 24 months. Total credit to the economy, which also includes corporate bonds, rose even more strongly by 6.5% y/y in July. Most of those loans are related to working capital needs which might have been dictated by the rising cost pressures felt by businesses. However, household lending has remained contained at 5.3% y/y in July, as households remain cautious to spend in the current economic environment. If credit growth continues to pick up, we think that this might be another factor that BNM will consider when setting rates.
Conclusion
Overall, we think that BNM is likely to keep rates unchanged for the time being, but a rate hike remains possible in early 2027 if growth and inflation data remain conducive to a rate hike. We think that BNM will raise rates in early 2027 if inflation moves tangibly higher than 2% in Q4 2026, or if GDP growth remains well above 5% in H2 2026. At the same time, we also see a possibility that BNM will keep the policy rate unchanged for an extended period of time regardless of the incoming economic data. It should be noted that BNM has made just 1 rate change over the past 3 years, which highlights that it remains comfortable with keeping the policy rate at the current level.
The main factor stabilizing the inflation outlook and monetary policy in Malaysia remains the government's generous fuel subsidy programme which effectively eliminates the impact of global oil prices on consumer prices. As the government has confirmed that it will keep fuel subsidies intact for the foreseeable future and will try to contain the cost of living pressures further in Budget 2027, we think that BNM remains in no rush to hike rates. If BNM decides to raise rates in early 2027, we think that a 25bps rate hike is all that it will do in the current environment.
Further Readings
| Ask the editor | Back to contents |
| MPC likely to hold at 9.25% as easing inflation offsets energy, climate risks |
Next MPC announcement: Sep 30, 2026
Current policy rate: 9.25%
EmergingMarketWatch forecast: 9.25%
The next MPC meeting is scheduled for today (Sep 30), and we think the committee will hold the MIMO rate at 9.25% as the sharper-than-expected easing in headline inflation provides room to wait while significant external and domestic risks remain elevated. Annual inflation fell to 6.45% y/y in August from 7.48% in July and 7.51% in June, while monthly inflation remained negative at -0.28% m/m and food and non-alcoholic beverages prices fell 1.1% m/m. Q2 GDP growth also improved to 1.74% y/y from 0.05% in Q1, although activity remains relatively subdued. The nominal policy rate therefore remains 2.80pps above headline inflation, while the MPC has already held rates at 9.25% since March after suspending its easing cycle amid heightened inflation risks. We therefore think the latest fall in inflation and still-weak activity will favour another hold rather than a resumption of easing at this meeting.
Inflation and monetary conditions
The principal argument for another hold is that domestic inflation momentum has weakened materially. Food and non-alcoholic beverages inflation slowed to 8.9% y/y in August from 12.6% in July, while transport inflation remained elevated at 14.8%. Food nevertheless accounted for 2.6pps of headline inflation and transport for 2.1pps, leaving both components important risks to the outlook. The moderation in food prices has therefore done much of the recent work in lowering headline inflation, while transport costs remain sticky following the large fuel-price adjustment earlier this year. At the same time, the 39% reserve requirement on domestic-currency deposits introduced in May has reduced metical liquidity and gives the BoM an additional tightening channel without another rate increase. The September prime rate also remained unchanged at 15.50%, indicating that broader domestic borrowing conditions remain relatively tight despite the earlier MIMO easing cycle.
The external backdrop nevertheless argues against restarting the easing cycle. Regulated fuel prices have remained at MZN 93.69/litre for petrol and MZN 116.25/litre for diesel since the May adjustment, limiting the immediate domestic pass-through from the latest increase in international oil prices. However, Brent crude rose to around USD 105/barrel on Sep 28 as US-Iran tensions intensified, while the FAO Food Price Index increased 1.9% m/m in August and its cereal component rose 2.2%. If the energy shock persists, higher fuel and freight costs could eventually feed into transport and imported food prices in Mozambique, particularly given transport's already large contribution to headline inflation. The risk is therefore less about an immediate second fuel-price increase and more about a renewed external shock interrupting the current disinflation trend.
External risks and policy trade-offs
The foreign-exchange environment provides some counterweight to these risks. The metical remained broadly stable, with the BoM's reference rate at 63.91 MZN/USD on Sep 29, while the central bank has reported improved FX-market liquidity supported by activity in the extractive sector. Continued exchange-rate stability should help contain imported inflation and gives the MPC some room to wait for clearer evidence on whether the recent external energy shock is persistent. However, fiscal and external pressures remain significant. The IMF's September mission highlighted large fiscal and external imbalances, tight financing conditions and the need for further reforms to restore debt sustainability. Mozambique's latest public-debt data also put central-government debt at MZN 1.11tn, equivalent to 73.6% of GDP, at end-June. These conditions make a rapid return to monetary easing less attractive because any renewed pressure on the metical could complicate imported-inflation management.
Looking ahead, the MPC is also likely to retain a cautious bias because of the emerging climate shock. Mozambique's disaster-management authorities said on Sep 21 that a strong El Niño had consolidated, with the potential to become one of the strongest episodes since 1950. The critical period is expected to run from October this year to February 2027, with a significant precipitation deficit expected particularly during January-March 2027. The risk is relevant for monetary policy because weaker agricultural output and tighter water availability could push food prices higher after the recent decline, while the broader climate shock could also weigh on economic activity. The BoM itself had previously identified climate shocks, higher domestic fuel prices, fiscal risks and the Middle East conflict as key uncertainties around its inflation projections. We therefore expect the MPC to retain the 9.25% rate and cautious guidance, with the combination of contained current inflation and weak activity arguing against a hike, but external, fiscal and climate risks limiting the case for an immediate rate cut.
Previous Monetary Policy Committee Communique No. 4/2026
| Ask the editor | Back to contents |
| NBR to consider rate cuts no sooner than early 2027 as inflation stays high |
- Next MPC meeting: Oct 8, 2026
- Current policy rate: 6.50%
- EmergingMarketWatch forecast: Hold
Rationale: Romania's central bank is very likely to keep the key policy rate at 6.50% at the Oct 8 MPC meeting and wait at least until early 2027 before considering a cut, in our view. This was also suggested by NBR Governor Mugur Isarescu during the presentation of the latest Inflation Report on Aug 13. He stressed high uncertainties regarding the inflation outlook and noted that a key rate cut could be considered when inflation drops below the monetary policy rate. Since the Inflation Report revised the end-year forecast upward to 6.1% from 5.5%, we assume that rate cuts will be discussed in early 2027.
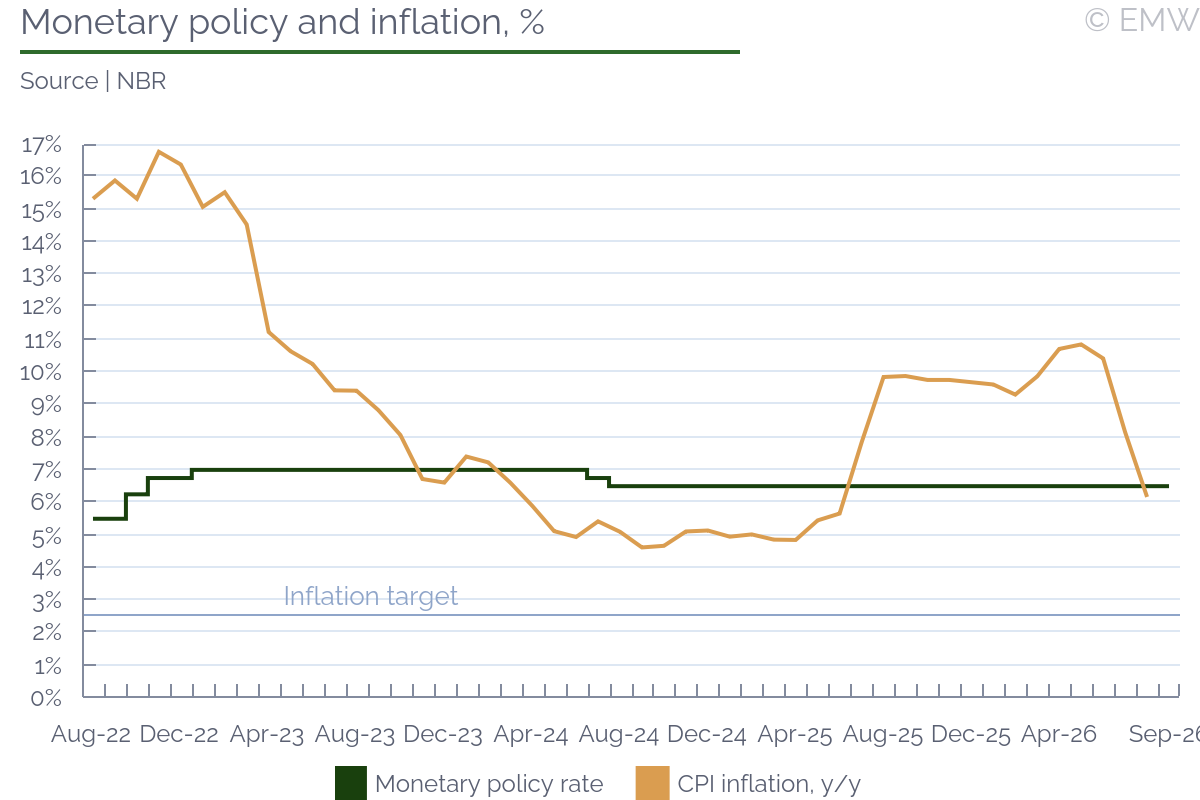
Inflation remained persistently high, driven by rising fuel prices following the Iran conflict and a renewed spike in domestic uncertainty after the political crisis. The NBR revised its end-year inflation forecast upward mainly due to the effects of the severe drought on electricity prices, stronger CORE2 inflation and a bigger contribution from administered prices. It's true that the CPI growth slowed sharply, more than expected, to 6.17% y/y in August, putting a rate cut on the NBR board's agenda. Yet, inflation must show signs of consolidating below the policy rate before the NBR considers a cut, as Isarescu suggested.
The central bank kept the policy rate unchanged at the Aug 10 MPC meeting, reflecting a sharp deterioration in the short-term inflation outlook following the escalation of the Middle East conflict and the resulting surge in global energy prices. According to the NBR, the balance of risks has shifted decisively upward, with inflation having remained above 10% until June, levels higher than previously anticipated due to fuels and elevated oil and gas prices.
The NBR expects inflation to sharply moderate in Q3 and fluctuate throughout the remainder of the year, on a higher path than previously anticipated. The central bank sees inflation entering the upper band of the target interval toward the end of 2027. As a result, market expectations have adjusted once more, with most economists no longer anticipating cuts in 2026.
| Ask the editor | Back to contents |
| Inflation and fiscal uncertainty remain key arguments against further rate cuts |
- Current policy rate: 14.0%
- Next monetary policy committee meeting: Sep 11
- Expected decision: hold
The market is almost unanimous that the CBR will keep the policy rate unchanged after a long period of continuous cuts, and we find ourselves in this majority, even though the CBR has continued in recent years to surprise the market. Several classic indicators support keeping the rate unchanged at this meeting. Inflation has accelerated, corporate and household lending activity is increasing, the fiscal impulse remains in place and external risks remain high. At the same time, the gradual cooling of the labor market, slower wage growth, and the slowdown in economic activity, also speak against further easing. In addition, based on the standard fiscal process in Russia, by the time of the October meeting the CBR will have fresh fiscal projections and an updated economic outlook for next year. Therefore, it would be more reasonable to decide on any change in the rate-cutting path in October. Despite these arguments, we note that the CBR prefers to describe the factors driving inflation as one-off in its comments. In addition, last year, despite similar fiscal conditions, the CBR still decided to cut the key rate.
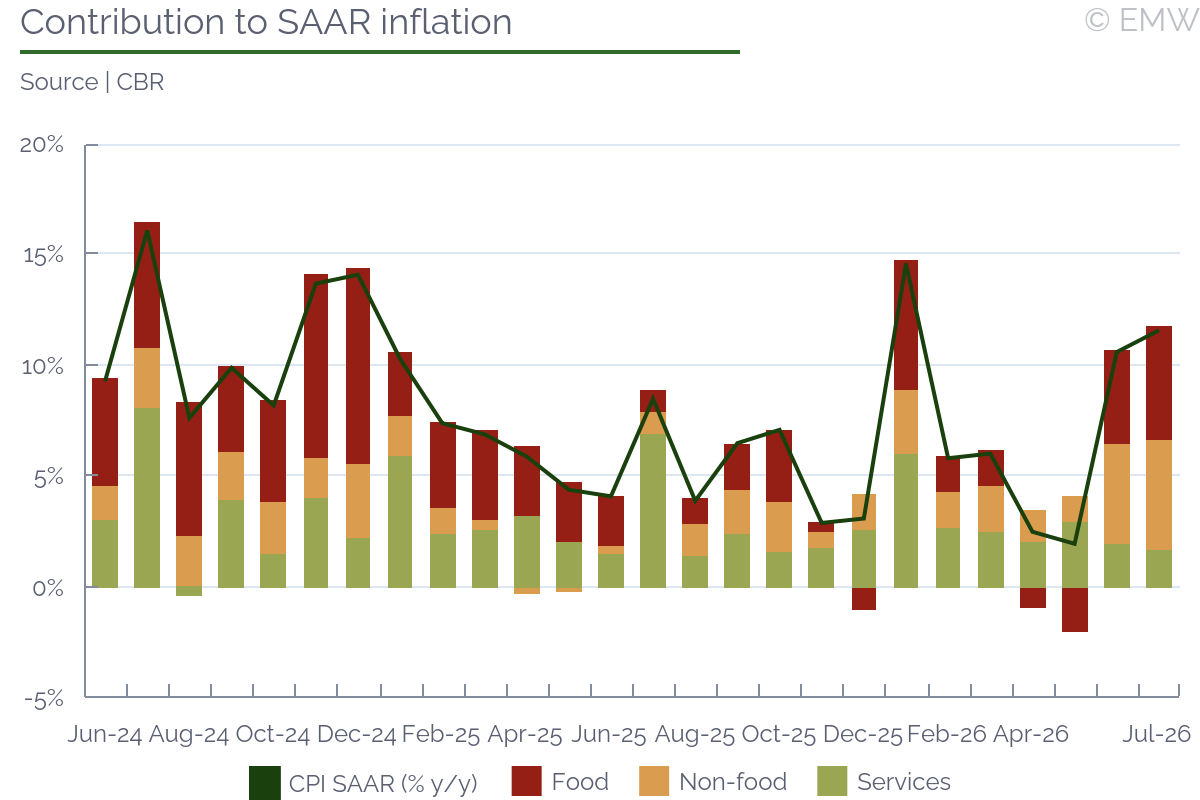
One big argument for keeping the rate unchanged is the inflation trend. The inflation picture has clearly not improved since July and has rather worsened. SAAR inflation accelerated to 11.6% in July from 10.6% in June and just 2% in May, but full August data will not yet be available by the time of the meeting. The annual non-seasonally adjusted print increased to 6.0% y/y in July, while underlying inflation is moving closer to 5%. The business sector's inflation expectations increased to 5.5% on average over the last three months, while those of households eased marginally to 13.7% in August and 13.6% on average over three months, but remain elevated. At the same time, we note the unusual nature of the current inflation. Clearly, the CBR understands that classic monetary policy measures currently have limited effect as the main drivers are the fuel market crisis and volatility around further RUB depreciation.
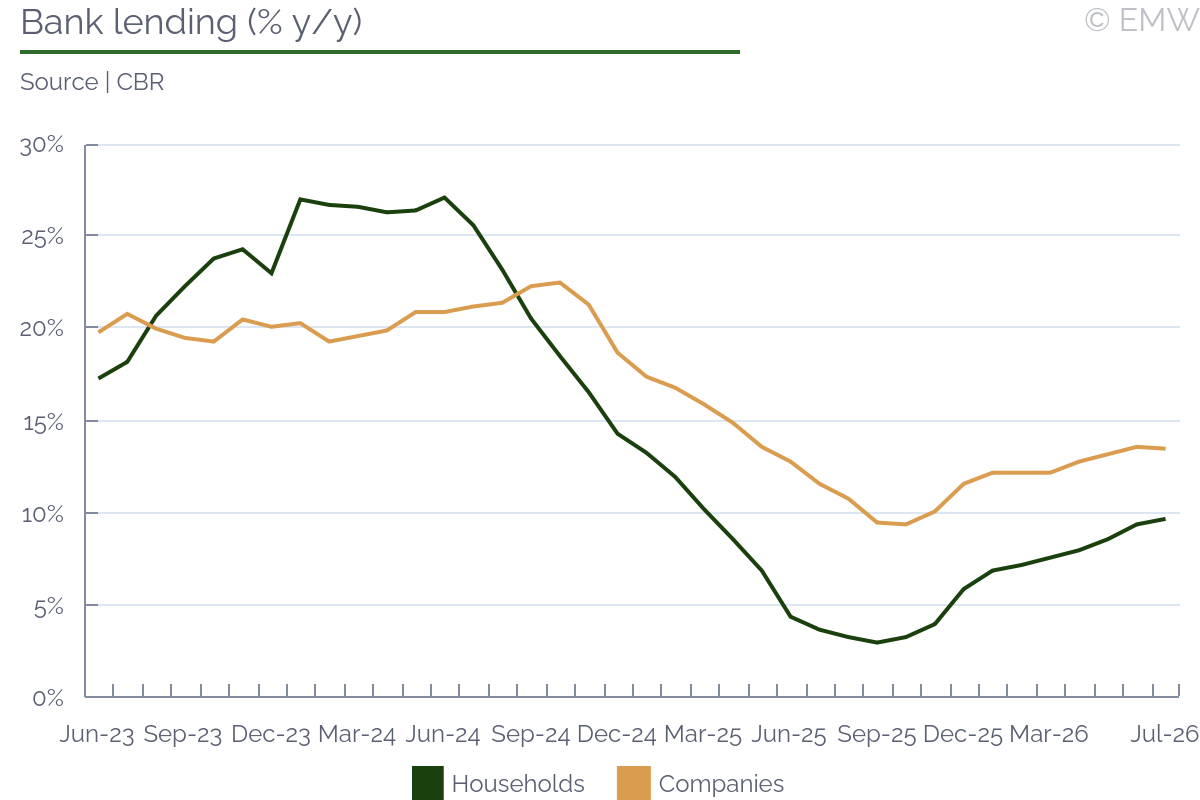
Another argument for no further easing is bank lending. Corporate lending grew by 13.5%-13.6% y/y in June-July, the fastest since the first months of 2025. We recall that this was when the CBR started the current rate-cutting cycle. While August data is not yet published, we expect the trend to remain largely unchanged. Household lending also accelerated further to 9.7% y/y in July, the fastest since last March. That reflects not only slower wage growth combined with higher prices, but also continued demand. The CBR admitted long ago that the policy rate has less direct influence on lending due to the share of lending supported by government demand and subsidized programs. Still, it affects consumer behavior. As for the corporate segment, which was a triggering indicator for much longer than the consumer segment, we believe that keeping the rate unchanged could now slow demand in the short term, as companies see that the CBR will likely return to rate cuts at some point and may prefer to wait for more favorable conditions.
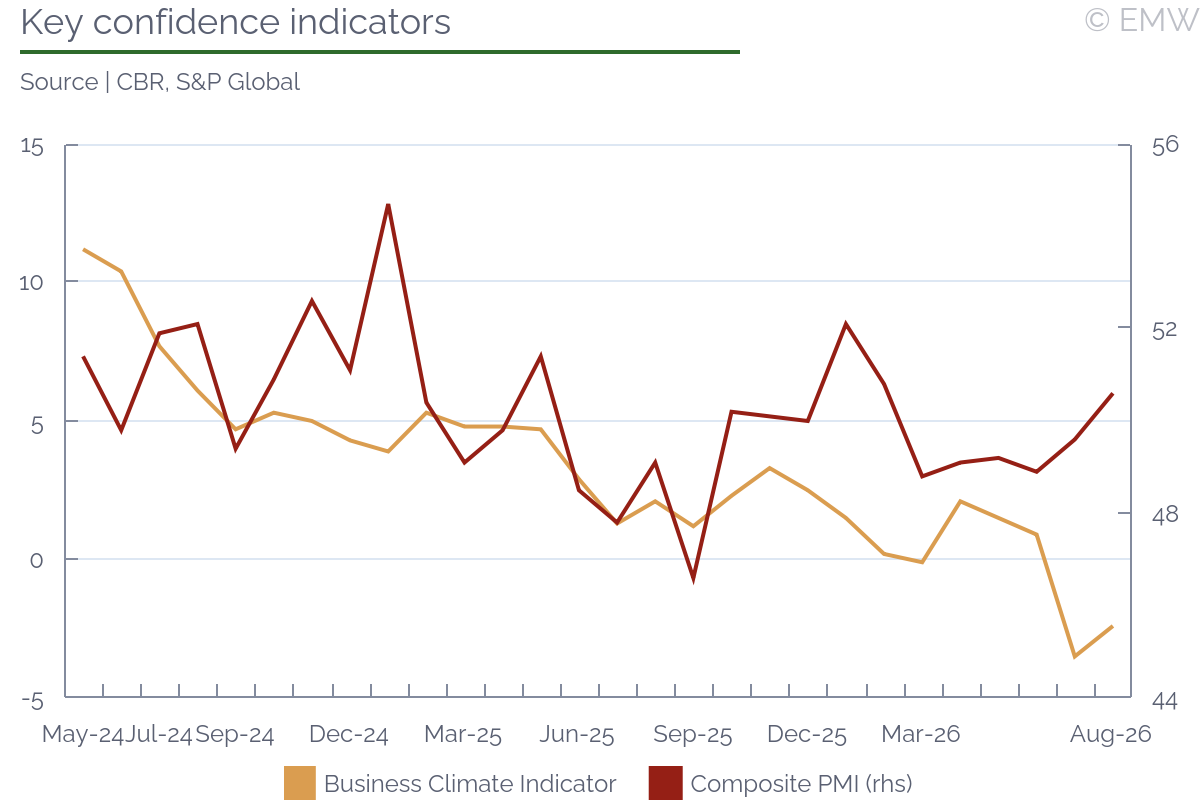
Arguments to ease monetary policy further come from the real sector, which is putting pressure on the CBR to accelerate rate cuts. GDP growth slowed to 0.6% y/y in July vs. 1.7% y/y in June. Industry growth also slowed to 0.4% y/y, supported almost exclusively by manufacturing due to defense-related output. Retail sales growth remains relatively strong, but is also slowing, at 5.3% y/y, as real wages have started to decline and the labor market is cooling. In addition, consumer sentiment and expectations are becoming more negative. Real wages were up by 3.4% y/y in June, the lowest since December, while nominal wages climbed above the RUB 114,000 mark (outside of December, when wages are much higher due to bonus payments). The unemployment rate shows some signs of normalization, reaching 2.3% from the 2.1-2.2% levels observed for several years. At the same time, there are stronger indirect signs that actual unemployment is rising faster. PMI and BCI surveys show a decline in labor demand, which could ease some of the pressure. That said, the economy is certainly cooling, raising concerns about whether this slowdown is manageable under continued war conditions. The CBR faces a choice between accepting this slowdown and trying to reverse it.
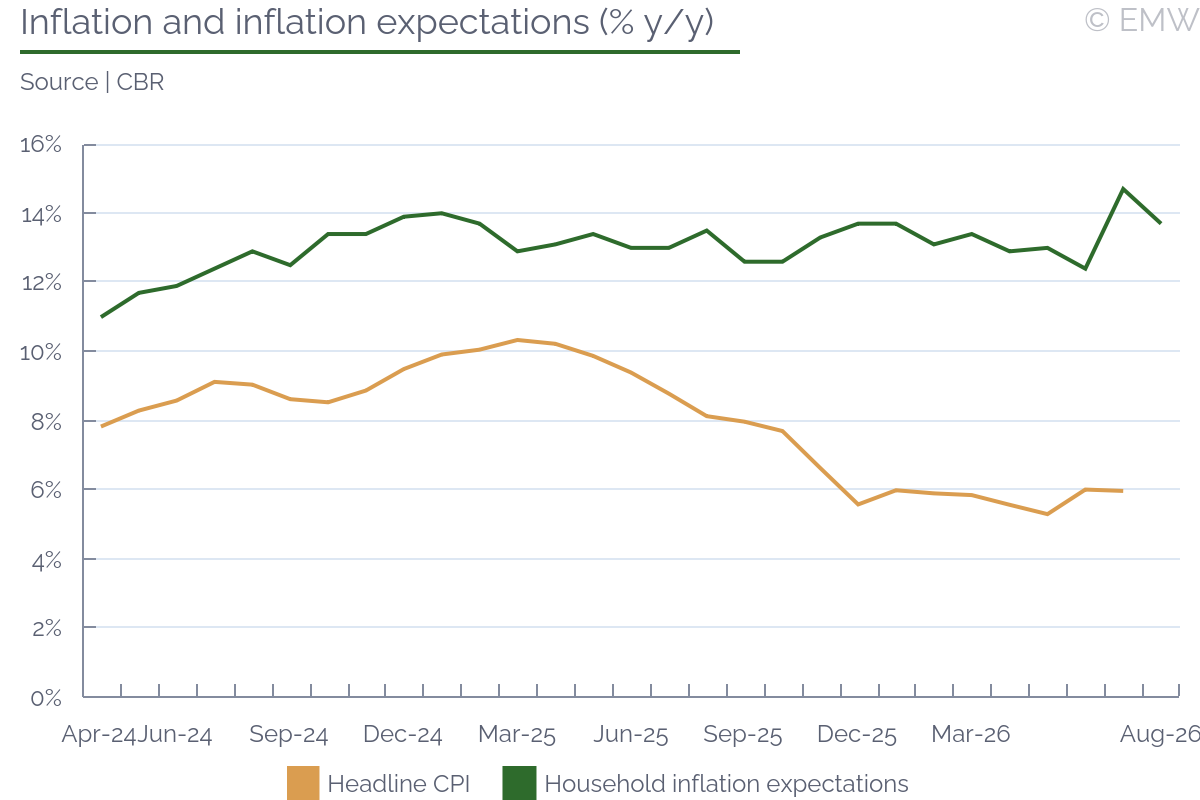
External political and economic factors also generally favor a hold. The ruble has weakened about 16% from the peak levels seen in May-June, bringing the exchange rate to levels that are more comfortable for the government. Although the latest spike in oil prices can support the ruble, it is difficult to predict how long oil prices will remain at current levels and the CBR may ignore them. It is also important to note that the CBR does not publicly support the importance of RUB depreciation for maintaining export revenues. Regarding the political situation, negotiations with the US do not promise any major surprises and will not change CBR's view that war-related high fiscal spending will remain in place for now.
| Ask the editor | Back to contents |
| NBS to hold rate at 5.75% on energy risks, expected low-base-led inflation spurt |
- Next MPC meeting: Oct 8
- Current policy rate: 5.75%
- EmergingMarketWatch forecast: Hold
- Rationale: central bank to remain cautious on high global energy prices, uncertainty in domestic energy sector, with inflation likely to speed up from September due to low base effects
The NBS is likely to keep the key policy interest rate unchanged at 5.75% at its Oct 8 sitting due to higher global energy prices, uncertainty related to the domestic energy sector, including oil company NIS and the gas arrangement with Russia, but also because inflation is projected to accelerate from September on low base effects.
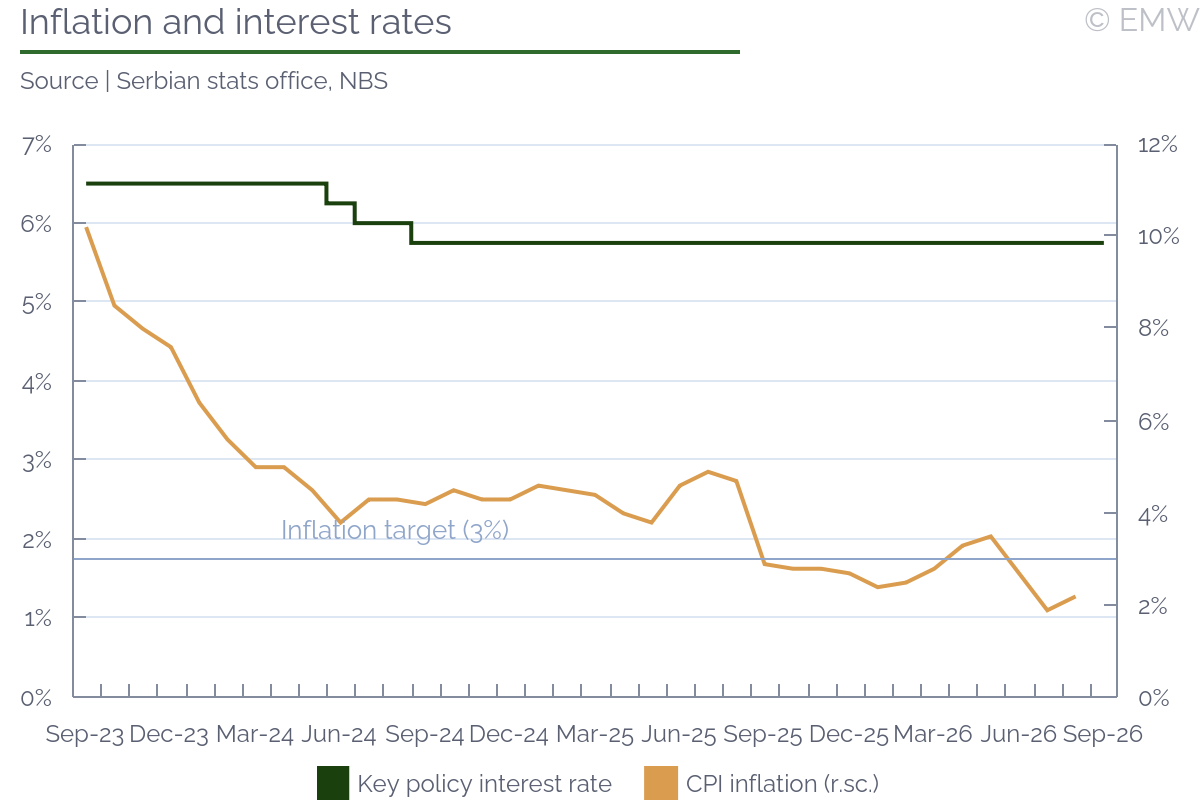
On Sep 10, the NBS Board held the key policy rate amid elevated uncertainty related to the Middle East conflict. In the rationale, the central bank said that the effects of an oil price spike on the domestic market have been softened by the use of available energy inventories and a cut in fuel excise duties. Nevertheless, the central bank admitted that if the Middle East conflict persisted or geopolitical tensions escalated further, it could spill over to production and transport costs, supply chains, capital flows, and inflation. The Board reiterated that it stood ready to use all available instruments should global oil prices have more pronounced second-round effects on other prices through inflation expectations.
So far, the impact of the global oil price shock has been milder than expected thanks to the government's measures, including price caps, a ban on oil exports, and a release of diesel from state reserves. The inflation expectations of the financial sector and firms, as well as of households, remain anchored. The financial sector's one-year inflation expectations stagnated m/m at 3.5% in August, thus being within the NBS's tolerance band (3%+/-1.5pps), those of the business sector were unchanged m/m at 5%, while those of households, which are usually higher than those of the other sectors, stagnated m/m at 10% in August.
CPI inflation accelerated to 2.2% y/y in August from 1.9% y/y the previous month, but remained below the NBS's target mid-point of the tolerance band. The main upward pressure on headline inflation came from transport prices, while food prices continued to fall thanks to the extremely good harvest, thus preventing a stronger inflation acceleration. The NBS continues to expect that this year's domestic agricultural season will be better than the preceding two below-average seasons, meaning further downward pressures on food prices. Under the NBS's August projection, average inflation this year will be lower than projected in May and is expected to stay within the target band over the next two years. Still, the NBS expects that from September, inflation will run around 4% y/y, reflecting a low base effect from last year's cap on retail prices and rising global energy and commodity prices.
The NBS does not seem concerned with demand-driven inflationary pressures. GDP growth surprised on the upside in Q2, accelerating to 3.8% y/y from 3.2% y/y in Q1, driven by fixed investments and household consumption. Yet, the stronger increase in investments is generally of a one-off character, reflecting the acceleration of Expo-related project implementation, while household consumption growth eased in the quarter albeit remaining robust. The central bank has revised up the 2026 GDP growth projection to 3.2% on a better-than-expected outturn in H1.
The central bank is also not concerned with the one-off aid provided by the government in September, ahead of the Oct 25 early general election, saying that it will not affect inflation in the long term. The NBS said that aid payments were fully accounted for in the August projection, which forecasts average inflation of 3.2% this year. Thus, apparently, the NBS does not currently see a risk to the inflation projection coming from public finances that would require a tightening of its monetary stance.
| Ask the editor | Back to contents |
| October fuel shock worsens inflation outlook, pressuring MPC response |
Next MPC announcement: Sep 23, 2026
Current policy rate: 7.00%
EmergingMarketWatch forecast: 7.25%
We now expect the SARB to raise the repo rate by 25bps to 7.25% at its Sep 23 meeting, as the balance of risks has continued to deteriorate and increasingly shifted against another hold. A further 25bps hike in November is also becoming more likely, although this will depend on the final October fuel price adjustment, whether the government provides renewed fuel price relief and the extent to which the shock feeds into inflation expectations and underlying prices.
The argument for tightening has strengthened substantially since the July MPC meeting due to the renewed surge in domestic fuel prices. What is shaping to be a relatively benign August inflation print is likely to turn into a much more unfavorable inflation profile in Q4. This comes alongside the Fed's decision on Sep 16 to raise rates by 25bps to 3.75-4.00% and signal that further tightening is likely. This could put pressure on the rand at exactly the moment that the economy is facing a large external inflation shock.
We expect August CPI, released on the morning of the MPC decision, to ease marginally from 4.3% y/y in July. However, the easing in July was mostly driven by the decline in fuel prices and the weak food inflation print of only 0.9% y/y. Meanwhile, the core inflation edged up to 4.2% y/y from 4.1% y/y, while services inflation remained elevated at 5.0% y/y.
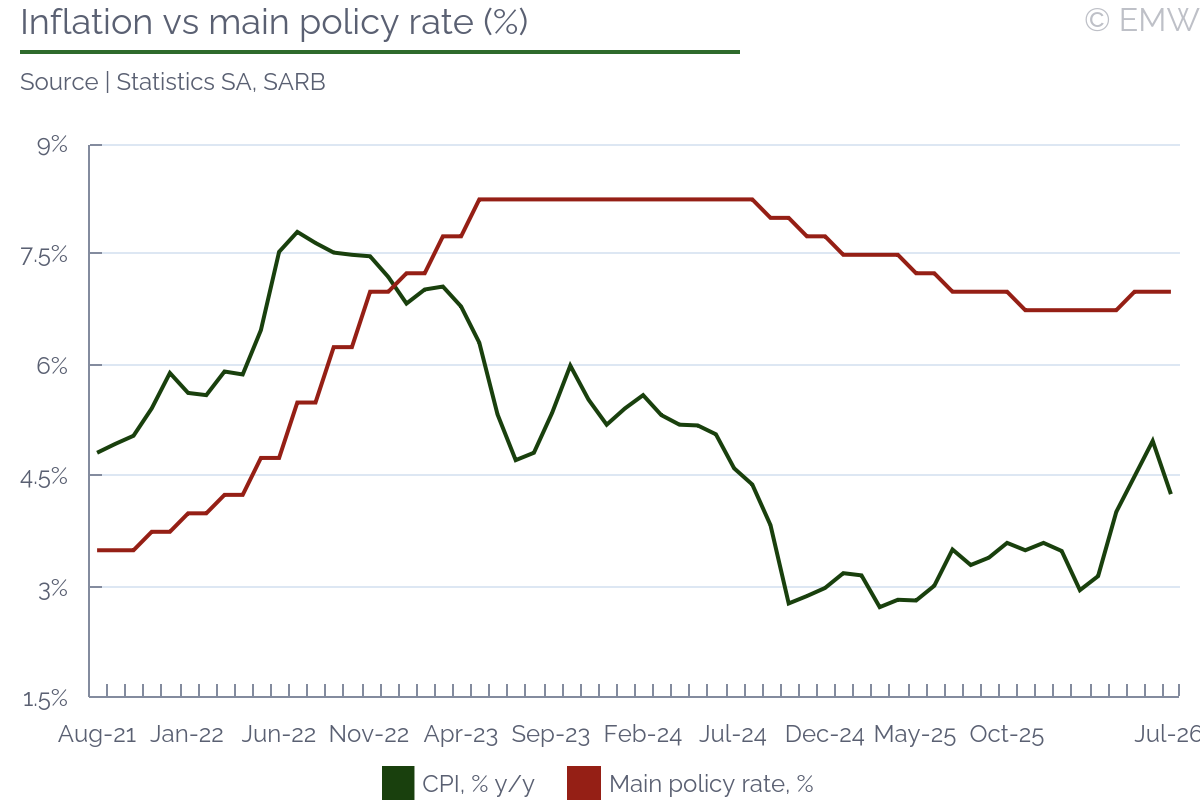
The fuel price outlook has deteriorated sharply since then. Petrol prices increased by ZAR 1.34/l in September and the latest daily recovery data now point to another increase of about ZAR 2.6/l in October. At current under-recoveries, inland 95-octane petrol would rise from ZAR 26.92/l to around ZAR 29.54/l, an increase of almost 10% m/m. In our forecasts, headline inflation will rise to around 5.0% y/y in October and averages around 5.0% y/y in Q4. That would place inflation 2pps above the 3% target and around 1ppt above the upper end of the SARB's tolerance. More importantly, the shock would extend into 2027 through base effects and potentially through second-round price and wage adjustments.
This is increasingly close to the adverse scenario the SARB presented in July. That scenario assumed oil averaging USD 100/bbl in 2026 and produced persistently above-target inflation, spillovers into food and core prices and one additional rate hike in 2026, followed by a longer period of restrictive policy. While Brent eased over the most recent sessions, it still remains around USD 102.7/bbl and the oil assumption in the SARB's adverse scenario no longer looks particularly extreme. It is worth noting that the rand remains considerably more resilient than the SARB's adverse scenario, while exceptionally low food prices and limited evidence of a broad second-round pass-through provide some cushion. Still, the probability that the adverse scenario begins to materialise has increased substantially.
The Q3 BER inflation expectations among analysts, businesses and trade unions for 2026 remained unchanged at 4.4% and the 2027 expectation declined to 4.0% from 4.2%, the 2028 estimate eased to 3.8% from 3.9% and the five-year expectation slipped to 4.0% from 4.1%. Household expectations improved much more sharply, with the one-year measure falling to 4.9% from 6.0% and the five-year measure declining to 8.3% from 9.1%, providing some reassurance. However, the SARB would likely place less weight on these readings compared to normal because this could be seen largely as a response to the decline in July fuel prices. It is likely for expectations to be impacted adversely once fuel prices approach ZAR 30/l.
Finance minister Godongwana said this week that, despite having forgone around ZAR 18bn because of the fuel subsidy intervention, revenue remains on track and the government's debt-consolidation programme remains intact. It cannot be ruled out that the Treasury decides to provide additional relief but that cannot be incorporated into the baseline at this stage. Godongwana has previously warned that permanently offsetting fuel increases through the budget would simply shift the burden to higher taxes, lower spending elsewhere or additional borrowing. Mineral and petroleum resources minister Gwede Mantashe also said this week that no new intervention is currently planned.
Although the SARB would be vigilant against risks on the inflation target, signals from the real economy were not particularly encouraging in Q2 with a GDP contraction of 0.1% q/q s.a. and subdued business confidence, while consumer confidence managed a modest recovery. This means that a September hike is unlikely to be the start if aggressive tightening cycle. The combination of an exceptionally large October fuel-price increase, inflation around 5% through Q4 and a more hawkish global rate environment could mean that the two MPC members that supported a 25bps hike in July could now get support from others. We would also see a further 25bps increase in November as increasingly likely as the key concern for the MPC becomes whether allowing inflation to remain at around 5.0% into year-end risks undoing the fragile improvement in expectations.
Monetary Policy Committee Statement
| Ask the editor | Back to contents |
| CBSL to hold rates in September despite inflation edging higher |
- Next policy meeting: Sep 30
- Current policy rate: 8.75%
- Our forecast: Hold
- Last decision: Hold (Aug 19)
- Rationale: Inflation remains near target band, despite mounting pressure on rupee
The Central Bank of Sri Lanka (CBSL) kept the Overnight Policy Rate unchanged at 8.75% on Aug 19, following the front-loaded 100bps increase delivered in May. The next Monetary Policy Board meeting is scheduled for Sep 29, with the decision due on Sep 30. The case for another increase remains weak despite a further rise in headline inflation. Governor P. Nandalal Weerasinghe said in August that the CBSL saw no need for additional rate hikes in 2026 under its baseline, describing the May move as proactive and indicating that future action would depend on whether inflation materially deviates from the expected path. The August Monetary Policy Report supports this interpretation. The CBSL expects inflation to remain elevated in the near term before converging towards the 5% target, while private-sector credit growth should moderate as recent monetary and macroprudential measures take effect. The central bank continues to describe the external sector as resilient, although geopolitical and weather-related risks remain significant.
The IMF's latest mission assessment also points towards policy continuity rather than another immediate tightening step. The Fund has stressed that monetary policy should remain prudent and data-dependent, while noting that the economy has remained resilient, reserves have strengthened and inflation expectations remain broadly anchored.
Inflation Outlook
Inflation has moved somewhat higher than at the July meeting. CCPI inflation accelerated to 8.0% y/y in August from 7.3% in July, while national NCPI inflation reached 8.1% y/y from 7.2%. Both measures are now above the upper end of the CBSL's 5%±2pp target band. However, the composition remains important. The increase in CCPI inflation was driven primarily by food inflation, which accelerated to 8.5% y/y from 6.3% in July, partly because of base effects. Non-food inflation eased marginally to 7.7% y/y from 7.8% in July. Core CCPI inflation rose to 5.1% y/y in August from 4.4% y/y in July, suggesting underlying pressures are increasing but remain considerably below headline inflation. The national measure shows a similar, though not identical, picture. NCPI food inflation increased to 6.6% y/y from 4.9% y/y in July, while non-food inflation edged up to 9.3% y/y in August. On a monthly basis, the overall NCPI increased only 0.26% in August, suggesting that the sharp annual headline increase partly reflects earlier price adjustments and base effects rather than a fresh acceleration in monthly price momentum.
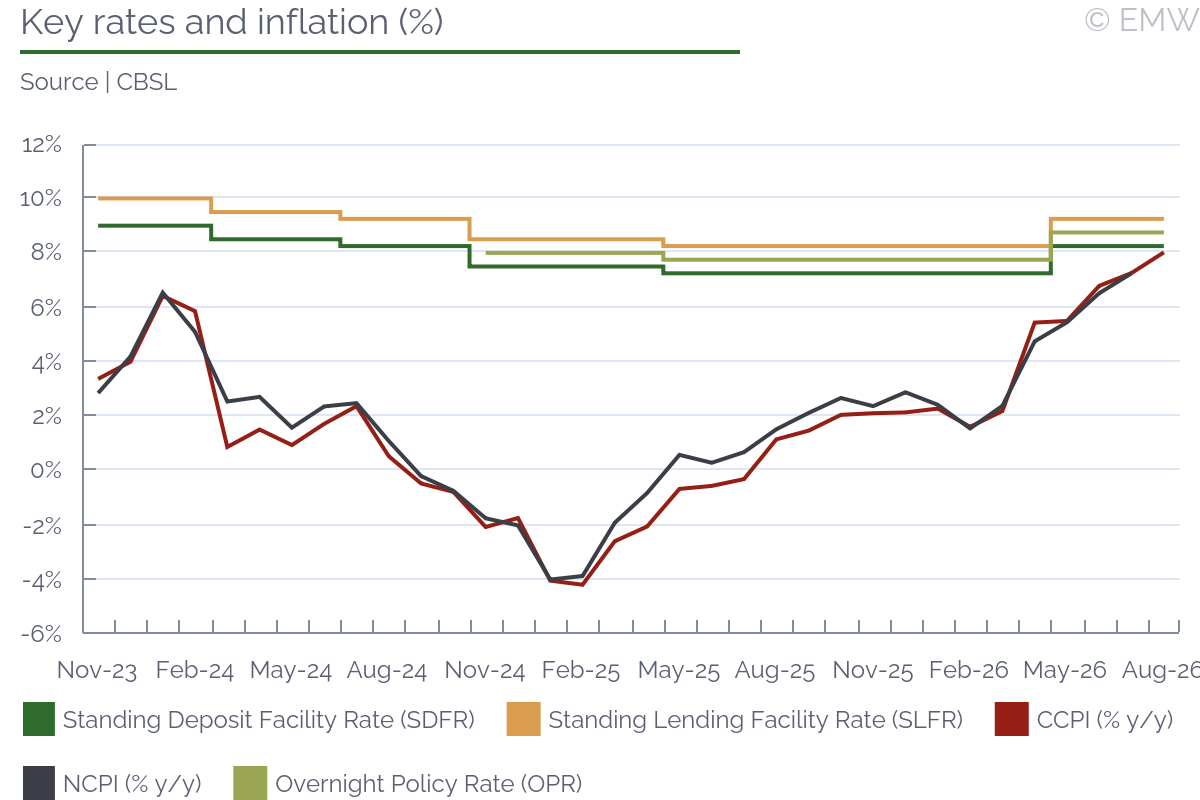
The CBSL continues to expect inflation to remain above target in the near term before easing as the effects of the energy shock dissipate and tighter monetary conditions constrain demand. Its August projections are higher than those published in February, but still envisage convergence towards 5% over the medium term. Governor Weerasinghe has said inflation should ease towards target during H1 2027, provided there is no renewed external shock.
Risks remain firmly tilted to the upside. The principal threats are renewed escalation in the Middle East, higher oil, shipping and fertiliser costs, further LKR weakness and El Niño-related disruption to food production and hydropower. The CBSL's August baseline assumed Brent crude at around USD 80/barrel in 2026 and USD 70/barrel in 2027, meaning a sustained return to materially higher prices (Brent crude has been above USD 100/barrel since early September) would challenge the current policy path. Even so, the latest inflation data do not yet make another hike our base case. The rise was anticipated, monthly inflation remains relatively contained, and the CBSL has already tightened substantially in response to the shock. The threshold for further action is therefore likely to be evidence that inflation is becoming more persistent, expectations are de-anchoring, or second-round demand pressures are intensifying.
External and Financial Conditions
The external position remains under pressure but has improved in several important respects since the July policy meeting. The current account recorded a USD 142mn deficit in July, its fourth consecutive monthly shortfall, taking the cumulative deficit during Jan-Jul to USD 387mn. The merchandise trade deficit widened to USD 6.51bn, from USD 3.85bn a year earlier, as imports rose 25.8% y/y to USD 14.64bn while exports increased only 4.4% y/y to USD 8.14bn. Energy and vehicle imports remain the main sources of pressure. Fuel imports reached USD 3.62bn during Jan-Jul, up 59.9% y/y, while vehicle imports totalled USD 1.50bn. Tourism has also provided less support than expected: earnings during Jan-Aug fell around 10% y/y to USD 2.06bn, despite a modest return to annual growth in August.
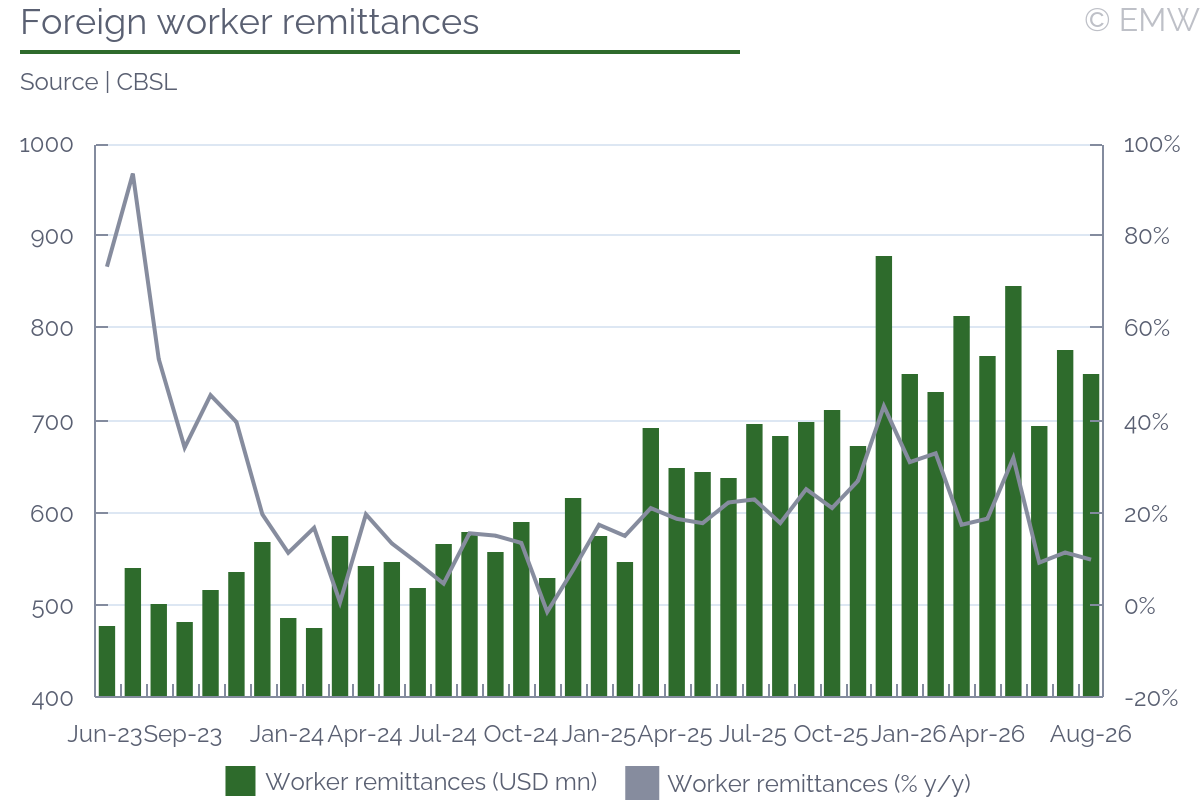
Remittances remain the strongest offset. August inflows were USD 748.6mn, up around 10% y/y, taking cumulative receipts during Jan-Aug to approximately USD 6.13bn, up 19.8% y/y. This continues to provide an important source of FX liquidity as the merchandise deficit remains wide. More importantly for monetary policy, reserve buffers strengthened materially in August. Gross official reserves rose 4.6% m/m to USD 6.91bn, from USD 6.60bn in July, while foreign-currency reserves increased 5.1% m/m to USD 6.69bn.
This improvement reduces the immediate need to use the policy rate defensively to support the currency. Exchange-rate risks have not disappeared, particularly with the current account in deficit and external debt servicing set to increase, but the combination of reserve accumulation, strong remittances and lower LKR volatility gives the CBSL more room to wait.
Growth Momentum
The growth picture has softened but remains resilient. Real GDP expanded 4.2% y/y in Q2 2026, slowing from 5.1% in Q1 but extending the recovery. The Department of Census and Statistics reported that industry grew 7.3%, services expanded 2.7%, and agriculture contracted 2.3%. The industrial sector was the principal growth engine. Construction expanded 13.9%, mining and quarrying 17.4% and manufacturing 3.2%. Services growth slowed from the previous year, reflecting weaker tourism and softer performance in some financial and hospitality activities, while agriculture was held back by lower rice, fishing and plantation output.
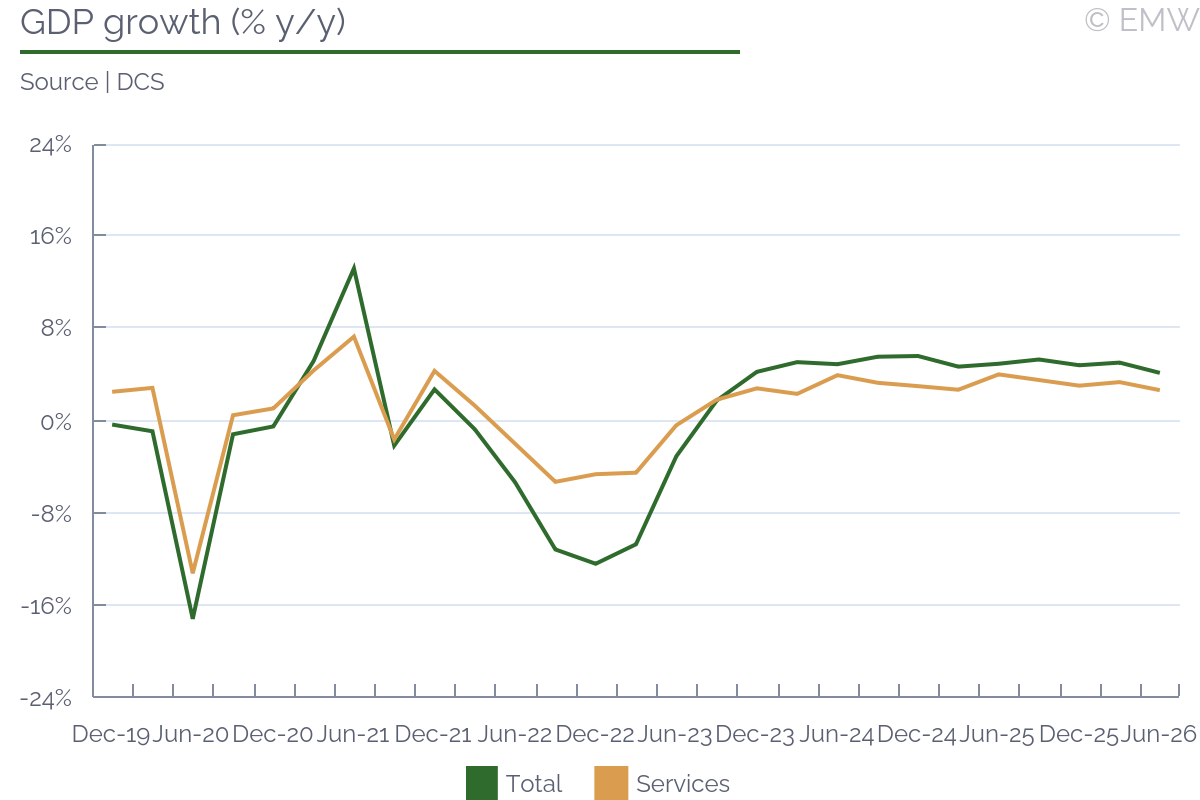
More recent activity indicators remain broadly supportive but show some moderation. The Manufacturing PMI remained expansionary at 53.0 in August, although production moved below the neutral threshold and new orders were flat. By contrast, the Services PMI strengthened to 65.6, led by transport, wholesale and retail trade and professional services.
The CBSL continues to see 4-5% real GDP growth in 2026. Fitch's latest assessment is broadly consistent with that range, forecasting 4.1% growth this year and just over 4% over the medium term. The balance of risks remains skewed lower because of energy vulnerability, weaker tourism, El Niño and global trade uncertainty. This moderation in growth also argues against further tightening unless the inflation outlook deteriorates substantially. The CBSL now has to balance above-target inflation against the risk of unnecessarily constraining an economy that is already slowing from the stronger pace recorded in 2024-25.
Conclusion
The data since July have moved in both directions, but not enough to alter our call. Inflation has risen further and is now above the CBSL's tolerance band, but much of the increase continues to reflect food, energy and other supply-side pressures rather than a renewed acceleration in demand. Core inflation has increased, making it an important watchpoint, but expectations remain broadly anchored, and monthly headline price momentum remains relatively contained.
We therefore expect the CBSL to hold the OPR at 8.75% on Sep 30 and maintain it through the remainder of 2026. The May 100bps increase still looks like a front-loaded response to the energy and exchange-rate shock, rather than the first step in a sustained hiking cycle. The principal trigger for a change in this view would be a clear deviation from the CBSL's baseline: a sustained inflation overshoot accompanied by stronger core pressures, renewed disorderly LKR depreciation or a fresh energy shock that materially worsens the medium-term inflation path. In the absence of those developments, the hurdle for another hike remains high.
Further reading
| Ask the editor | Back to contents |
| BOT’s MPC likely to maintain policy rate at 1.00% in October |
- Next MPC meeting: Oct 28
- Current policy rate: 1.00%
- EmergingMarketWatch forecast: Hold
- Rationale: MPC statement of Aug 26
We think that BOT's Monetary Policy Committee (MPC) will keep the policy interest rate unchanged at 1.00% in its meeting on Oct 28, the fifth one for 2026. On Wednesday (Aug 26), the MPC voted unanimously to maintain the key rate at 1.00%. In line with expectations, this was the third consecutive hold decision.
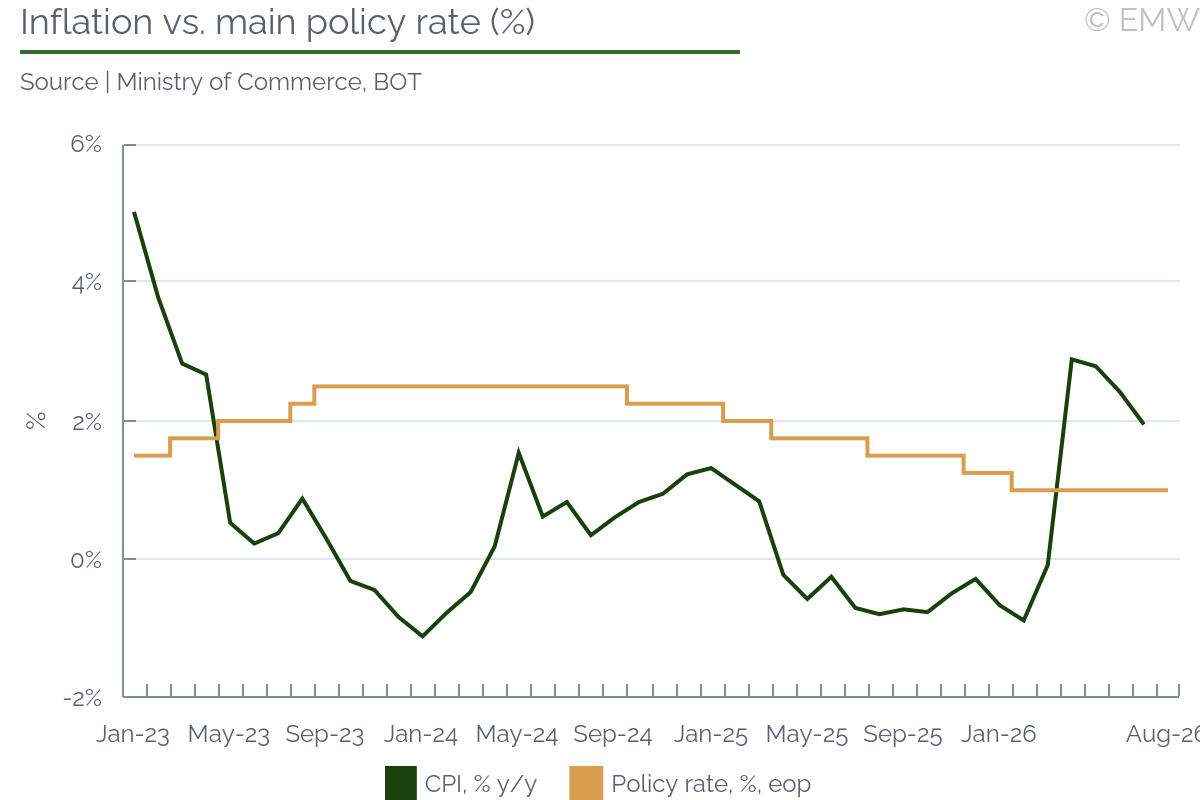
The prevailing monetary policy framework aims at maintaining price stability, supporting sustainable growth and preserving financial stability. The MPC's view is that the current key rate level is appropriate to support economic recovery. Inflation has risen temporarily due to supply-side factors, and the MPC will continue to monitor the inflation outlook and the associated risks in the future.
Economic growth
Thailand's overall economic growth remains low and uneven, the press release said. It has benefited from the technology and artificial intelligence (AI) cycle. The latest projection of GDP growth in 2026 and 2027 is largely in line with the June forecast, which was 2.3% and 1.8%, respectively.
Goods exports and private investment have risen faster than expected, driven mainly by the technology and AI cycle. However, the share of imported inputs used in goods exports has increased, and the recent investment growth has generated only limited employment gains for Thais. The press release noted persisting adaptation challenges and intense competition faced by SMEs. Meanwhile, the growth of private consumption has been slower-than-expected.
The MPC sees a need for monitoring private consumption after the government support measures expire, and the spillovers from the technology and AI cycle.
Inflation
The MPC now expects that headline inflation in 2026 and 2027 will be lower than the previous projection, primarily on the back of global energy prices. The MPC's latest forecast is of slightly lower core inflation due to lower-than-anticipated cost pass-through. Nonetheless, the committee expects headline inflation to accelerate through Q1 2027 due to the impact of El Niño and gradual cost pass-through. After that, inflation will ease to low levels because of base effects and weak domestic demand. The MPC said that medium-term inflation expectations continue to be anchored within the 1-3% target range.
The committee said it will monitor uncertain developments related to the Middle East conflict, cost pass-through by companies, and medium-term inflation expectations going forward.
We note that in June the MPC projected headline inflation of 2.8% in 2026 and 1.4% in 2027. Core inflation was seen at 1.5% and 1.4%, respectively.
Lending
Credit growth has accelerated, driven mainly by large companies. While part of the lending to large corporates reflects new investment, the bulk of it is for working capital. The contraction of SME loans has persisted because lenders continue to be cautious in extending financing to high-risk borrowers. While overall loan quality has been stable, SME loan quality has deteriorated.
The MPC sees a need for continued monitoring of the debt repayment ability of SMEs and vulnerable households. The committee also called for greater targeted support to vulnerable groups and potential SMEs.
Exchange rate
The exchange rate of the Thai baht is USD/THB 32.765 at the time of writing, which compares with USD/THB 33.705 on Jun 24, the date of the previous MPC meeting. The exchange rate was USD/THB 31.500 on Dec 31, 2025.
The USD/THB has been volatile, driven by Middle East geopolitical developments and shifting market expectations about the path of US monetary policy, the MPC said.
Further reading
| Ask the editor | Back to contents |
| BCT likely to hold at 7.00% in September but oil shock raises policy risks |
Next announcement: likely end of Sep
Current policy rate: 7.00%
EmergingMarketWatch forecast: 7.00%
Tunisia's monetary policy framework is centred on a price-stability mandate implemented through an interest rate-based operational framework but the BCT does not operate a formal inflation targeting regime or announce a numerical inflation target. Under the 2016 BCT Statute, price stability is the central bank's primary objective, while it also contributes to financial stability and supports the broader economic objectives of the state. The operational framework is set out in a 2017 Circular which stipulates that the policy rate is the main monetary policy instrument and the overnight interbank rate is the operational target. The BCT seeks to keep the overnight rate close to the policy rate through liquidity operations, standing lending and deposit facilities and reserve requirements.
The exchange rate is an important additional dimension in the framework. Tunisia formally operates a flexible exchange rate, but the dinar remains closely managed and the BCT intervenes materially in the FX market. The IMF historically characterised the regime as crawl-like, after the dinar had previously been managed against a euro/dollar basket, and has repeatedly advocated greater exchange rate flexibility as part of a transition towards a clearer interest rate-based monetary framework. In practice, EUR/TND has remained relatively stable and the exchange rate objective interacts directly with monetary policy. FX sales to support the dinar withdraw domestic liquidity, which the BCT can offset through refinancing of the banking system. This means that the policy stance cannot be assessed only through the headline policy rate.
The external constraints on monetary policy currently stem from Tunisia's dependence on imported energy. Higher oil prices widen the trade and CA deficits, increase demand for foreign currency and can put pressure on both reserves and the dinar. If the BCT seeks to limit currency depreciation, a persistent oil shock limits its scope to ease monetary policy even if domestic activity would otherwise favour lower rates. Capital controls give the BCT considerably more monetary autonomy than a conventional currency peg but the available reserve buffer ultimately limits how far exchange rate stability and easier domestic monetary conditions can be pursued simultaneously.
The BCT does not publish a regular forward calendar for monetary policy decisions. Under the BCT Statute, the Board meets once every two months and must publish a communiqué on economic and financial conditions and monetary policy measures at the same frequency. The most recent meeting was held on Jul 29, when the Board kept the policy rate at 7.00%, making a meeting in the Sep 28-30 window the most likely timing for the next decision. In July, the BCT already highlighted upside inflation risks, the elevated energy bill and the need to preserve an adequate level of FX reserves.
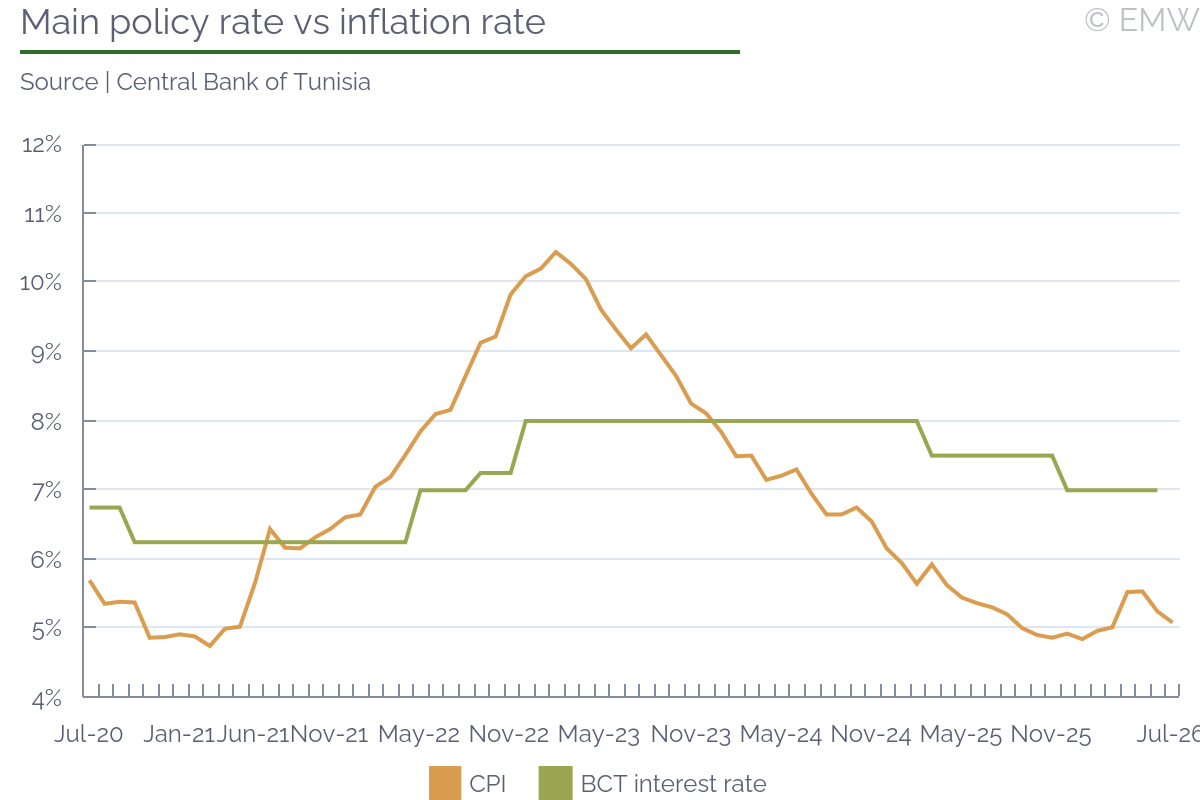
We expect the BCT to keep the policy rate unchanged at 7.00% as the acceleration in inflation would not be sufficient in our view to require an immediate hike. Headline inflation accelerated to 5.4% y/y in August from 5.1% y/y in July, while core inflation excluding food and energy edged up to 4.9% y/y from 4.8% y/y. Food inflation was the main driver, accelerating to 7.8% y/y. At the same time, the 7.00% policy rate remains 1.6pps above current headline inflation, suggesting that monetary conditions remain restrictive. Economic activity has also strengthened without pointing to obvious demand overheating, with GDP rising 1.4% q/q s.a. and 2.3% y/y in Q2.
The stronger argument for caution comes from the external balances. The CA deficit widened to TND 4.24bn, or 2.3% of GDP, in H1 from TND 2.84bn, or 1.6% of GDP, a year earlier, largely reflecting the increase in the energy import bill to TND 8.50bn from TND 6.37bn. The deterioration continued through August as the merchandise trade deficit widened to TND 17.85bn in Jan-Aug from TND 14.64bn a year earlier, while the energy deficit increased to TND 8.93bn from TND 7.15bn. Net FX reserves stood at TND 24.72bn, equivalent to 97 days of imports, on Sep 21, up from 92 days immediately after the EUR 700mn Eurobond repayment in July but below 109 days in February.
We therefore see a hold as the most likely September outcome but we think that the risk balance is shifting towards tightening. The BCT can probably look through part of the current food and energy driven inflation increase while the exchange rate remains stable and core inflation stays below 5%. However, a sustained oil shock that further widens the external deficit, erodes reserves or begins to feed more visibly into the dinar and underlying inflation would materially strengthen the case for a rate hike at subsequent meetings.
| Ask the editor | Back to contents |
| Central bank under pressure to increase key rate again |
- Current rate: 15.5%
- Next rate decision: Sep 17
- Our forecast: another rate hike by 50bps or, less likely, rate on hold
The central bank (NBU) is likely to increase its key rate again tomorrow after unexpectedly raising it by 50bps on Jul 30, but we would not rule an on-hold decision either. Although the headline CPI inflation edged up to 8.1% y/y in August from 7.7% in July, which was slightly higher than projected by the NBU in July, core inflation stayed flat, which was slightly below NBU projections, according to the NBU's inflation commentary from Sep 10. The NBU expects that price pressures will keep rising, but this may not be enough to merit another hike right now, so a pause in the tightening cycle is possible.
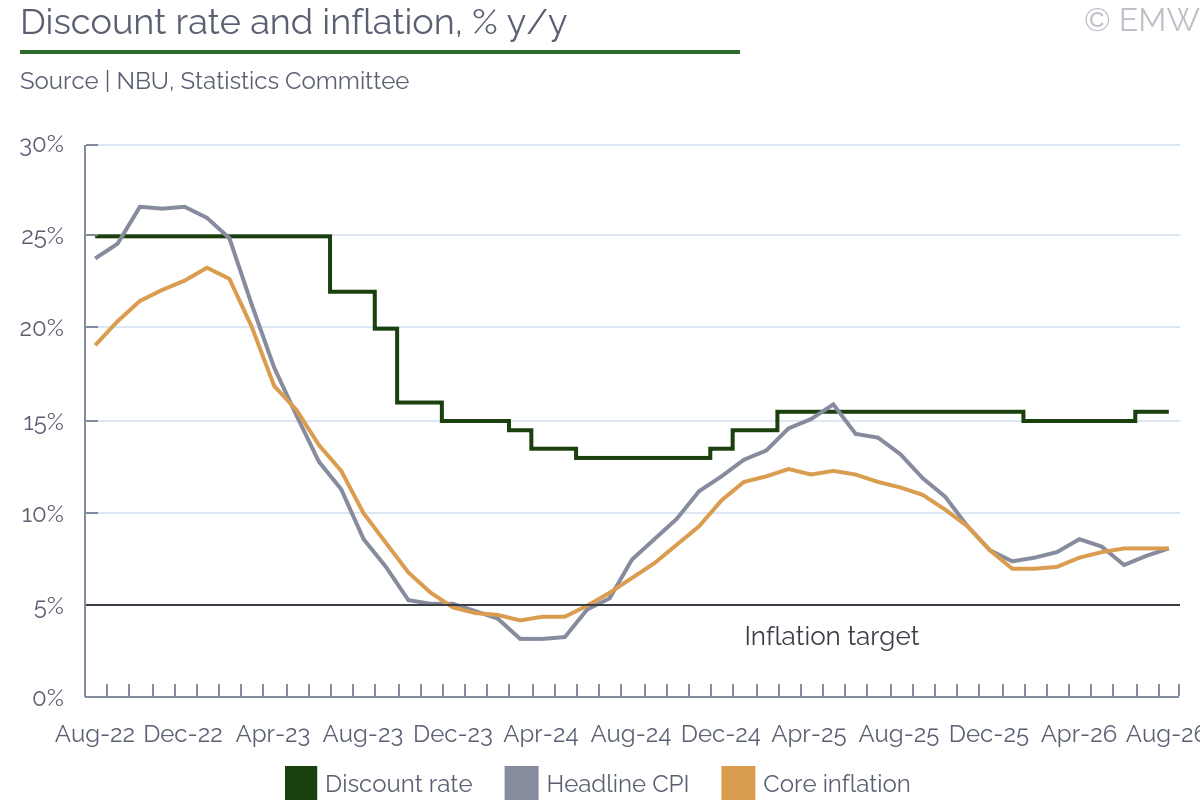
Nine MPC members out of 11 supported the 50bps rate hike at the Jul 29 meeting, according to the summary of the meeting published by the NBU on Aug 10. They argued that the core inflation acceleration early in the summer showed signs of a sustained trend and that pro-inflationary risks intensified. Furthermore, most MPC members argued at the time that it would be necessary to keep raising the key rate in 2026.
The NBU expects that damage to logistics infrastructure from the intensification of Russian missile and drone strikes on civilian infrastructure in Q3 2026 could add 0.4-0.6pps to annual inflation by end-2026, according to a recent column by NBU deputy governor Volodymyr Lepushynsky in Interfax-Ukraine. The most recent official NBU inflation forecast, from early August, was for 10% at end-2026. Current budget problems, unstable fuel prices, and fears of delayed international assistance increase uncertainty amid the war. At the same time, domestic food oversupply due to the export bottlenecks owing to Russian strikes on the seaports and border crossings is pushing food prices in Ukraine down.
| Ask the editor | Back to contents |